Turkey’s Treasury will tap domestic investors tomorrow with auctions of 2-year and 4-year fixed-rate bonds, a routine funding move that still carries outsized importance for a country where borrowing costs, inflation expectations and demand for lira assets remain tightly linked.
Turkey Treasury to auction 2-year and 4-year bonds
For investors, these sales are more than a calendar item. They are a fresh read on how much compensation the market wants to lend to the Turkish government at the short and intermediate end of the curve, and whether demand is strong enough to suggest confidence in policy credibility. In an economy still working to restore price stability, every refinancing operation is a test of financing conditions.
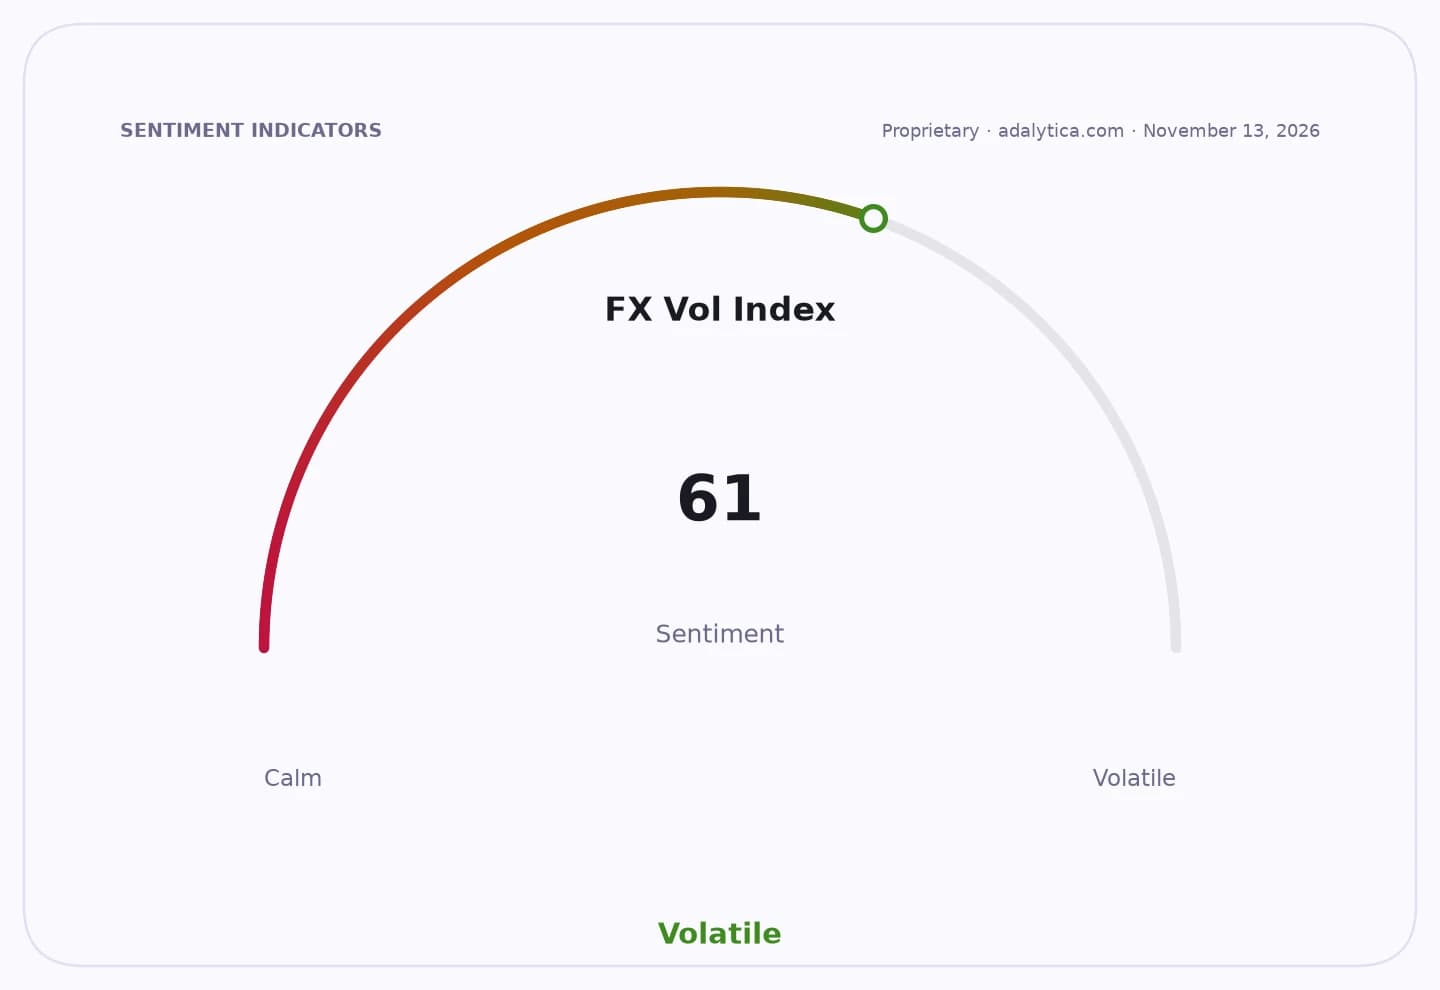
Sentiment Indicators
The Ministry of Treasury and Finance said it will reissue a 2-year bond due in 672 days and a 4-year bond due in 1,617 days, both with semiannual coupon payments. Reopenings are a standard way for governments to raise money, but they matter because they help reveal the pricing of sovereign risk at the front and belly of the curve, where investors are often most sensitive to shifts in monetary policy and inflation.
That backdrop makes the auction timing notable. Global bond markets have been under pressure, with the U.S. 10-year Treasury yield recently around 5.1% and the 2-year near 4.9%, levels that keep pressure on emerging-market funding costs. When developed-market yields are elevated, borrowers such as Turkey usually need to offer more attractive terms to clear auctions, especially if local demand is cautious.
Market signals around sovereign debt have been mixed. U.S. Treasury bond sentiment has been described as neutral, while Adalytica’s dollar trade signal shows extreme greed, underscoring how firm the greenback remains. For Turkish issuers, a stronger dollar and higher global yields can tighten conditions even if domestic buyers stay engaged.
The real question for investors is whether the auction clears comfortably and at what yield. Strong demand would support the view that domestic institutions still have appetite for duration in lira assets, which can help anchor the yield curve and ease pressure on future borrowing. A weak outcome would point to higher funding costs ahead and could spill over into broader Turkish fixed income, the currency and bank balance sheets that hold large amounts of government paper.
For long-term investors, the story is not about one auction alone. It is about whether Turkey can keep financing itself without forcing yields materially higher, and whether that process remains compatible with disinflation and policy normalization. Tomorrow’s sales will offer another data point on that path, and they are worth watching closely.
| Entity | Gains | Losses |
|---|---|---|
| Turkey’s Treasury | ▲Fresh funding access | ▼Higher borrowing costs if demand weakens |
| Domestic bond buyers | ▲Attractive yield pickup | ▼Price risk if yields rise |
| Turkish banks | ▲Portfolio income from sovereign paper | ▼Mark-to-market pressure on holdings |
| Global bondholders | ▲Opportunity to compare sovereign risk | ▼Exposure to a firmer dollar and higher rates |