UEW Co-operative Credit Union is lowering the cost of borrowing to deepen member savings, a move that matters because cheaper credit can strengthen household cash flow, encourage formal savings and support small-scale economic activity in Ghana.
UEW Credit Union Cuts Loan Rate to 13.5%
The credit union said it has reduced its loan rate from 18% to 16% last year and then again to 13.5% this year as it tries to make borrowing more affordable while promoting a regular savings habit among members. For a co-operative lender, that is not just a pricing decision — it is the core of the business model. Credit unions rely on steady deposits from members, and a stronger savings base gives them more room to lend without stretching the balance sheet.
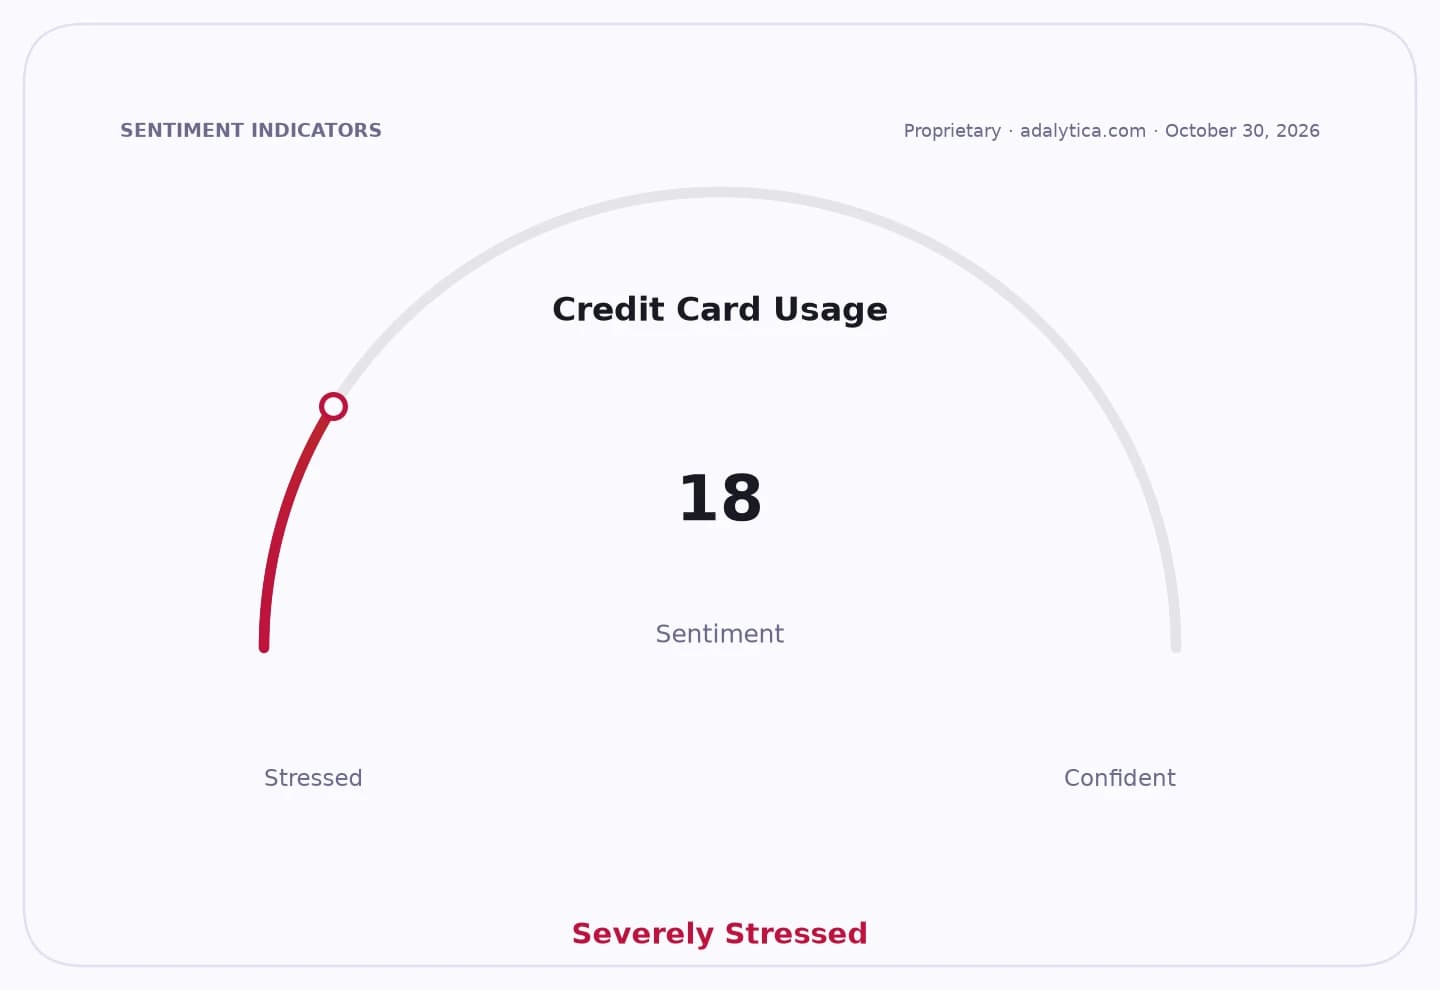
Sentiment Indicators
That is why the institution is pairing lower rates with a broader push into regular savings accounts, child savings products, fixed deposits and fixed savings plans. It is also targeting borrowers who often struggle to access conventional bank credit, including petty traders, farmers and members seeking guarantor-backed loans. In practical terms, cheaper loans can help a small trader restock inventory, a farmer bridge seasonal cash needs or a household manage short-term expenses without turning to more expensive informal lenders.
UEW’s move also fits a wider pattern across the credit market, where lenders are trying to widen access while staying disciplined on risk. The credit union has added USSD and web portal services so members can deposit savings, check balances, generate statements and apply for loans remotely, lowering the friction that often keeps low-income savers out of formal finance. That matters for long-term growth because convenience is often what turns occasional users into repeat depositors.
The institution’s confidence is also being reinforced by regulation. It said it has qualified for licensing by the Bank of Ghana under ongoing microfinance reforms, with licensing expected in December 2026. If that happens, it would further formalize the lender’s position in a sector where trust, governance and regulatory credibility are key to attracting deposits.
For investors and savers watching the co-operative finance space, the bigger story is that lower loan rates are being used as a tool to build loyalty, expand access and grow balances over time. If UEW can keep loan quality stable while growing regular savings, the model becomes more resilient and more scalable. That is the kind of slow-burn financial story worth watching, especially for members who value affordability and for investors who like institutions that grow by compounding trust.
| Entity | Gains | Losses |
|---|---|---|
| UEW Co-operative Credit Union | ▲More member deposits | ▼Lower loan yield |
| Members/borrowers | ▲Cheaper credit | ▼Less room for high-rate lending |
| Small traders and farmers | ▲Easier access to loans | ▼Higher-cost alternatives |
| Informal lenders | ▲None | ▼Demand for expensive credit |