UnitedHealth Group’s latest earnings beat and raised profit outlook have become the real driver behind Piper Sandler’s slight increase in its price target to $504 from $502, underscoring how quickly sentiment has improved after a volatile year for the managed-care giant.
UnitedHealth shares rise after earnings beat and outlook
The adjustment looks modest on paper, but it lands after UnitedHealth reported third-quarter results that topped profit expectations and lifted its 2026 earnings forecast. For investors, that matters more than the size of the target change: it suggests analysts are increasingly willing to underwrite a turnaround in margins and execution at a company that had been discounted for medical-cost pressure and operational uncertainty.
UnitedHealth shares have already responded. The stock jumped 5.13% on Oct. 14 after the results, closing at $395.62, far above the levels seen during the spring selloff and back above its 50-day moving average of $386.16. The move also pushed its relative strength index to 66, a sign of stronger near-term momentum, while the price remains well below the recent Bollinger upper band, leaving room for further upside if earnings stability continues.
The bigger economic issue is whether UnitedHealth can keep converting scale into earnings growth while the healthcare cost environment normalizes. In managed care, margin recovery usually depends on pricing discipline, utilization trends and the ability to absorb medical-cost inflation without losing competitiveness. UnitedHealth’s guidance upgrade suggests management believes those pressures are manageable, at least for now.
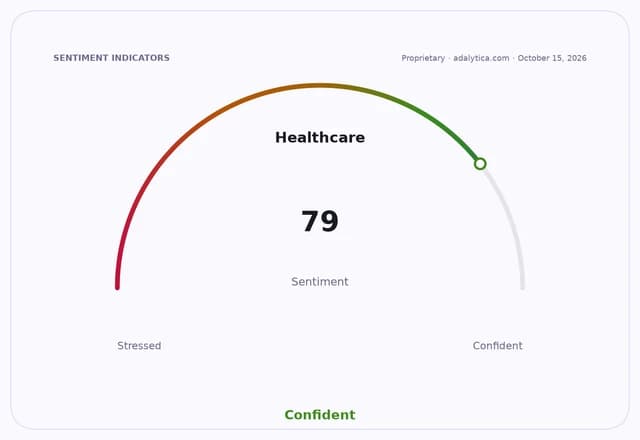
That has broader implications for the health-insurance group. UnitedHealth is the sector bellwether, and its results can influence expectations for peers such as Cigna and Humana. Cigna’s shares have also strengthened, with the stock at $289.58 and its RSI at 79.6, reflecting a strong run in the group. Humana, meanwhile, was trading at $427.40, close to its own highs, after a powerful rebound from earlier weakness. A sustained recovery in UnitedHealth would reinforce the view that investors can own managed care as a defensive growth area rather than a margin trap.
Piper Sandler’s move suggests the Street is becoming more comfortable with that narrative. The firm’s target change is small, but it comes in a market that is already rewarding evidence of earnings durability. If UnitedHealth can sustain its raised outlook into the next quarter, analysts may have room to lift estimates further and the stock could re-rate toward the high end of its historical trading range.
For now, the key question is whether this marks a durable reset or just a relief rally after a bruising correction. Investors will be watching the next earnings update, medical-cost trends and any evidence that the company can hold its improved margin profile without sacrificing growth.
| Entity | Gains | Losses |
|---|---|---|
| UnitedHealth | ▲Higher valuation support | ▼Skeptics of the turnaround |
| Piper Sandler | ▲Validation of cautious optimism | ▼Bears on managed care |
| Managed-care peers | ▲Sector read-through strength | ▼Margin-pressure narrative |
| Long-only investors | ▲Potential upside re-rating | ▼Shorts betting on cost inflation |