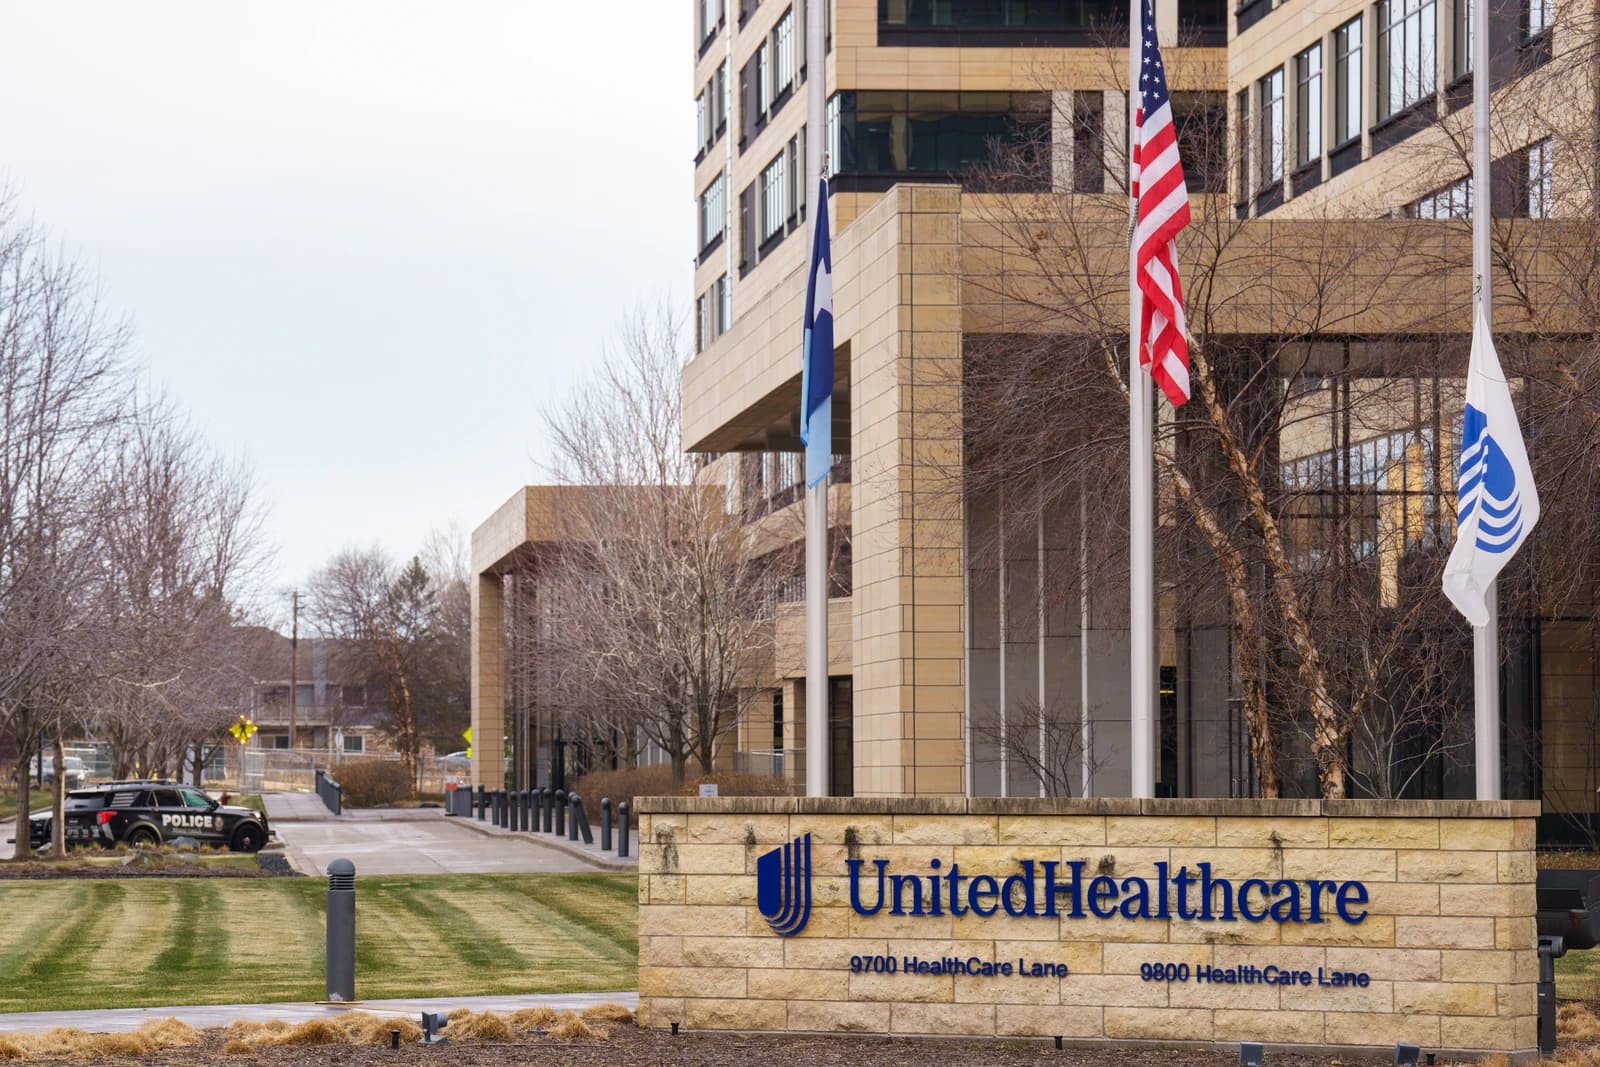
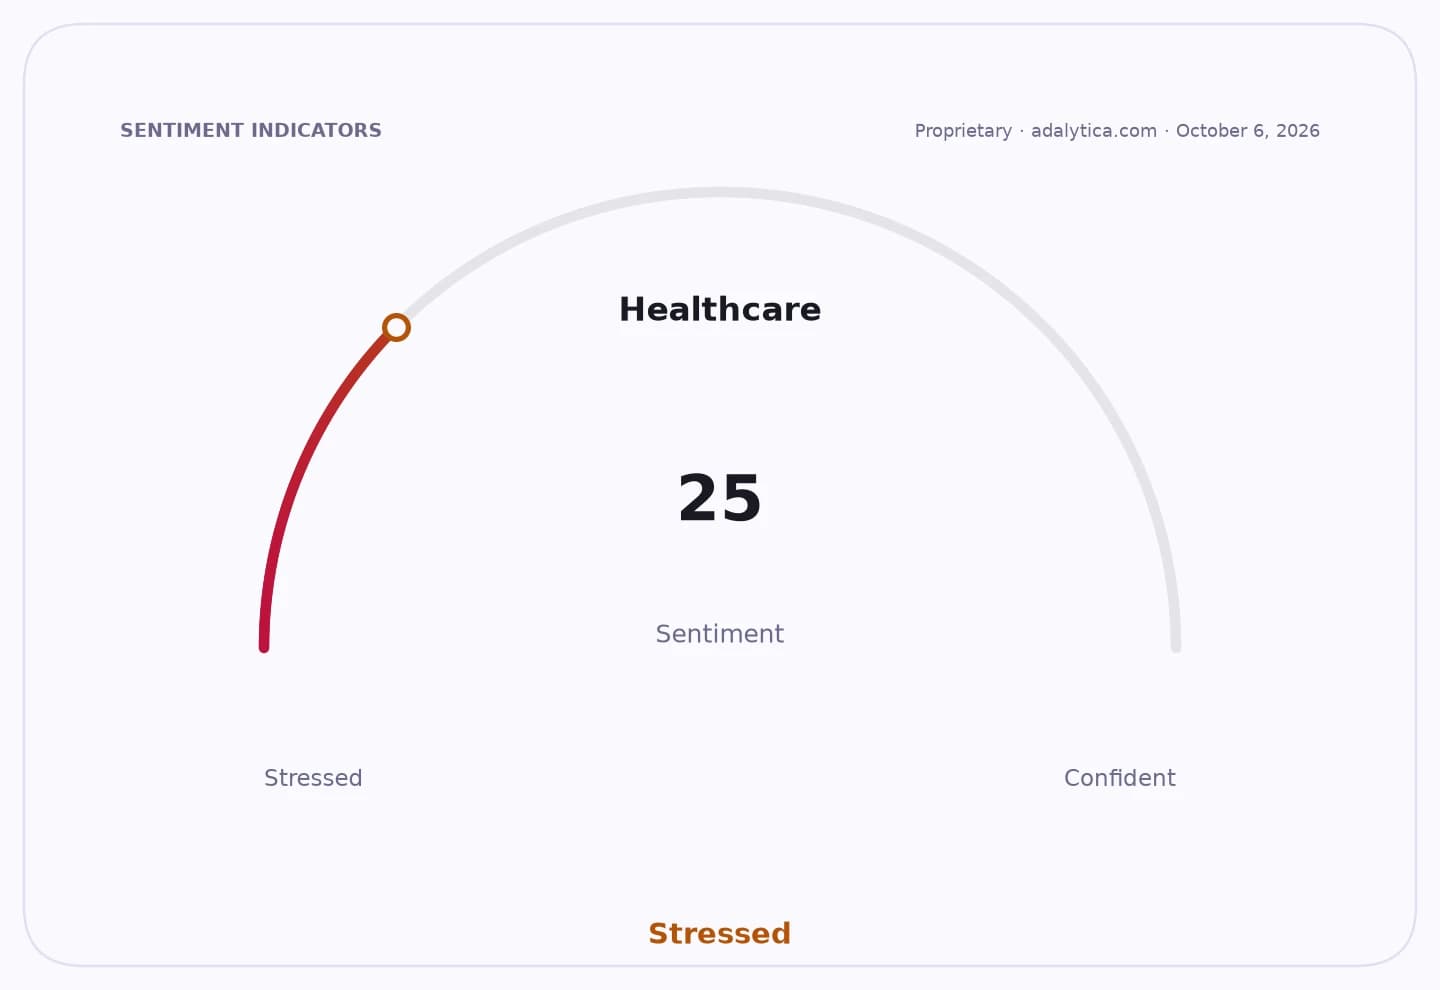
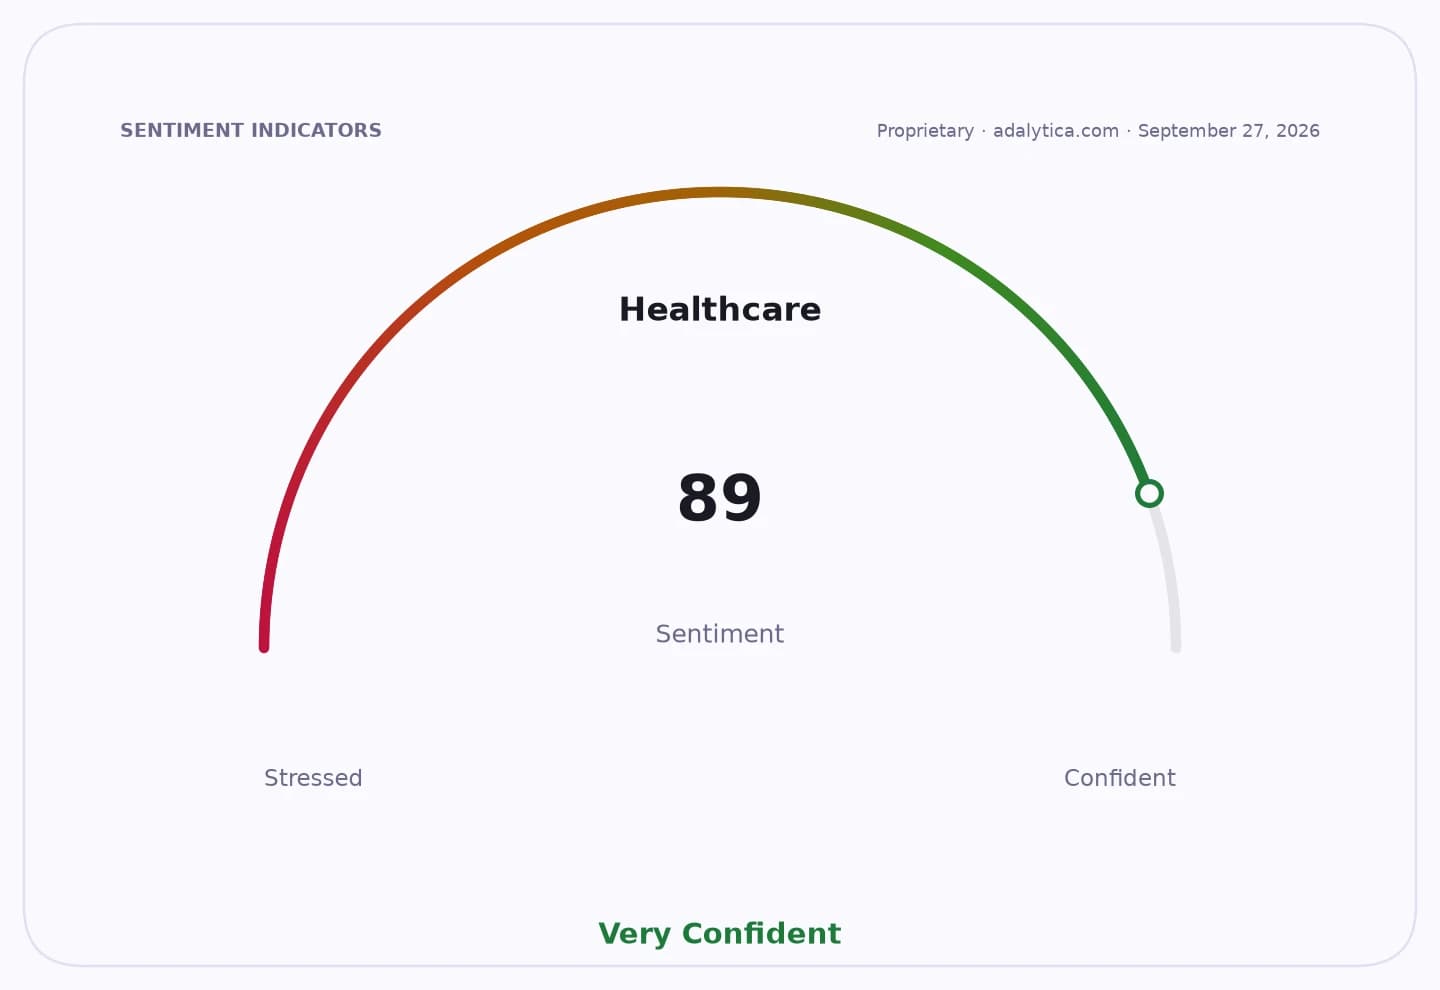
UnitedHealth Group raised its full-year profit outlook for the third time after third-quarter results showed medical costs running below expectations and left more premium income to fall through to earnings.
UnitedHealth Raises Full-Year Profit Outlook Again
The update matters because UnitedHealth is the biggest US health insurer and one of the clearest gauges of how quickly medical utilization, pricing and government program trends are pressuring the managed-care industry. The company’s ability to lift guidance again suggests the cost spike that shook investor confidence earlier this year may be stabilizing, even as the broader US healthcare system continues to face higher treatment demand and shifting reimbursement rules.
Adjusted earnings per share rose to $4.69 in the three months through September from $2.92 a year earlier, topping analysts’ estimates. Net income attributable to shareholders climbed 75% to $4.1 billion, while revenue edged down to $112.7 billion. The main driver was a lower medical-care ratio than Wall Street had expected, meaning a smaller share of premiums was spent on claims and a larger share was left to cover overhead and profit.
UnitedHealth also benefited from a $610 million reserve release tied to medical claims that never had to be paid. Chief financial officer Wayne DeVeydt said the medical-cost trend remained elevated but “very stable,” a key phrase for a sector that has spent much of 2025 wrestling with rising treatment volumes, Medicare-related pressure and regulatory scrutiny.
For investors, the guidance increase is an important signal that management’s turnaround plan is gaining traction after a volatile year. UnitedHealth earlier cut and then suspended its annual targets as medical expenses surged, before founder Stephen Hemsley returned to the helm and pushed the company toward a leaner operating model. The stock’s rise reflects renewed confidence that the insurer can restore margins without relying solely on premium growth.
Still, the recovery is not clean. The company said revenue slipped slightly and it is shrinking parts of the business, selling assets and serving fewer customers in order to generate more profit from a smaller base. That can support earnings in the near term, but it also raises questions about growth once one-off reserve releases fade and if utilization trends worsen again.
The broader significance goes beyond UnitedHealth. Managed-care peers are watching closely because any sustained easing in claims pressure would help the whole group, while a fresh cost surge would likely weigh on the sector and keep pressure on valuations. For now, the third straight profit-target increase gives bulls a stronger case that the worst of UnitedHealth’s 2025 earnings reset may be over, even if the industry backdrop remains unsettled.
| Entity | Gains | Losses |
|---|---|---|
| UnitedHealth | ▲Higher earnings outlook | ▼Less room for growth |
| Shareholders | ▲Margin recovery | ▼Ongoing regulatory risk |
| Managed-care peers | ▲Better cost signal | ▼Pressure to match results |
| Patients/providers | ▲-- | ▼Stricter utilization control |