President Donald Trump’s tariffs are helping push more auto investment into the U.S., but the biggest costs are falling on suppliers, leaving the industry with only a partial gain and a still-cloudy outlook.
U.S. Auto Tariffs Shift Investment to Suppliers
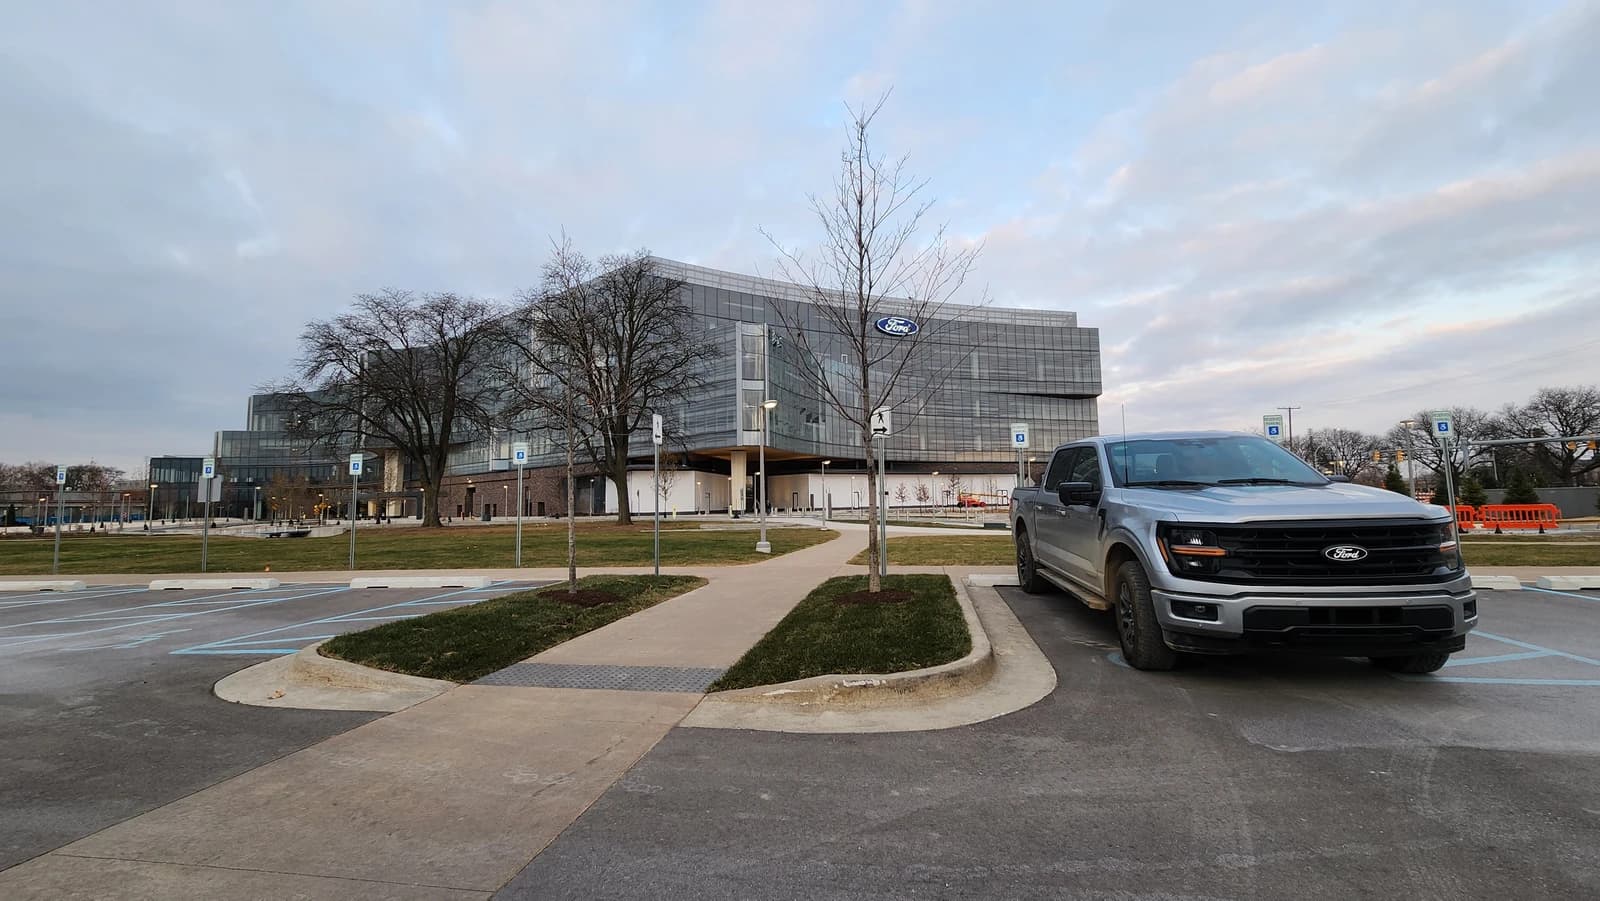
Since Trump returned to the White House, General Motors, Toyota, Ford and other automakers have announced U.S. plant expansions or production shifts from overseas as they try to make use of underused capacity and avoid the hit from the 25% levy on imported autos. But the broader economic payoff remains limited because tariff uncertainty is discouraging longer-term spending, especially among parts makers.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That split matters because suppliers employ about 930,000 people in the United States and sit at the center of the industry’s cost base. Industry economist Tyler Harp of the Center for Automotive Research said suppliers are more exposed to tariffs and less able to absorb them than automakers, making them the most vulnerable link in the chain.
The pressure is showing up in capital spending. CAR data cited in the report show supplier investment plunged from more than $8 billion in the first quarter of 2025 to about $600 million in the next two quarters before recovering somewhat. Deloitte said the industry has recouped only about half of tariff-related costs, leaving a sustained margin drag that is likely to weigh on supplier financials.
For investors, that means the tariff story is not a clean win for Detroit. Automakers may benefit from redirected production and better use of existing plants, but margins remain exposed to policy swings, and the supplier base could face weaker earnings, tighter cash flow and more automation-driven restructuring.
The jobs data also point to a mixed outcome. US auto employment rose to just under 1.8 million in September, almost 1% above January 2025 levels, but still more than 2% below the peak reached in July 2024. Production has been broadly stable and is not expected to rise meaningfully until around 2030, when major investments from GM and Toyota come onstream.
The biggest near-term risk is policy instability. Tensions with Canada have clouded the North American trade framework, while reversals of US support for electric vehicles add another layer of uncertainty for suppliers and carmakers planning multiyear capital projects.
For now, the industry is leaning toward automation and “discipline-over-growth,” according to Deloitte, with companies preferring efficiency and robotics over aggressive expansion until the tariff regime and USMCA outlook become clearer.
| Entity | Gains | Losses |
|---|---|---|
| GM, Ford, Toyota | ▲More US production plans | ▼Higher input and policy costs |
| Auto suppliers | ▲Limited volume upside | ▼Margin pressure, weaker capex |
| US factories/workers | ▲More plant utilization | ▼No broad employment boom yet |
| Trump tariff agenda | ▲Some reshoring headlines | ▼Uncertain long-term industry investment |