U.S. business inventories rose 0.4% in August, matching expectations but slowing from July’s revised 0.9% increase, a sign firms are still rebuilding stock without adding much fuel to GDP.
U.S. business inventories rose 0.4% in August
The Census Bureau said inventories climbed to $2.819 trillion, while retail inventories increased just 0.2% after jumping 0.9% in July. The more moderate pace suggests companies are becoming more cautious about restocking as demand normalizes and borrowing costs remain elevated, limiting the risk of a sharp inventory-led boost to growth.
Inventories matter because they are one of the most volatile components of gross domestic product. When stockpiles rise faster than sales, they can temporarily lift output; when they slow, they can restrain it. The August data points to a softer contribution from inventory accumulation in the third quarter than the July pace implied, even if the level of stocks remains historically high.
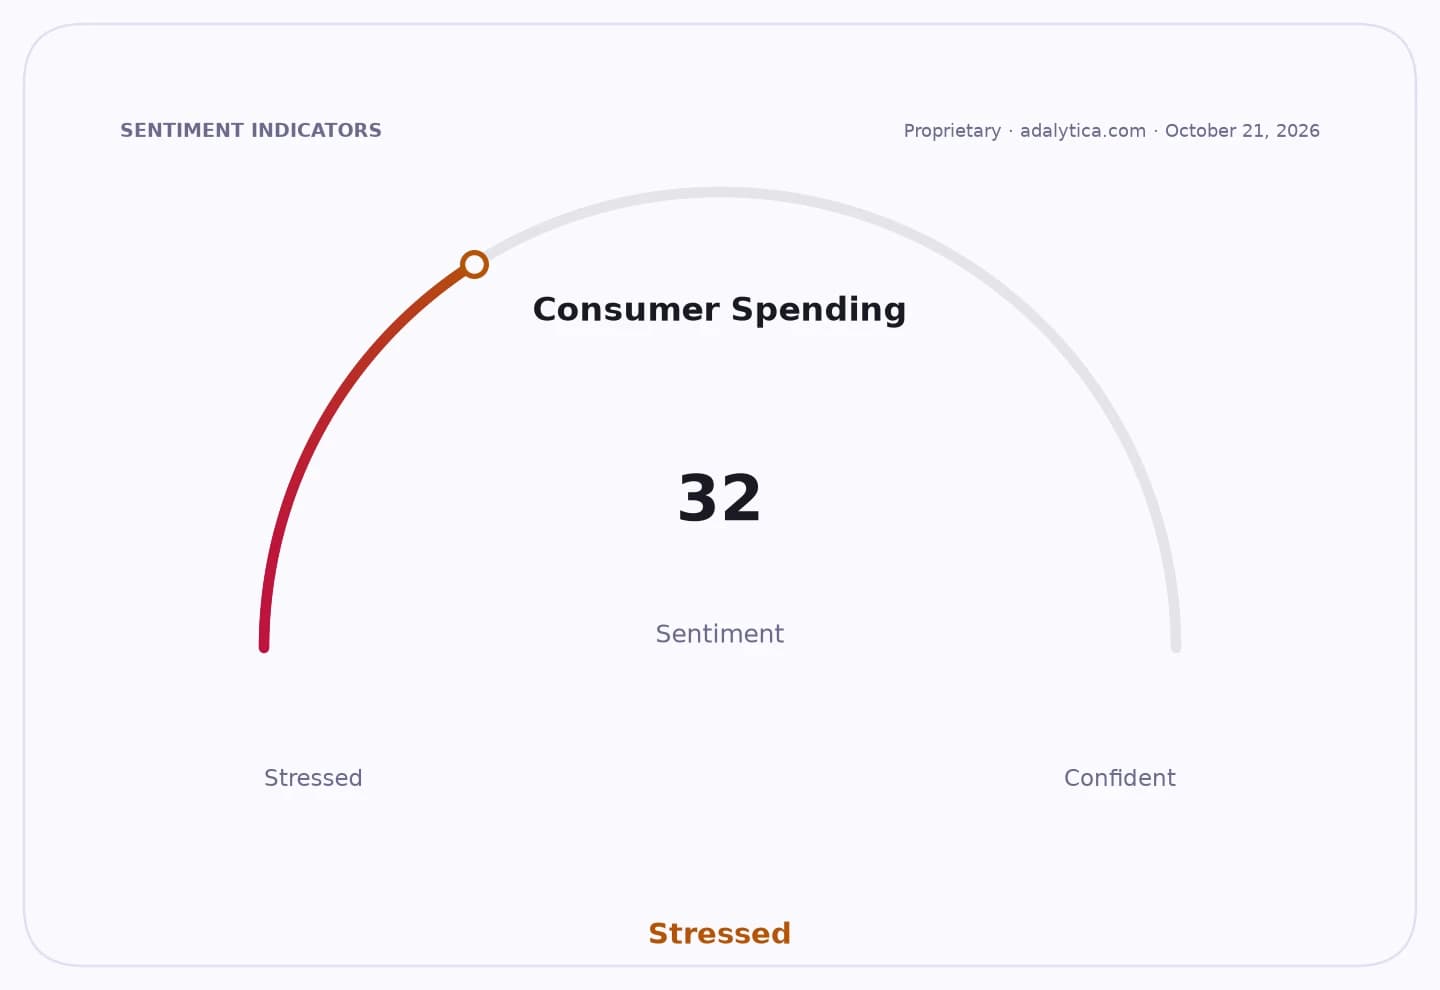
For markets, the report is a read on the balance between supply and demand rather than a standalone catalyst. A slower build in retail inventories can be consistent with healthier sell-through at stores, but it can also reflect managers resisting over-ordering ahead of uncertain consumer spending. That makes the trend relevant for companies tied to logistics, transportation, wholesalers and discretionary retail, where excess stock can pressure margins and trigger discounting.
The latest figures also fit a broader pattern of inventories growing, but not at a rate that would suggest a significant reacceleration in domestic demand. The inventory-to-sales ratio held near 1.33, close to recent readings, indicating businesses are neither severely overstocked nor aggressively under- stocked. That balance reduces the risk of a sharp correction, but it also limits the chance that inventories become a major engine of growth.
Investors will now focus on whether sales strengthen enough to justify current stock levels. If demand firms, the slower inventory build could support margins and reduce markdown risk. If sales soften, even a modest rise in stockpiles may become a headwind for earnings and production planning. The key implication is that inventories are no longer a growth tailwind in the way they briefly were earlier in the quarter, and that leaves the next set of retail sales and production data more important for the outlook.
| Entity | Gains | Losses |
|---|---|---|
| Retailers | ▲Lower markdown risk | ▼Slower restocking momentum |
| Manufacturers | ▲More stable ordering | ▼Less inventory-led GDP lift |
| GDP growth | ▲Less inflationary stock build | ▼Smaller third-quarter boost |
| Consumers | ▲Potentially leaner shelves | ▼Less discount-driven demand support |