The US Treasury sharply lowered its estimated fourth-quarter borrowing need to $618 billion, a sign that federal funding pressure is easing even as markets remain focused on the path for rates and bond issuance.
US Treasury Lowers Fourth-Quarter Borrowing Need
The reduction in supply is important because Treasury auctions help set the tone for global fixed-income markets and benchmark everything from mortgage rates to corporate borrowing costs. A smaller-than-expected funding requirement can reduce near-term pressure on yields, especially in a market already parsing whether the Federal Reserve will keep policy restrictive for longer.
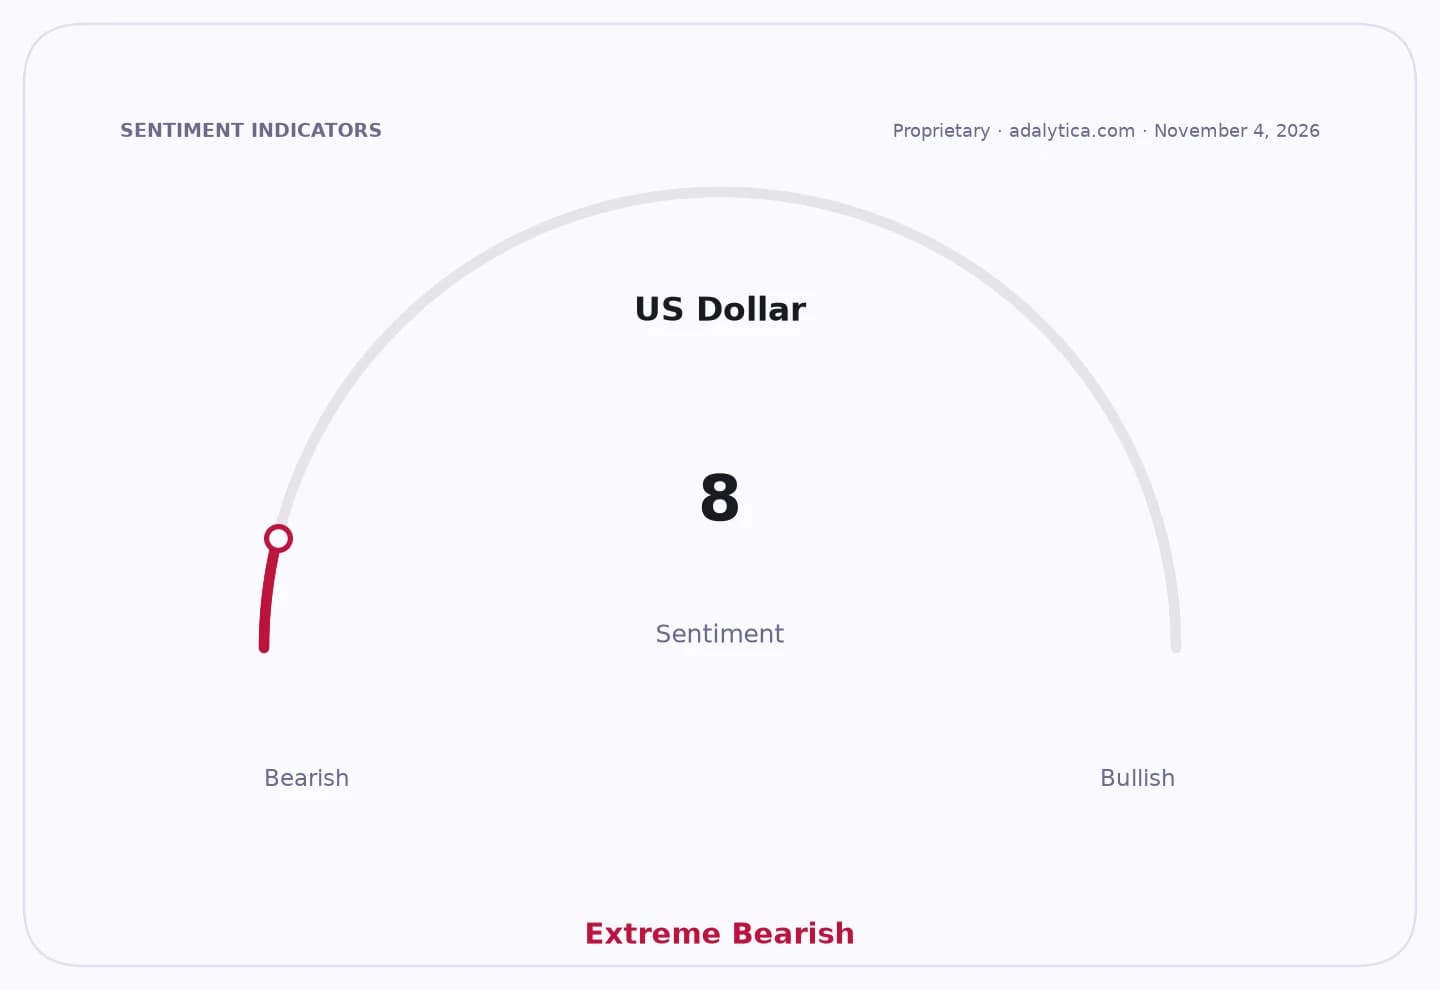
Sentiment Indicators
Treasury’s financing update comes as the 10-year yield has hovered around 4.94% to 5.05% in recent sessions, while the Fed funds rate is projected near 3.89% for November. Those levels keep short- and long-dated borrowing costs elevated by recent standards, making any sign of lighter government issuance meaningful for duration-sensitive investors.
Bond prices had already been firming before the financing announcement, with the iShares 20+ Year Treasury Bond ETF, TLT, rising to $81.16 from $79.46 on Oct. 19 before easing back. The 10-year note and intermediate-duration ETFs also showed a bid, reflecting investor appetite for government debt as inflation and recession risks remain in the background.
The Treasury revision also lands against a macro backdrop in which recession indicators remain subdued, but not irrelevant. The latest read on US recession probability stayed at zero in the data provided, suggesting policymakers are not dealing with a near-term downturn even as they manage a large financing calendar.
For investors, the key question is whether lighter borrowing will temporarily support Treasuries and widen demand for duration, or whether the market will quickly refocus on Fed policy and the still-high absolute level of rates. The next catalyst will be Treasury’s detailed auction schedule and any shift in the Fed’s messaging on cuts.
| Entity | Gains | Losses |
|---|---|---|
| Treasury bond investors | ▲Less supply pressure | ▼Fewer yield concessions |
| US government | ▲Easier financing conditions | ▼Less room to fund deficits cheaply |
| Borrowers tied to yields | ▲Potentially lower rates | ▼Slower relief if Fed stays tight |
| Short-duration cash holders | ▲Higher carry remains attractive | ▼Miss upside if yields fall |