Welltower’s faster dividend growth is winning the market’s attention, but Ventas still pays retirees the bigger cash yield today, and that is the real trade-off for income investors weighing the two senior housing REITs.
Ventas vs Welltower: Yield and Dividend Growth
The comparison matters because senior housing remains one of the clearest ways to play aging demographics, and both landlords have now lifted 2026 guidance after second-quarter results. For retirees, the choice is less about which company has the better long-term story and more about whether to prioritize immediate income or faster payout growth backed by stronger balance-sheet flexibility.
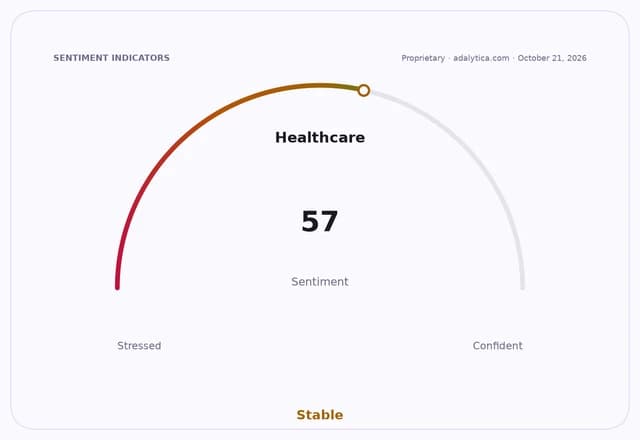
Sentiment IndicatorsⓘProprietary · adalytica.com · October 21, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Ventas currently pays $0.52 a quarter, or $2.08 annually, for a yield of about 2.4% at $85.82. Welltower pays $0.85 a quarter after a 15% increase, or $3.40 a year, but its yield is only about 1.5% because the stock has surged 37.18% over the past year.
That makes Ventas the better payer today, but Welltower the faster grower. Both companies cut dividends in 2020 and both have since rebuilt payouts, with Ventas still below its pre-cut rate and Welltower nearly back to its old level.
On coverage, the two are nearly tied. Ventas’ dividend uses about 54% of its $3.88 normalized funds from operations guidance center, while Welltower’s uses about 53% of its $6.40 guidance center, leaving both payouts comfortably covered by cash earnings.
Where they separate is leverage. Ventas has reduced net debt to 4.7 times EBITDA, which management says is its best level in more than a decade, while Welltower’s ratio is 2.99 times and S&P has turned its outlook on the REIT’s credit rating positive. That gives Welltower more balance-sheet room to keep raising its dividend if its growth plan works.
The key test now is execution. Welltower has a $15.5 billion acquisition pipeline that is only 75% occupied, making lease-up and operating performance central to whether it can sustain the pace of dividend increases. Ventas, meanwhile, is offering more current income but less upside if the market keeps rewarding lower leverage and faster growth.
For investors, the story is a classic yield-versus-growth split inside a sector benefiting from secular demand. Ventas may suit income-focused buyers looking for a higher starting payout, while Welltower looks better positioned for investors willing to accept a lower yield in exchange for stronger credit metrics and a faster dividend trajectory.
| Entity | Gains | Losses |
|---|---|---|
| Ventas | ▲Higher current yield | ▼Slower dividend growth |
| Welltower | ▲Faster dividend increases | ▼Lower current yield |
| Retiree income investors | ▲More cash today from VTR | ▼Less immediate income from WELL |
| Credit-focused investors | ▲Welltower’s lower leverage | ▼Ventas’ higher debt load |