Vietnam’s trade gap with Indonesia widened to 4.77 billion USD in the first eight months of 2026 as imports surged faster than exports, underscoring how deeply the bilateral relationship is being shaped by Vietnam’s need for fuel, industrial inputs and vehicles.
Vietnam trade deficit with Indonesia widens to $4.77B
That matters because the imbalance is not just a headline number: it points to a structural dependence on imported commodities and capital goods at a time when global energy, metals and shipping markets remain sensitive to growth and policy swings. Vietnam bought 8.87 billion USD of goods from Indonesia in the period, up 18.6% from a year earlier, while exports rose 6.88% to 4.09 billion USD, leaving total trade at more than 12.9 billion USD.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
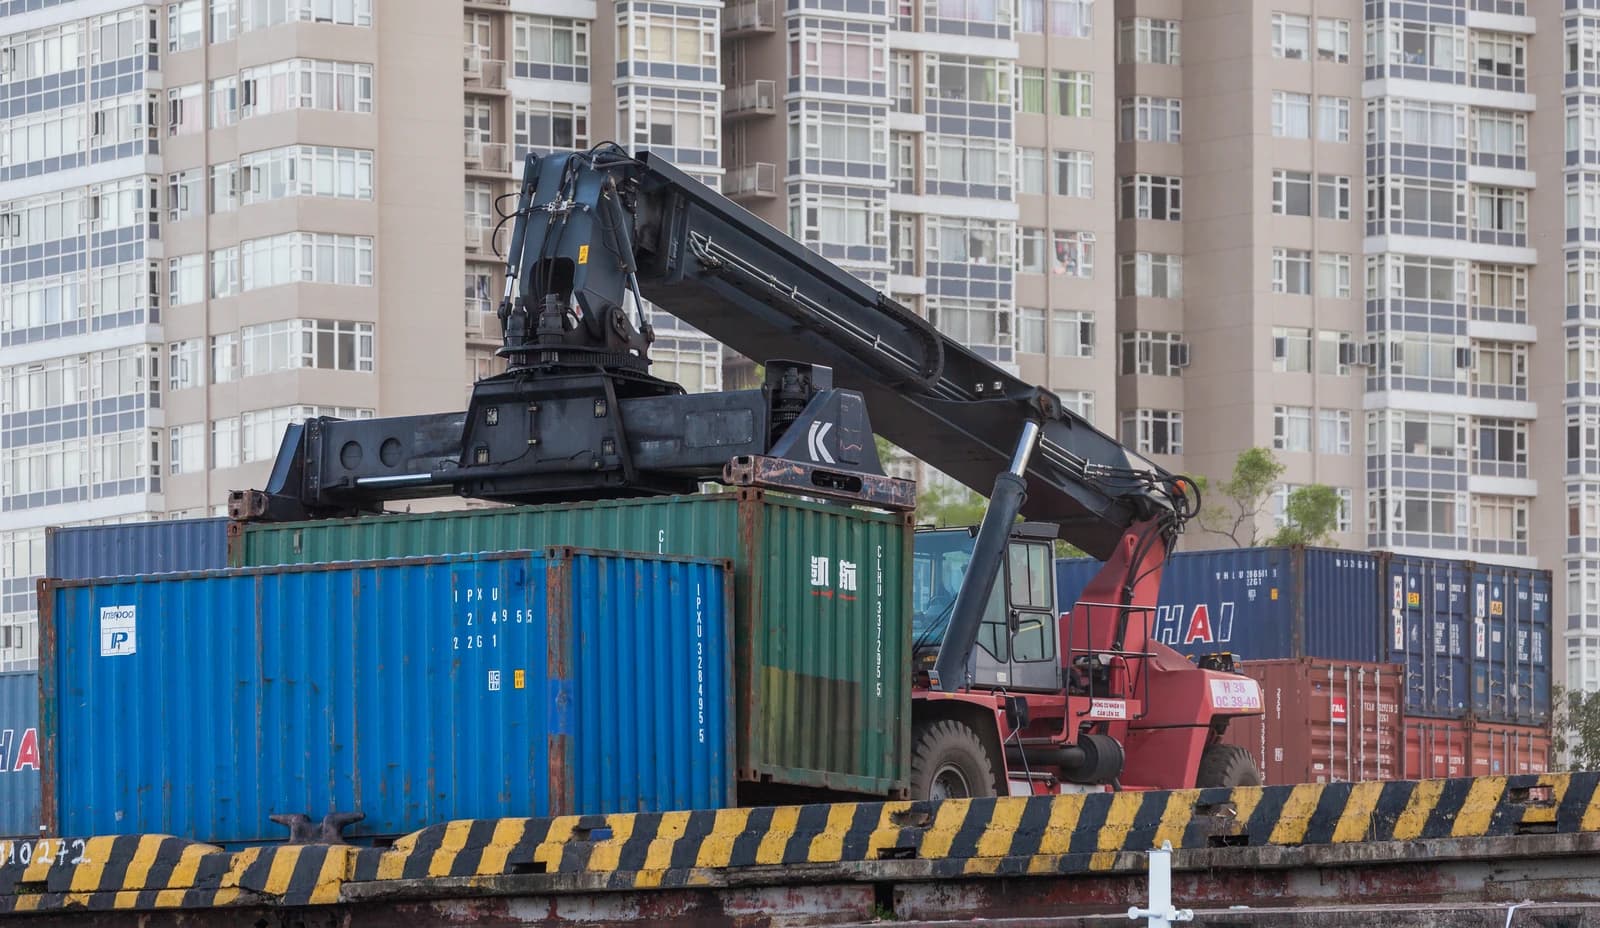
The composition of the deficit is what gives it economic weight. Coal was the largest import at 2.13 billion USD, followed by steel at 1.26 billion USD and fully assembled cars at 1.01 billion USD. Those three categories alone accounted for about 4.4 billion USD, or nearly half of Vietnam’s purchases from Indonesia. The mix suggests Vietnam is importing the building blocks of manufacturing and transportation rather than consumer goods alone, which can support industrial output but also widens the external bill when domestic supply is short.
For investors, the data reinforce two competing readings. The bull case is that stronger imports of coal, steel and vehicles reflect active industrial demand, infrastructure spending and consumer purchasing power in Vietnam, all of which can support earnings for logistics, ports, manufacturing and distribution companies. The bear case is that a rapidly widening deficit can pressure Vietnam’s trade balance, particularly if energy import costs stay elevated or if exports to Indonesia fail to keep pace.
Vietnam’s exports to Indonesia remain concentrated in textiles at 416 million USD, fabric and leather-shoe inputs at 313 million USD, and machinery and parts at 304 million USD. That profile shows the bilateral trade relationship is still asymmetric: Indonesia supplies Vietnam with harder commodities and transport goods, while Vietnam ships lower-value manufacturing and intermediate goods back. Unless Vietnam’s export basket broadens, the deficit is likely to stay vulnerable to commodity cycles.
The broader macro backdrop also matters. A weaker or volatile domestic currency can amplify the local-currency cost of these imports, while higher global rates and still-firm oil prices complicate the financing and pricing environment for importers. On the market side, the Indonesian rupiah and the Vietnamese dong may both feel the effect of trade flows, even if indirectly, through demand for foreign exchange and import pricing.
For companies, the implications are immediate. Vietnamese steelmakers, power producers, transport groups and auto distributors may benefit from stronger flow volumes, but they are also more exposed to external price shocks. Indonesian exporters of coal, steel and autos gain a larger foothold in one of Southeast Asia’s fastest-growing manufacturing markets.
The key question now is whether Vietnam can lift its exports to Indonesia enough to narrow the imbalance, or whether growth in industrial imports will continue to outstrip shipments in the other direction. For now, the trade story says Vietnam is still paying up for the inputs that keep its economy moving.
| Entity | Gains | Losses |
|---|---|---|
| Indonesian exporters | ▲Higher sales to Vietnam | ▼None from this flow |
| Vietnamese importers | ▲Access to coal, steel, cars | ▼Higher import bill |
| Vietnam trade balance | ▲Industrial supply support | ▼Wider deficit |
| Vietnam exporters to Indonesia | ▲Existing market access | ▼Slower growth than imports |