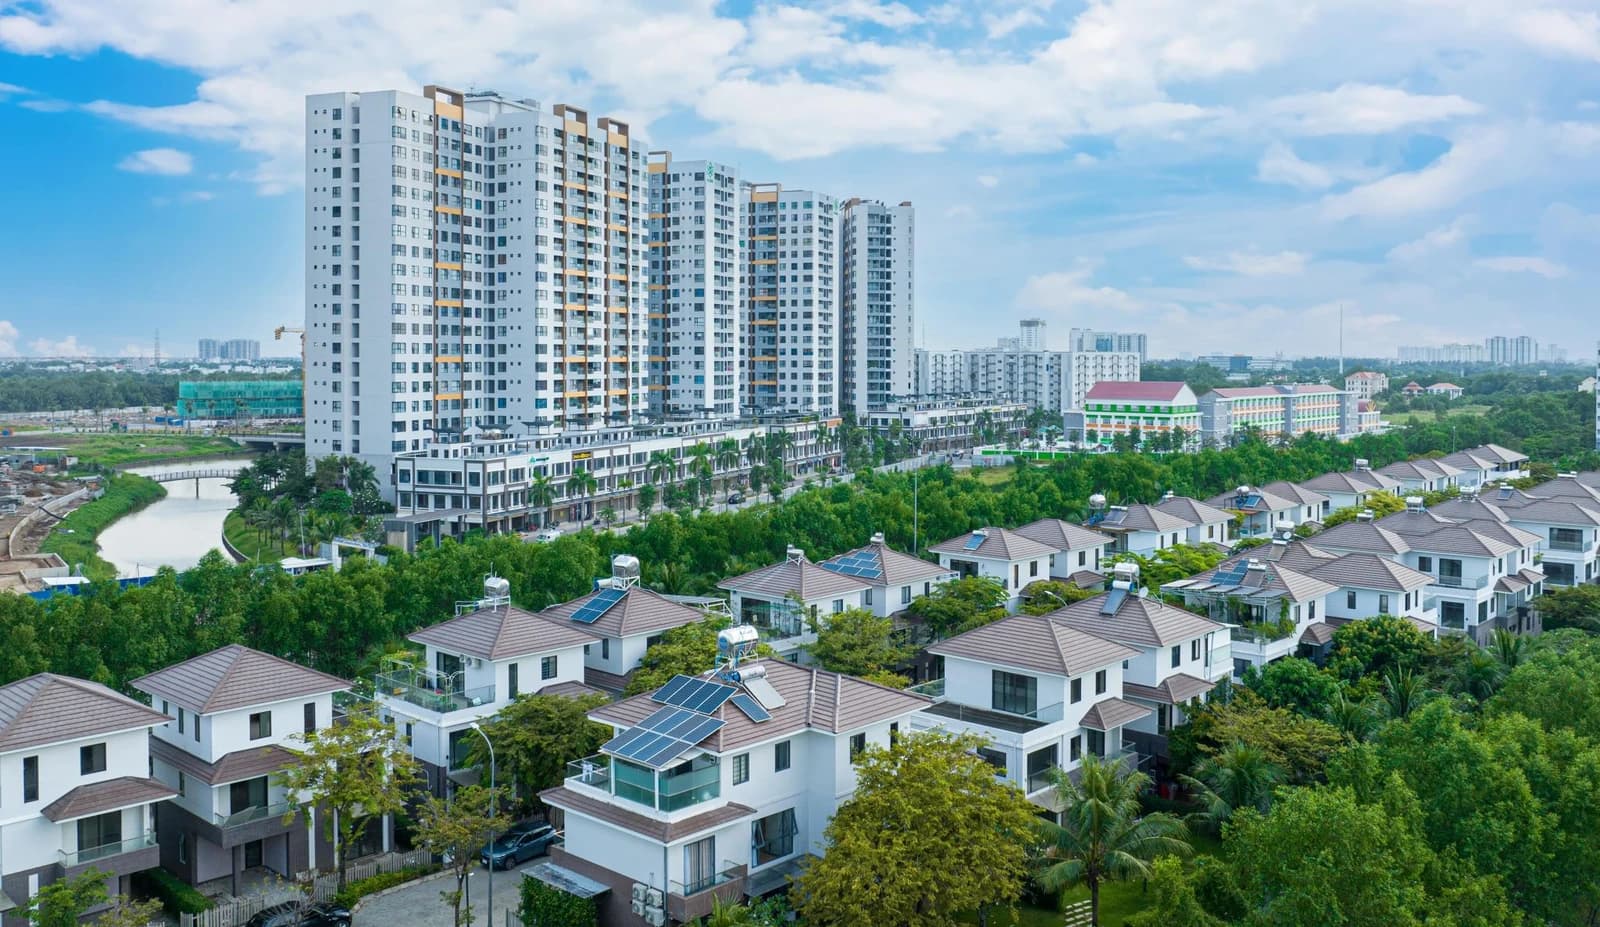
Vietnam’s property sector is still leaning heavily on borrowed money, and that makes the latest debt figure more important than a simple quarterly statistic. The Ministry of Construction says outstanding real estate business debt reached about 2.5 million billion dong in the second quarter, up nearly 13% from the previous three months, underscoring how central credit remains to the country’s housing and development cycle.
Vietnam real estate debt reaches 2.5 quadrillion dong
For investors, that matters because real estate debt is both a growth engine and a pressure point. When lending expands this quickly, it can keep projects moving, support land sales and construction activity, and help listed developers refinance near-term obligations. But it also raises the odds that a slowdown in sales, tighter underwriting or higher funding costs could leave weaker borrowers exposed, especially in a sector that has already spent years working through leverage and confidence problems.
Sentiment IndicatorsⓘProprietary · adalytica.com · August 24, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The scale of the borrowing is large enough to affect the wider economy. Property in Vietnam touches banks, building materials, contractors, household wealth and consumer spending. A 13% jump in just one quarter suggests credit conditions are still doing a lot of the heavy lifting in the sector, even as policymakers try to balance support for growth with the need to keep debt from becoming a systemic risk.
That tension is especially relevant at a time when global rates remain elevated compared with the era of ultra-cheap money. US 10-year Treasury yields are sitting around 4.7%, while the 2-year is near 4.2%, a reminder that the cost of capital is still not easy by historical standards. Even if Vietnam’s domestic financing market is different, the global backdrop argues for selectivity: businesses with strong land banks, better presales and manageable leverage should outperform those relying on perpetual refinancing.
Long term, the key question is not whether credit will keep supporting Vietnamese property, but which developers can turn borrowed money into durable cash flow. If the sector can convert this debt growth into finished projects, healthier inventories and steadier sales, it could set up a stronger multi-year recovery. If not, the debt load becomes a drag on banks, confidence and future supply.
For investors, that means this is a story worth watching, not chasing. In a market like this, balance sheet strength and liquidity matter more than headlines, and patience is usually rewarded.
| Entity | Gains | Losses |
|---|---|---|
| Developers with strong cash flow | ▲Easier refinancing | ▼Weaker peers with thin liquidity |
| Banks and lenders | ▲More loan growth | ▼More credit risk exposure |
| Construction and materials firms | ▲Ongoing project activity | ▼Delays if debt stress rises |
| Long-term investors | ▲Recovery upside | ▼Highly leveraged property names |