Wheat futures in Chicago fell to their lowest level since January on Wednesday, extending a commodities selloff as a surging dollar tightened the pressure on U.S. exports and added fresh downside to grain prices.
Wheat Futures Fall to January Low on Strong Dollar
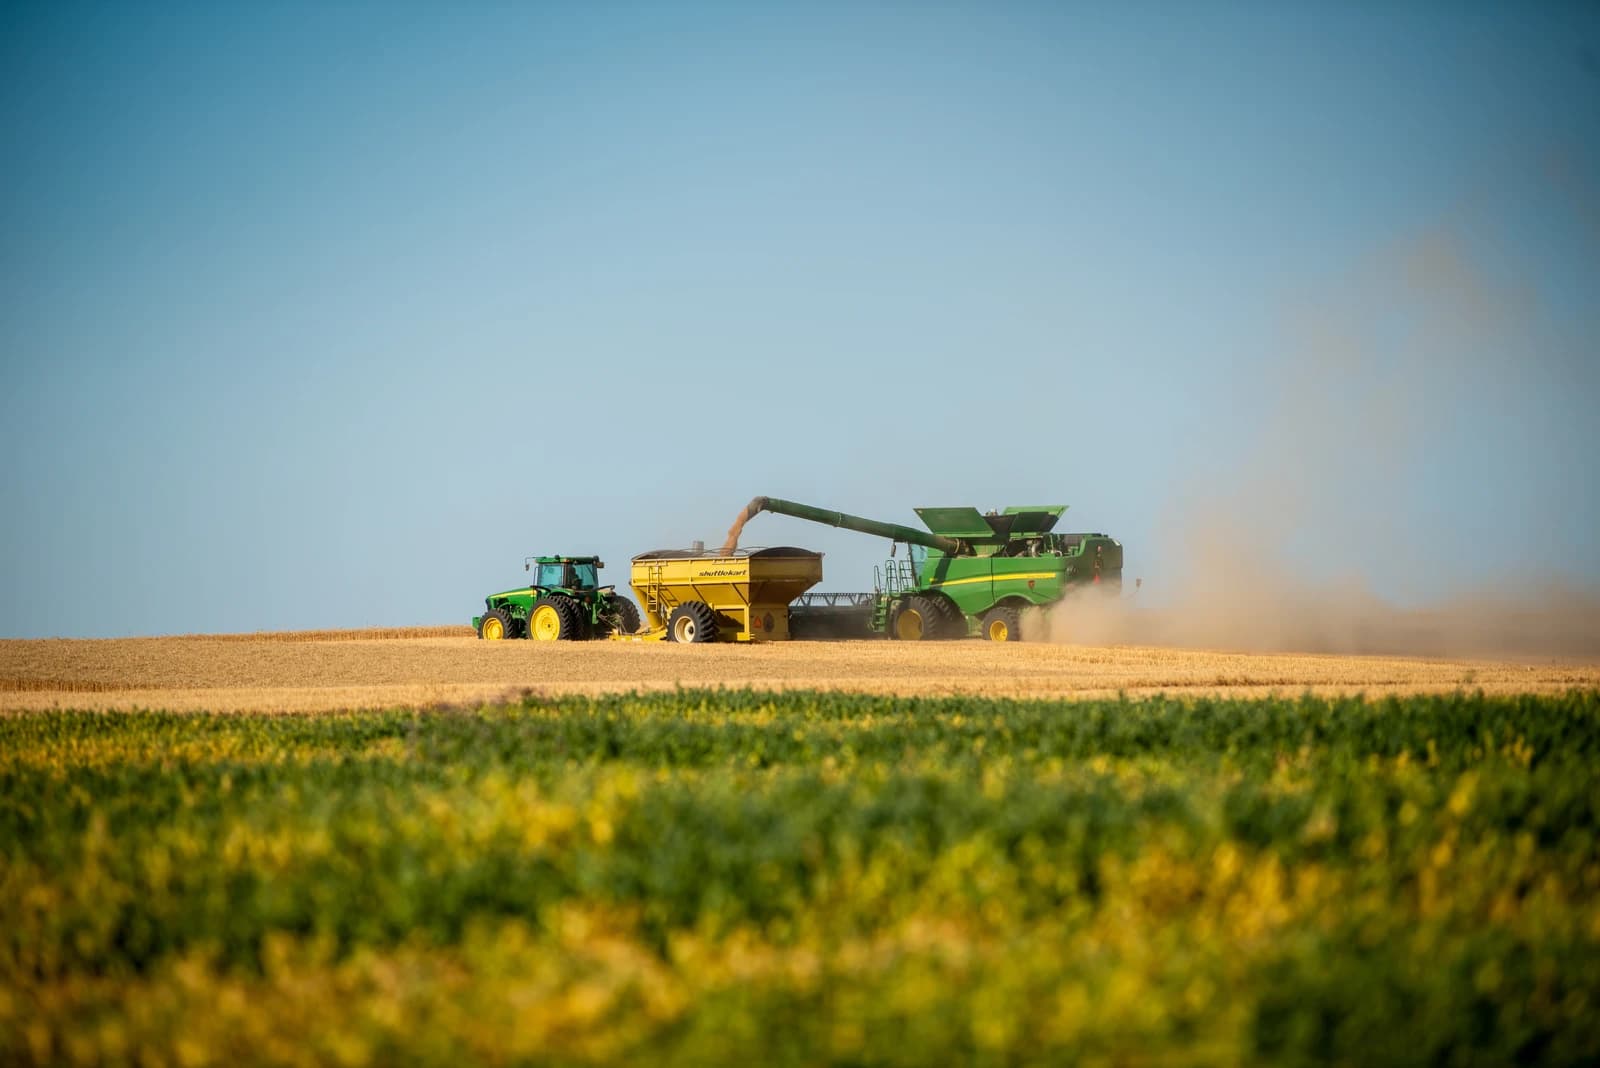
CBOT December wheat dropped 25 cents to $5.70 a bushel, with corn and soybeans also weaker. The move matters because wheat is a globally traded staple, so currency shifts, not just crop fundamentals, can quickly reshape trade flows, margins and farm income. When the dollar hits a 19-month high, U.S. grain becomes more expensive for overseas buyers just as importers have more alternatives from Europe, the Black Sea and other exporters.
Sentiment Indicators
That dynamic is especially important for investors watching the agricultural complex. The dollar strength comes at a time when wheat has already lost momentum technically: the December contract broke below its 50-day moving average and briefly traded near the lower end of its Bollinger Band range, while the relative strength index slipped to 32.9, showing the market is nearing oversold territory but has not yet found a durable bid. In plain terms, the path of least resistance remains lower unless export demand improves or the dollar eases.
The macro backdrop is doing the heavy lifting. Reuters data showed the greenback rallying on expectations of tighter U.S. policy, and that matters across commodities. A firmer dollar tends to weigh on dollar-denominated raw materials by reducing purchasing power abroad. For wheat, the hit is amplified because buyers can switch sourcing relatively easily, and global supplies are still being shaped by aggressive competition from non-U.S. origins.
For the broader food chain, weaker wheat prices can eventually ease input costs for millers, bakers and packaged-food companies, but the market is not yet pricing a clean tailwind. Adalytica’s Food and Grocery Spending sentiment gauge remains in Fear, underscoring that consumers are still under pressure and limiting the ability of sellers to pass along higher costs. At the same time, U.S. grain merchants and exporters face a tougher margin environment if foreign demand continues to migrate away from American supplies.
The investment takeaway is straightforward: the market underestimates how much currency can dominate grain pricing in the near term. Until the dollar cools, wheat is likely to remain the weakest link in the U.S. grain complex, and that keeps pressure on farmgate returns, grain merchandisers and export-sensitive ag names even if longer-term food demand remains intact.
| Entity | Gains | Losses |
|---|---|---|
| Overseas wheat buyers | ▲Cheaper U.S. and global offers | ▼None materially |
| U.S. grain exporters | ▲Limited benefit from lower prices | ▼Weaker export competitiveness |
| Millers and food manufacturers | ▲Lower input costs over time | ▼Near-term price volatility |
| Wheat farmers | ▲None materially | ▼Lower cash receipts |