Woodside Energy is rapidly advancing its $24 billion Louisiana LNG project, making the ASX-listed producer’s biggest global wager a central test of whether US gas policy and export demand can justify another wave of multibillion-dollar liquefied natural gas investment.
Woodside Energy advances $24B Louisiana LNG project
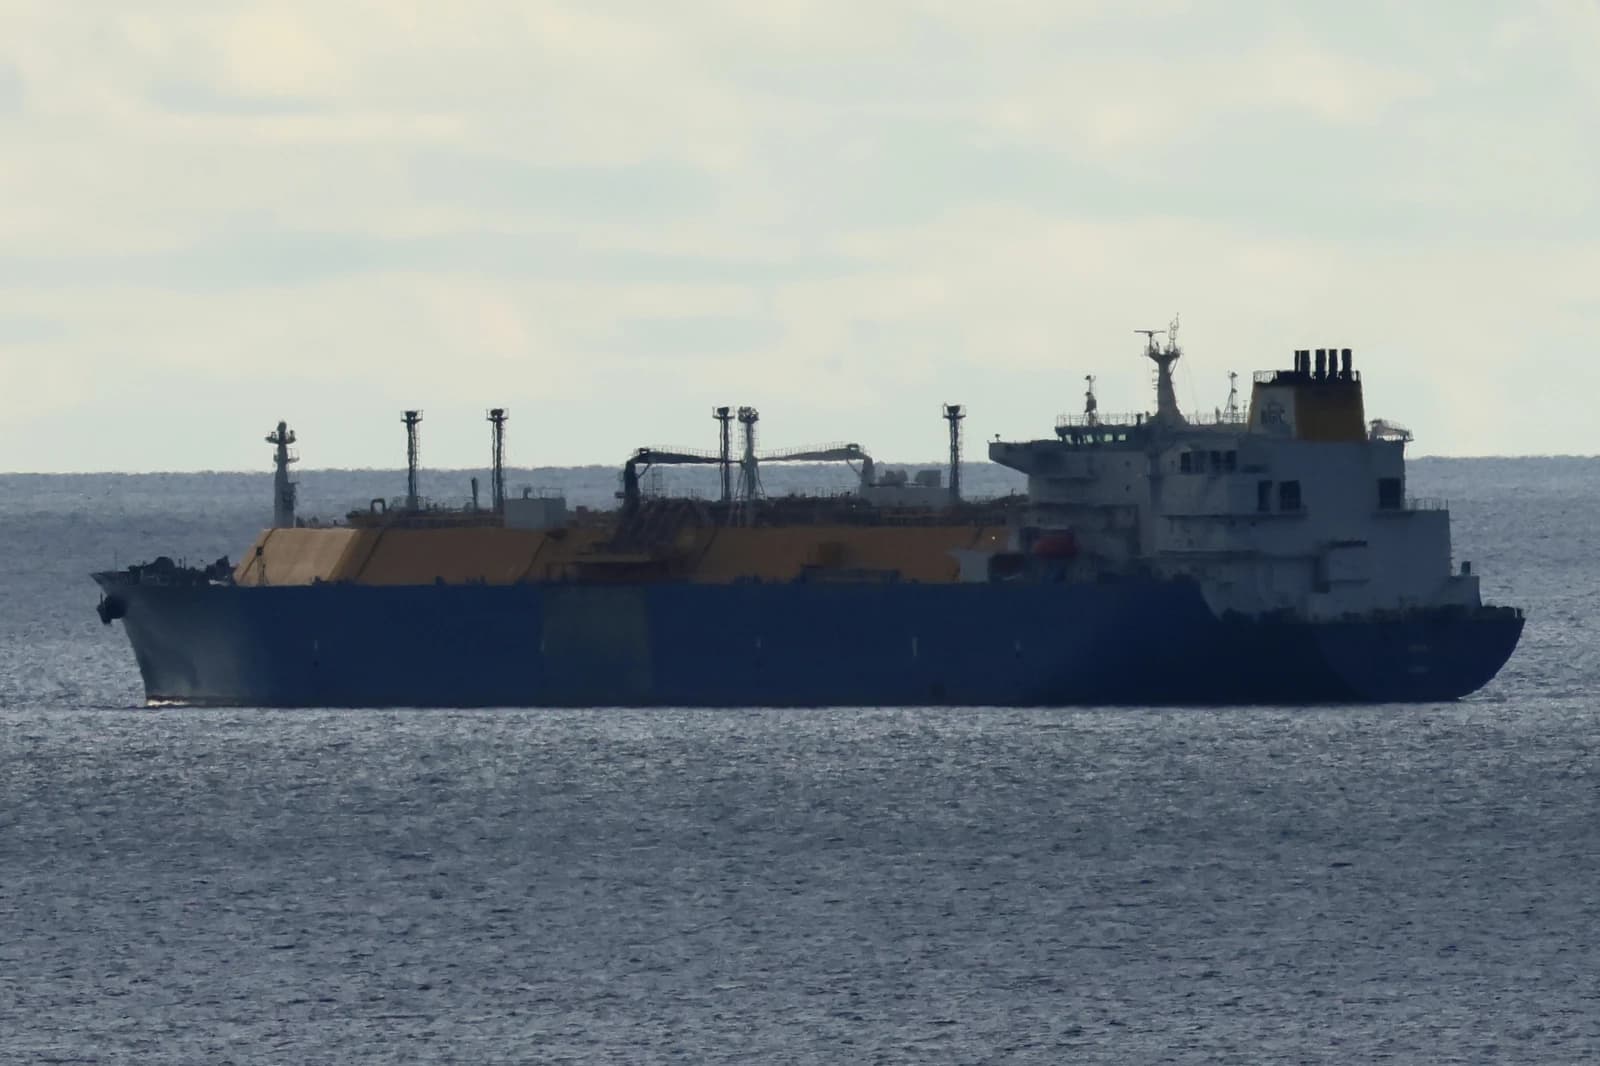
The scale of the buildout matters because it could lock in years of capital spending, reshape Woodside’s production mix and deepen its exposure to the US Gulf Coast export market just as geopolitical shocks keep LNG demand and pricing volatile. For investors, the project is the clearest driver of Woodside’s next leg of growth — and one of the biggest reasons the stock has swung sharply higher and lower as execution risk, tariffs, politics and gas prices move in tandem.
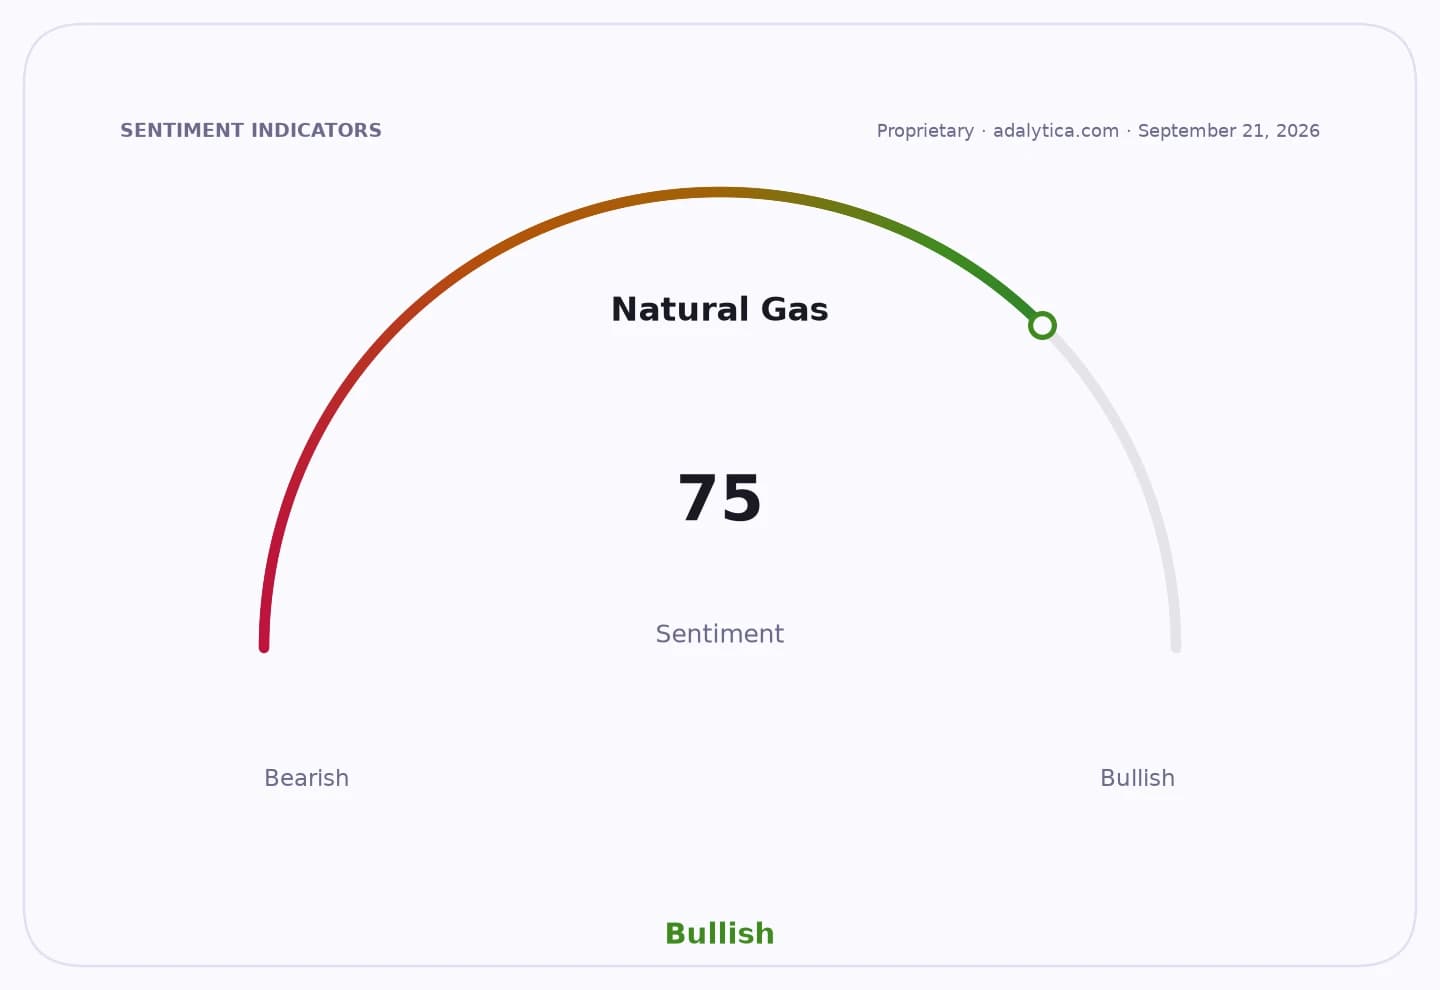
Sentiment IndicatorsⓘProprietary · adalytica.com · September 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
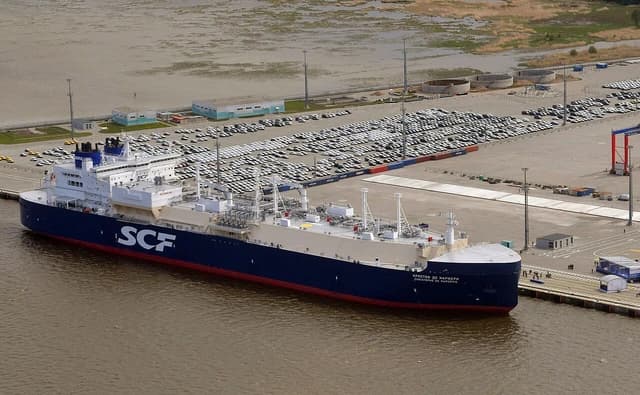
On a 445-hectare former Louisiana swamp, cranes, trucks and excavators are now moving earth around what will become one of the largest LNG projects in the US. The site includes two of North America’s biggest concrete tanks and infrastructure designed to liquefy gas for export, a visible sign that the project has shifted from paper ambition to heavy construction.
Woodside’s push comes as global LNG markets stay tight. QatarEnergy has extended supply cancellations to Pakistan, Bangladesh and Italy until at least November, while low European gas inventories and geopolitical disruption around the Strait of Hormuz are supporting competition for cargoes. That backdrop has kept Asian LNG prices near their highest since 2022 and reinforces why producers still see export capacity as strategically valuable.
The market has already priced in much of the optimism around Woodside’s US expansion. The stock last traded at A$22.77, above its 200-day moving average of A$19.84, after surging earlier this year to as high as A$24.18. By contrast, U.S. peer Cheniere Energy has rallied to about $292, underscoring how investors continue to favor LNG exporters with visible volumes and long-duration cash flow.
Still, the Louisiana project remains the main catalyst. Successful execution would give Woodside a larger foothold in the world’s most important LNG export basin and help offset more mature assets elsewhere in its portfolio. Any slippage, cost blowout or policy reversal would hit a project large enough to move company-wide earnings, balance-sheet leverage and investor confidence.
The next market focus will be on construction milestones, financing, and whether Washington’s pro-export stance under the Trump administration continues to support permitting and development momentum. Global gas volatility and winter demand will likely keep LNG names in the spotlight well into year-end.
| Entity | Gains | Losses |
|---|---|---|
| Woodside Energy | ▲US LNG growth | ▼Capex and execution risk |
| LNG buyers | ▲More supply optionality | ▼Higher spot prices |
| Cheniere Energy | ▲Sector tailwinds | ▼Competition for capital |
| Gas-importing countries | ▲Future cargo access | ▼Short-term pricing pressure |