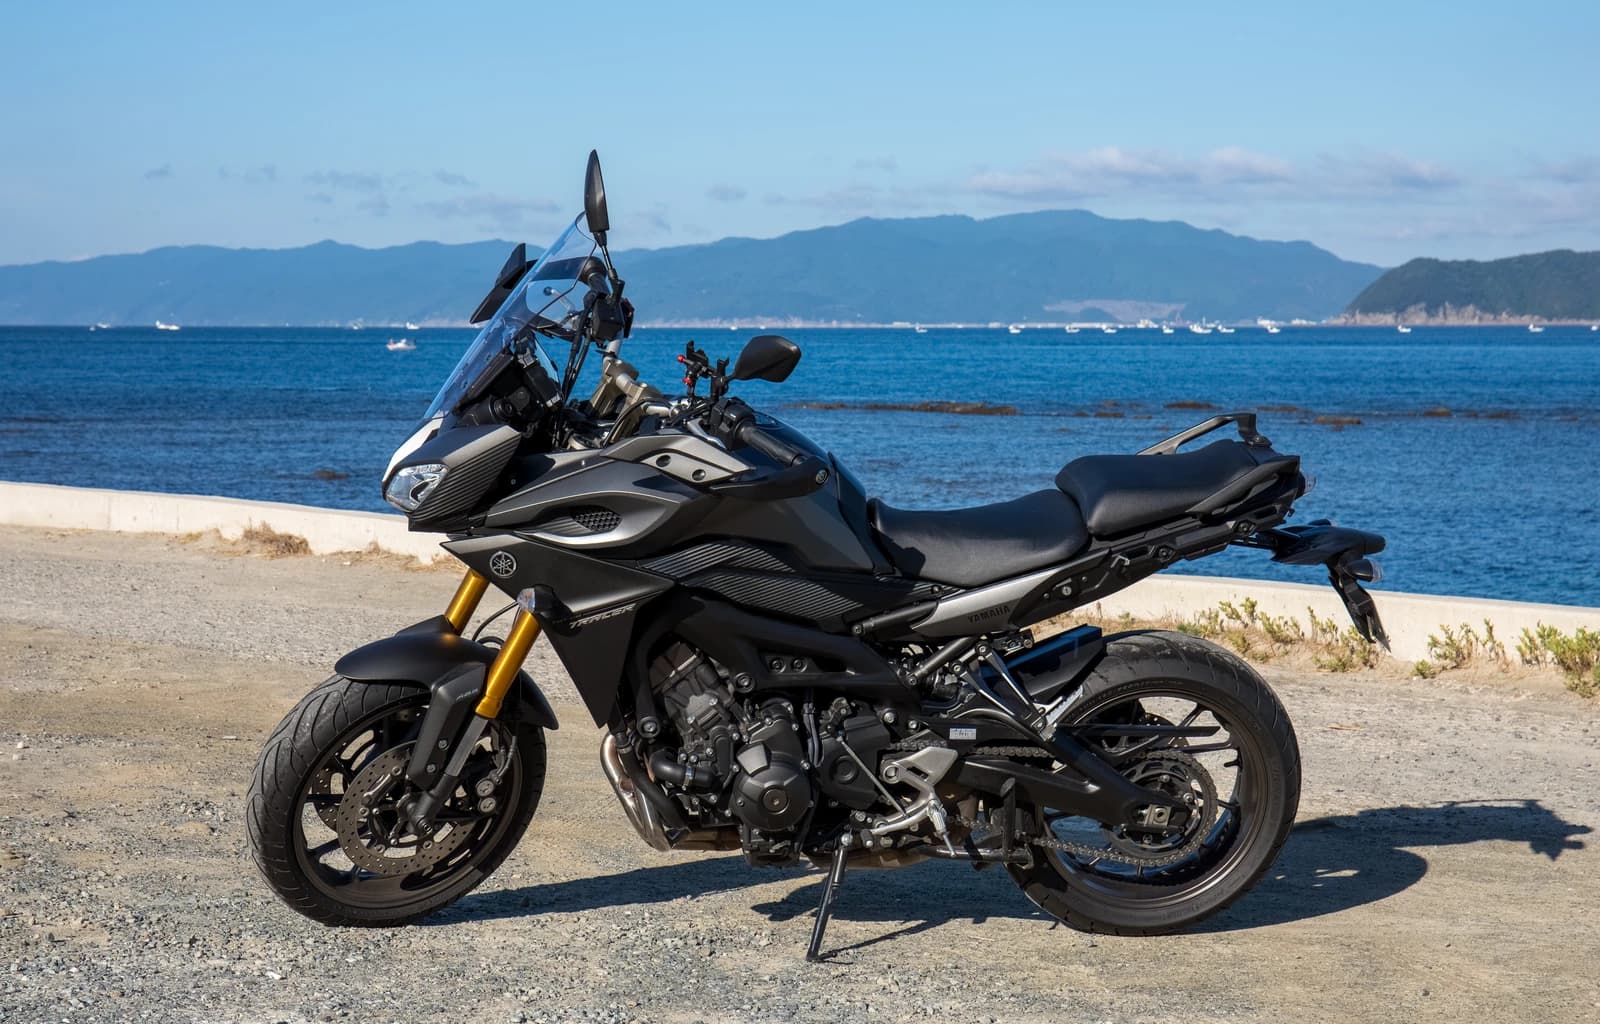
Yamaha Motor's profit surge shows how powerful currency moves can be for a Japanese exporter when product demand is still firm. In the January-to-September period, net profit nearly quadrupled, helped by stronger sales of motorcycles and outboard motors and by a weaker yen that inflated the value of overseas earnings.
Yamaha Motor Profit Rises on Weak Yen
For investors, that matters because Yamaha is not just another cyclical manufacturer riding a one-quarter pop. It is a global consumer and marine brand with real pricing power in key markets, and the latest results suggest its operating leverage is still intact. When sales volumes rise and the yen stays soft, profits can expand much faster than revenue — a reminder that exporters can generate substantial earnings upside even without a dramatic improvement in domestic demand.
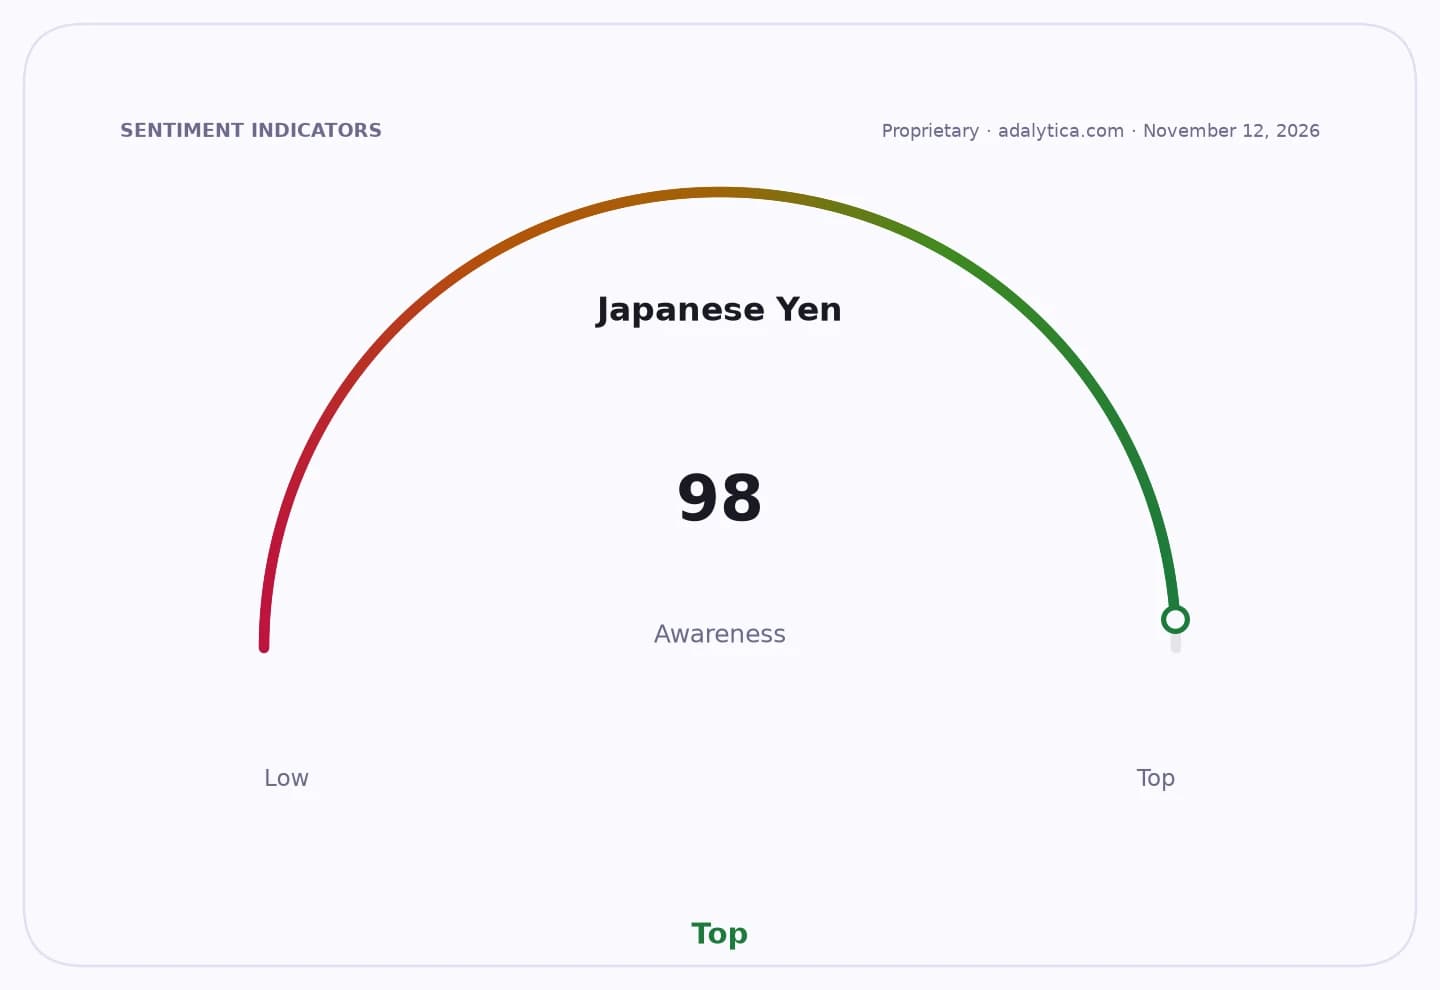
Sentiment Indicators
US Dollar
The foreign-exchange backdrop has been central. The yen has spent much of the period near the weaker end of its recent trading range, with the currency around 158.75 to the dollar in the latest data, still well above levels that would normally be considered comfortable for Japanese households but supportive for exporters. That split is exactly why the weak-yen trade remains so important: it boosts translated profits for companies selling abroad, even as it raises the cost of imported goods and fuels criticism overseas that Japan keeps its currency too cheap.
Yamaha appears to be benefiting from both sides of its business. Motorcycle demand remains the core engine, especially in emerging markets, while outboard motors provide a more specialized, higher-margin source of growth. That mix is attractive for long-term investors because it gives the company exposure to transportation and recreation spending across geographies, rather than relying on one narrow market or one product cycle.
US Dollar
Still, currency gains are never a moat on their own. If the yen strengthens, the math changes quickly. The dollar-yen pair has shown plenty of volatility, and the broader foreign-exchange market is still very much in play as central banks and investors reassess interest-rate paths. That means Yamaha’s earnings power should be judged not just on the latest headline profit but on whether the company can keep growing unit sales, defend margins and continue raising returns when the currency tailwind fades.
For long-term investors, the takeaway is straightforward: Yamaha’s latest numbers reinforce the appeal of high-quality exporters that can compound earnings through both operational execution and favorable FX. The stock may wobble with the yen, but the business remains worth watching for investors who want exposure to global consumer mobility and marine leisure with a durable international footprint.
| Entity | Gains | Losses |
|---|---|---|
| Yamaha Motor | ▲Higher profit, stronger overseas earnings | ▼Import-cost pressure if yen rebounds |
| Overseas customers | ▲Broader product supply, brand availability | ▼Higher local prices if yen weakness persists |
| Japanese exporters | ▲Translation boost from weak yen | ▼Households facing costlier imports |
| Yen bulls | ▲Potential upside if policy narrows FX weakness | ▼Near-term currency headwinds |