Zijin Mining’s long-delayed 182.6 billion yuan takeover of Chifeng Gold is now down to its last 48 days, and the biggest question for investors is no longer the price but whether the remaining approvals can clear before the Nov. 30 deadline. That matters because this is one of the largest domestic control deals in China’s gold industry in years, and every extra month of uncertainty keeps a strategically important asset in limbo while the market keeps repricing both sides of the transaction.
Zijin Mining Chifeng Gold takeover faces Nov. 30 deadline
The deal, announced in late March, would see Zijin’s wholly owned Zijin Gold buy 242 million A shares from Chifeng’s controlling shareholder at 41.36 yuan each and subscribe for 311 million new H shares at 29.82 Hong Kong dollars apiece, for a combined consideration of about 182.58 billion yuan. If completed, Zijin Gold would become Chifeng Gold’s controlling shareholder with about 25.85% of the company, while the current controlling party exits entirely.
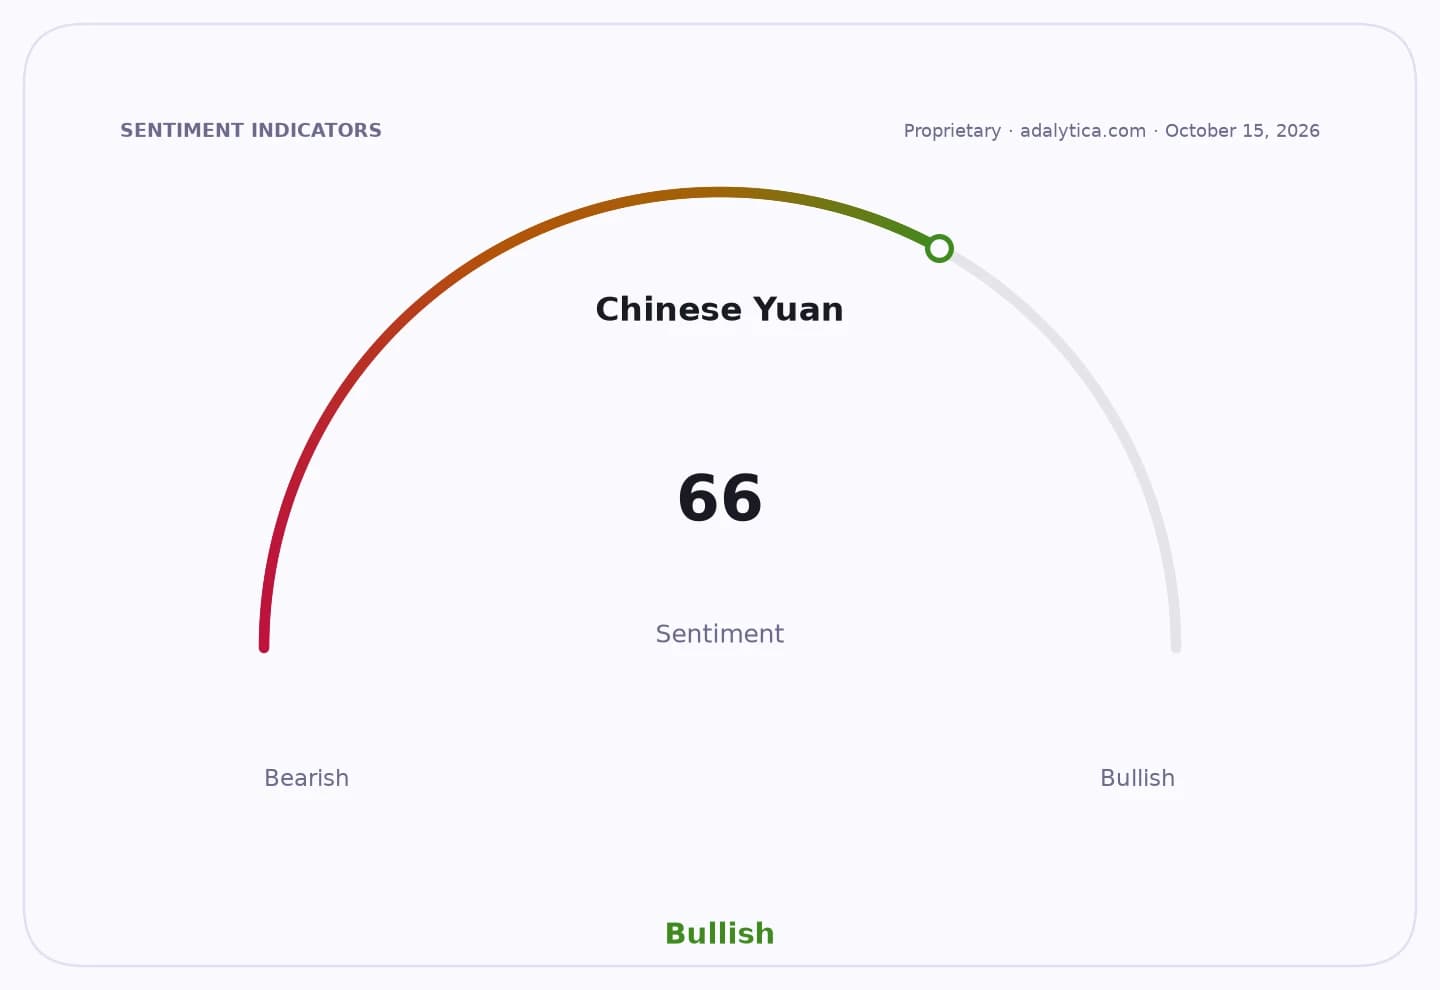
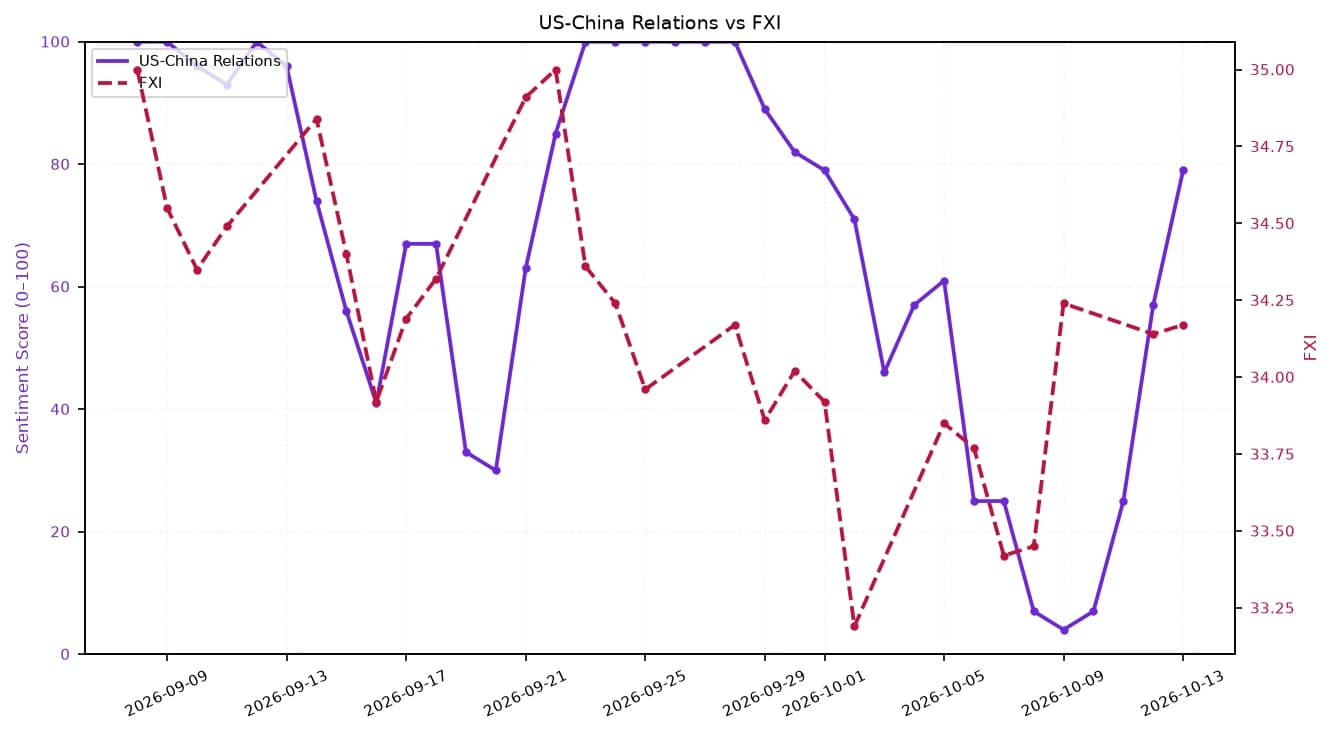
Sentiment IndicatorsⓘProprietary · adalytica.com · October 15, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That control change is economically important for a simple reason: gold producers are asset-heavy businesses whose value depends on reserves, execution and capital discipline. Bringing Chifeng under Zijin’s umbrella would deepen the scale of one of China’s best-known miners and could improve financing flexibility, mine development and operational integration across a sector that remains highly fragmented. For investors, the deal is also a test of how quickly large, cross-structured transactions involving A shares, H shares and regulatory approvals can actually close in China.
The problem is timing. The parties first signed the transaction in March and the shareholder base approved the H-share issuance in May, but by Sept. 28 they had already had to push the closing deadline out two months to Nov. 30 because, in Zijin’s words, “most” of the conditions precedent had been met, but completion still needed more time. The companies have not said which approvals remain outstanding, and both declined to comment on Oct. 13, leaving the market to fill in the blanks.
According to the transaction disclosure, the deal needs five separate gates: state-owned assets approval, compliance confirmation from the Shanghai Stock Exchange and share transfer registration, China’s market regulator approval for the concentration filing, overseas investment filings with the development and commerce authorities, and shareholder approval for the H-share issuance. The anti-monopoly review has already won unconditional approval, which leaves the remaining work concentrated around state asset consent and overseas filing formalities — the sort of paperwork that can seem routine right up until the deadline starts to bite.
The market has already shown it is willing to judge the deal in real time. Chifeng Gold’s A shares were down 5.27% on Oct. 12 to 39.20 yuan, leaving them below the 41.36 yuan transfer price again after earlier trading far beneath it. At one point in June, the shares had traded nearly 40% under the agreed price, underscoring how much doubt investors attached to completion. The H-share leg tells a different story: Chifeng’s Hong Kong shares were still trading above the subscription price, suggesting investors view the equity piece as less problematic than the control transfer itself.
For Zijin, the stock market backdrop also argues for patience rather than frenzy. Technical indicators on the shares show the stock trading below both its 50-day and 200-day moving averages, with the relative strength index in the low 40s and MACD still negative, a sign the market has not yet priced in a clean resolution. That does not change the long-term investment case, but it does show how little margin of safety the market is granting any delay.
What makes this deal worth watching is that it is bigger than a single merger filing. It is a live example of how Chinese miners are trying to build scale around gold at a time when the metal’s strategic and financial appeal remains strong. If the transaction closes on time, Zijin gets a larger platform in one of the world’s most watched commodities. If it slips again, investors may start to question whether “almost done” is good enough for a transaction of this size. For long-term investors, it remains a story to keep on the watchlist — and a reminder that in mining, approvals can matter almost as much as ounces.
| Entity | Gains | Losses |
|---|---|---|
| Zijin Mining | ▲Larger gold platform | ▼Approval delay risk |
| Chifeng Gold sellers | ▲Exit at agreed price | ▼Further uncertainty |
| Chifeng minority holders | ▲Potential control premium | ▼Prolonged overhang |
| Rival miners | ▲Relative repricing chance | ▼Scale gap widens if deal closes |