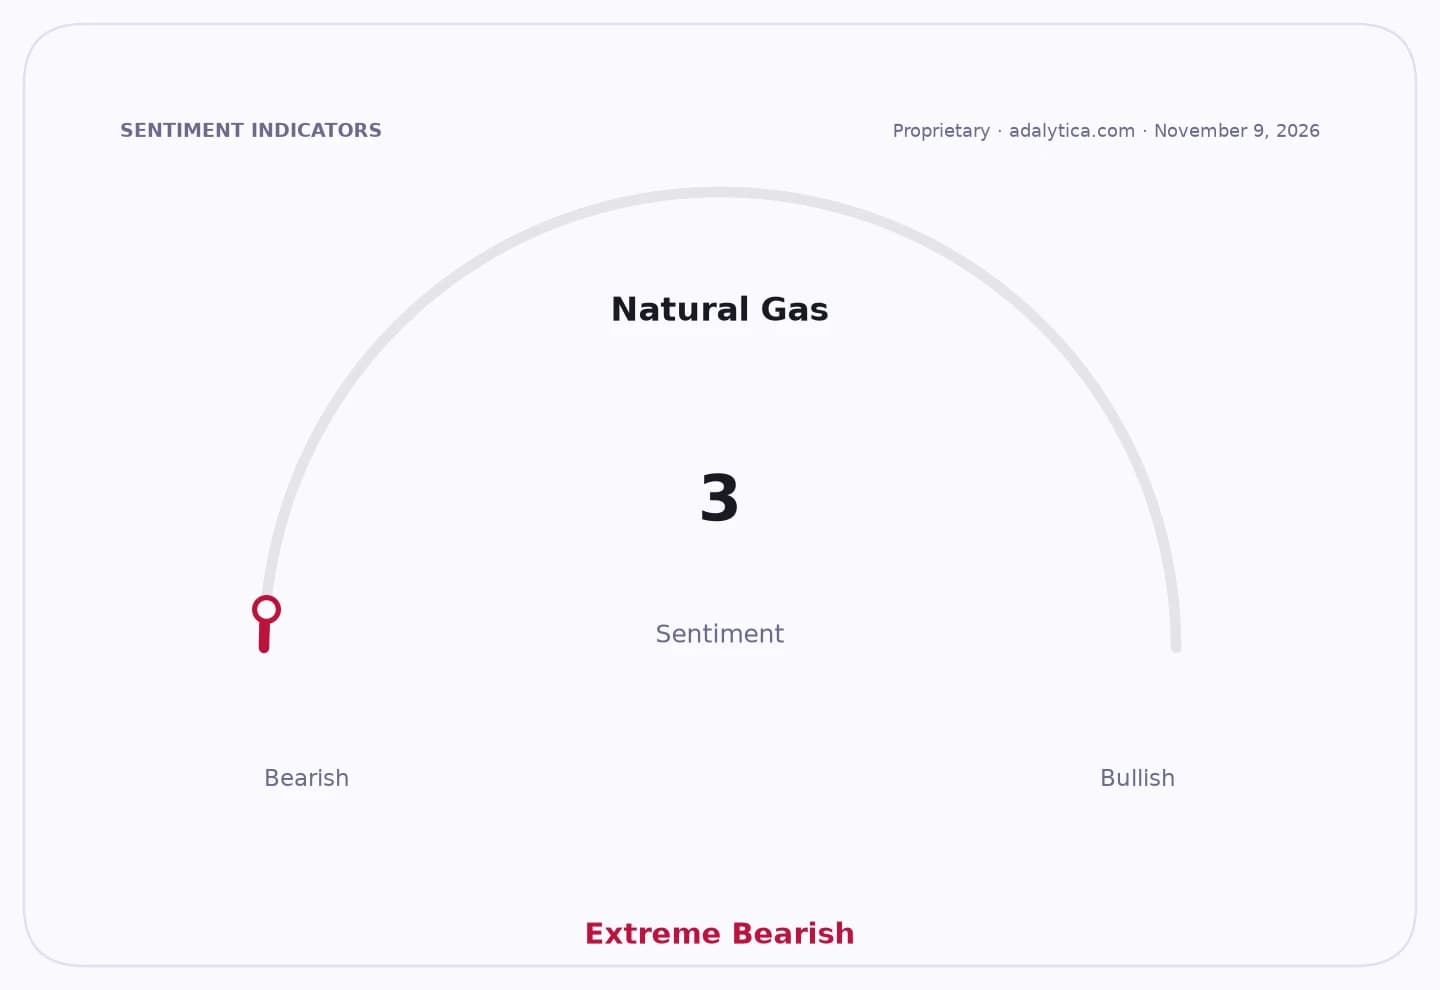
Zimbabwe’s regulator has moved to keep liquefied petroleum gas prices under pressure despite weaker crude, underscoring how import costs and logistics are now doing more damage to household fuel affordability than the oil benchmark itself.
Zimbabwe LPG prices stay high despite lower crude
The Zimbabwe Energy Regulatory Authority’s new LPG pricing regime matters because it highlights a broader shift across energy markets: when a country depends on imported fuel, the cost of moving the product can matter as much as the cost of producing it. For Zimbabwean consumers, that means the usual relief from lower crude prices may not filter through quickly, if at all. For retailers and distributors, it points to tighter margin management and a more closely watched pricing environment. For investors in the regional energy and shipping chain, it reinforces the value of supply security over simple exposure to lower oil prices.
The decision comes amid continued supply-chain disruption and higher import costs, according to the news context, which says LPG cylinder prices have not eased even as crude has declined. That divergence is important economically because LPG is a key household and commercial fuel, and persistent price pressure feeds directly into living costs and operating expenses for small businesses. In a price-sensitive market, that can curb consumption growth or shift demand toward lower-grade alternatives.
A move toward greater regulatory control also signals that authorities are trying to reduce distortions in a market that has been vulnerable to shortages and pricing unevenness. The context says domestic LPG sales have been shifted to an auction system to improve supply fairness and curb overpricing, while regulators have stepped up monitoring. That is a sign policymakers are prioritizing availability and transparency over a rapid pass-through of cheaper crude.
The supply-side risks are not just domestic. The broader market backdrop in the context points to shipping disruption in West Asia, including tensions around the Strait of Hormuz, which has already lifted imported LPG costs and complicated delivery schedules. Even where oil prices retreat, freight, insurance and routing costs can keep end-user fuel prices sticky. Indian Oil Corporation’s plan to acquire its own crude and LPG carriers also reflects that same strategic response: controlling logistics can be as important as negotiating supply.
For investors, the implication is that the LPG market is being driven less by spot crude and more by transport, access and regulatory structure. That is constructive for firms able to secure shipping and storage capacity, but negative for downstream businesses exposed to volatile import bills without the scale to hedge them efficiently. It also suggests that any relief in Zimbabwe’s consumer fuel prices is likely to be delayed until shipping routes stabilize and import costs normalize.
The near-term outlook remains volatile. Unless regional shipping risks ease and supply chains improve, Zera is likely to keep LPG pricing under close supervision, leaving consumers with little immediate benefit from softer crude and keeping the market tilted toward caution rather than relief.
| Entity | Gains | Losses |
|---|---|---|
| Zera / regulators | ▲More pricing control | ▼Less market flexibility |
| Importers / distributors | ▲Clearer rules | ▼Higher cost pressure |
| Consumers | ▲Better supply oversight | ▼No immediate price relief |
| Shipping-secure energy firms | ▲Strategic advantage | ▼Competitors exposed to disruption |