Africa’s banks are making money, but the continent’s private sector is still starved of credit — and that gap is becoming one of the biggest constraints on growth.
African Banks Face Credit Gap Despite High Profits
That is the core message from the Africa Financial Summit, or AFIS, in Luanda, where policymakers and lenders are trying to figure out how to channel an estimated $4 trillion of local financial resources into the real economy rather than leave them trapped in low-risk, low-impact assets.
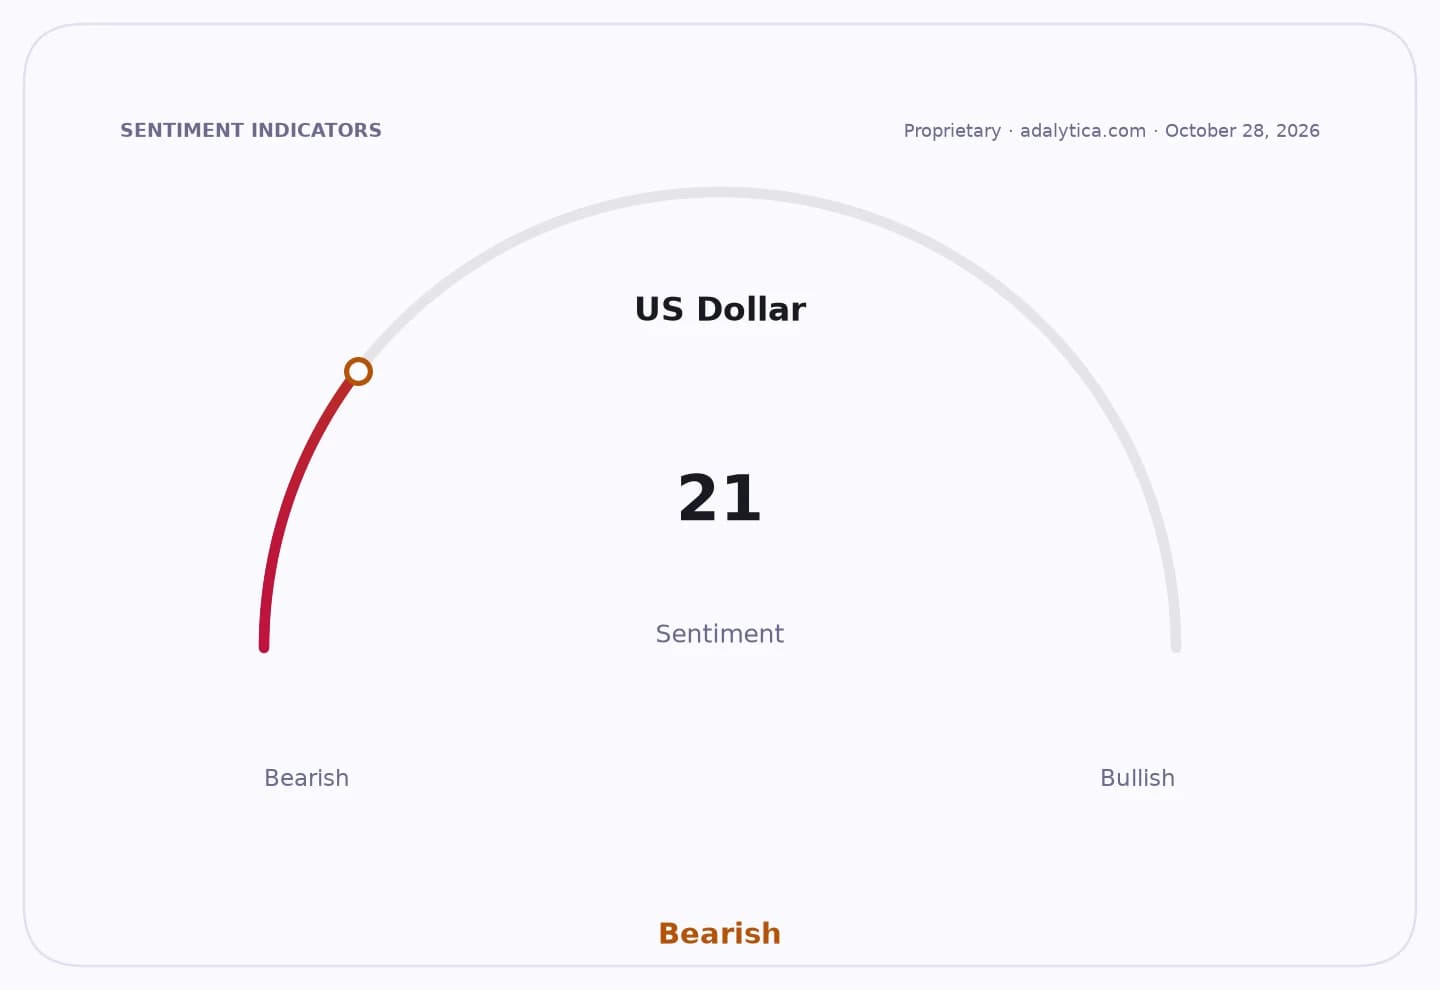
Sentiment Indicators
The economic significance is hard to overstate. McKinsey says African banks generated a return on equity of 19% in 2024, roughly double the global average of about 10%, yet corporate lending across much of the continent remains too shallow to finance the scale of investment needed in manufacturing, infrastructure, energy and technology. A profitable banking system that does not extend enough credit is a missed growth engine: it leaves small and mid-sized companies underfunded, suppresses job creation and forces economies to depend more heavily on external capital at a time when global financing remains expensive and selective.
For investors, that imbalance creates both risk and opportunity. The risk is obvious: banks can report strong profits while the broader economy fails to accelerate, limiting loan growth over time and keeping asset quality exposed to weak business activity. The opportunity is in the institutions, platforms and policy shifts that can convert profitability into lending volume. If African financial systems can improve credit intermediation, the winners should include banks with strong deposit franchises, lenders positioned in consumer and SME finance, and infrastructure financiers able to absorb longer-duration capital.
The summit comes as African banking confidence remains elevated. The sixth Deloitte-AFIS barometer gave institutions a confidence score of 8 out of 10, matching the prior year, underscoring that balance sheets are not the immediate problem. The real bottleneck is transmission: how to move domestic savings, pension assets and bank liquidity into productive lending without destabilizing the system.
That is why the policy debate matters so much. Across the continent, regulators are increasingly trying to balance credit expansion with financial stability, including tighter oversight of real-estate lending and more targeted support for priority borrowers. Elsewhere in Asia, state-run banks have been offering preferential lending at rates 1.5 to 2 percentage points lower, a reminder that cheaper credit can be manufactured when governments decide growth is the priority. AFIS is effectively asking whether Africa can build a similar playbook — one that lowers funding costs, broadens access to loans and still preserves bank profitability.
The investable takeaway is that the market may be underestimating the scale of the second-order winners from a successful lending expansion. Banks are the obvious beneficiaries, but so are payment networks, consumer finance lenders, infrastructure funds and insurers that can ride a deeper domestic capital market. The bigger prize is not just higher loan books; it is a more durable growth model for Africa itself. If AFIS can help unlock even a fraction of that $4 trillion pool, the re-rating could be structural, not cyclical.
The comparison table below frames the divide clearly:
| Entity | Gains | Losses |
|---|---|---|
| African banks | ▲Higher lending volumes | ▼Idle liquidity drag |
| Private-sector firms | ▲Cheaper credit access | ▼Funding shortages |
| Governments/regulators | ▲Stronger growth transmission | ▼Stability trade-offs |
| Foreign lenders | ▲Less reliance on external capital | ▼Less financing dependence |