Alcoa’s jump in third-quarter profit shows the aluminum producer is finally getting more leverage from higher output, even as prices and revenue remain under pressure.
Alcoa Q3 Profit Rises on Higher Output
The company said net income rose to $483 million in the third quarter of 2026 from $407 million in the prior quarter and $232 million a year earlier, helped by a 13% increase in aluminum production and better refinery performance. That matters because for commodity producers, volume gains can cushion softer pricing and keep cash flowing when markets are choppy.
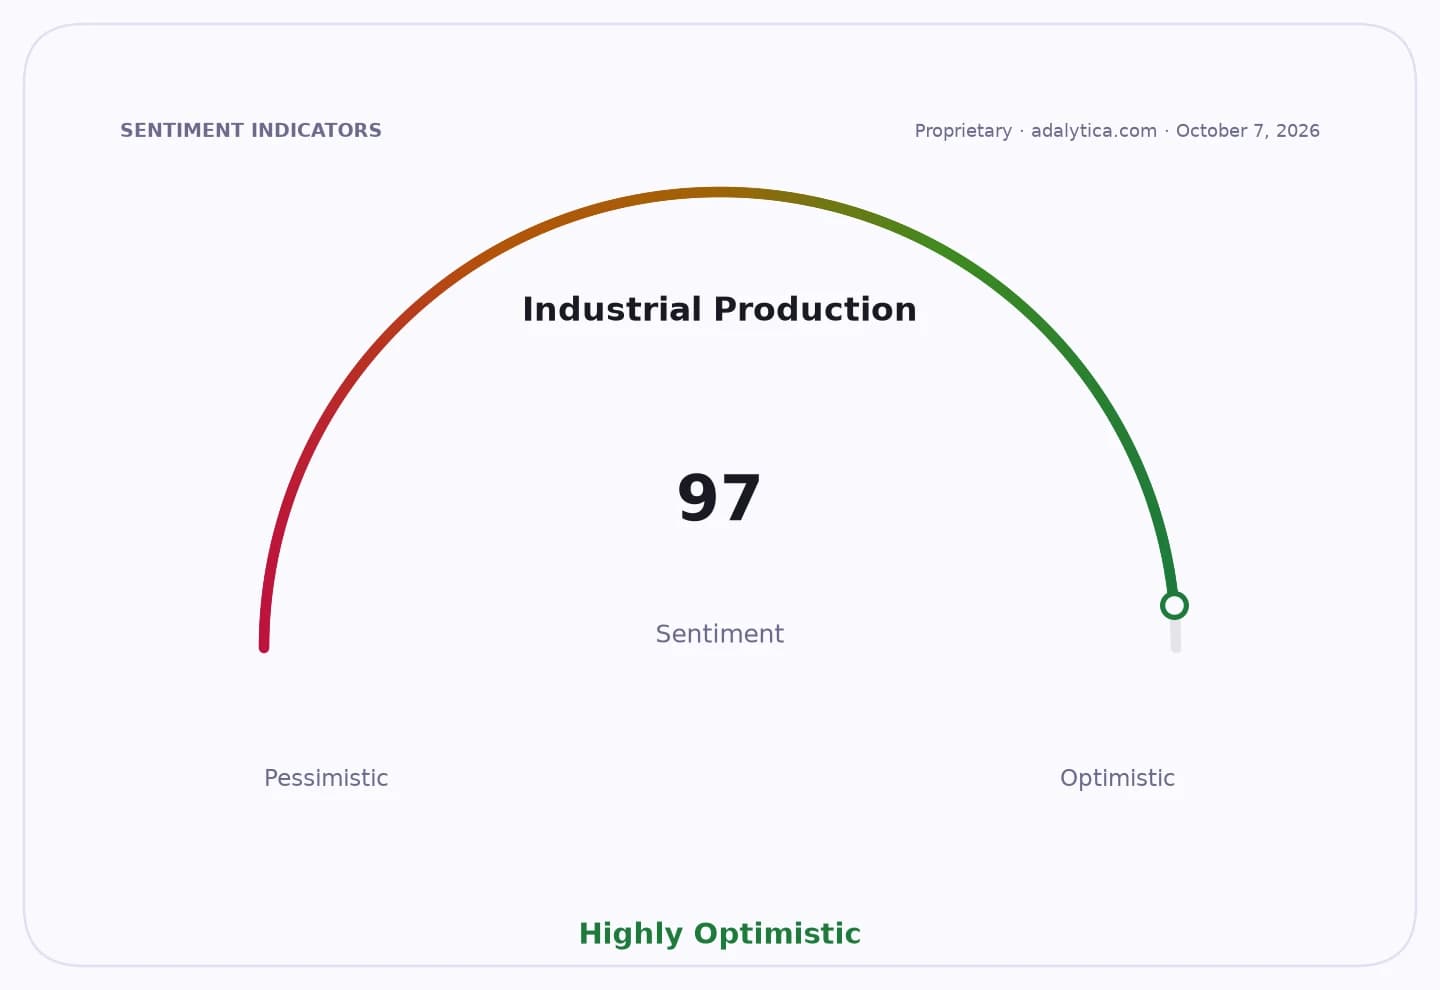
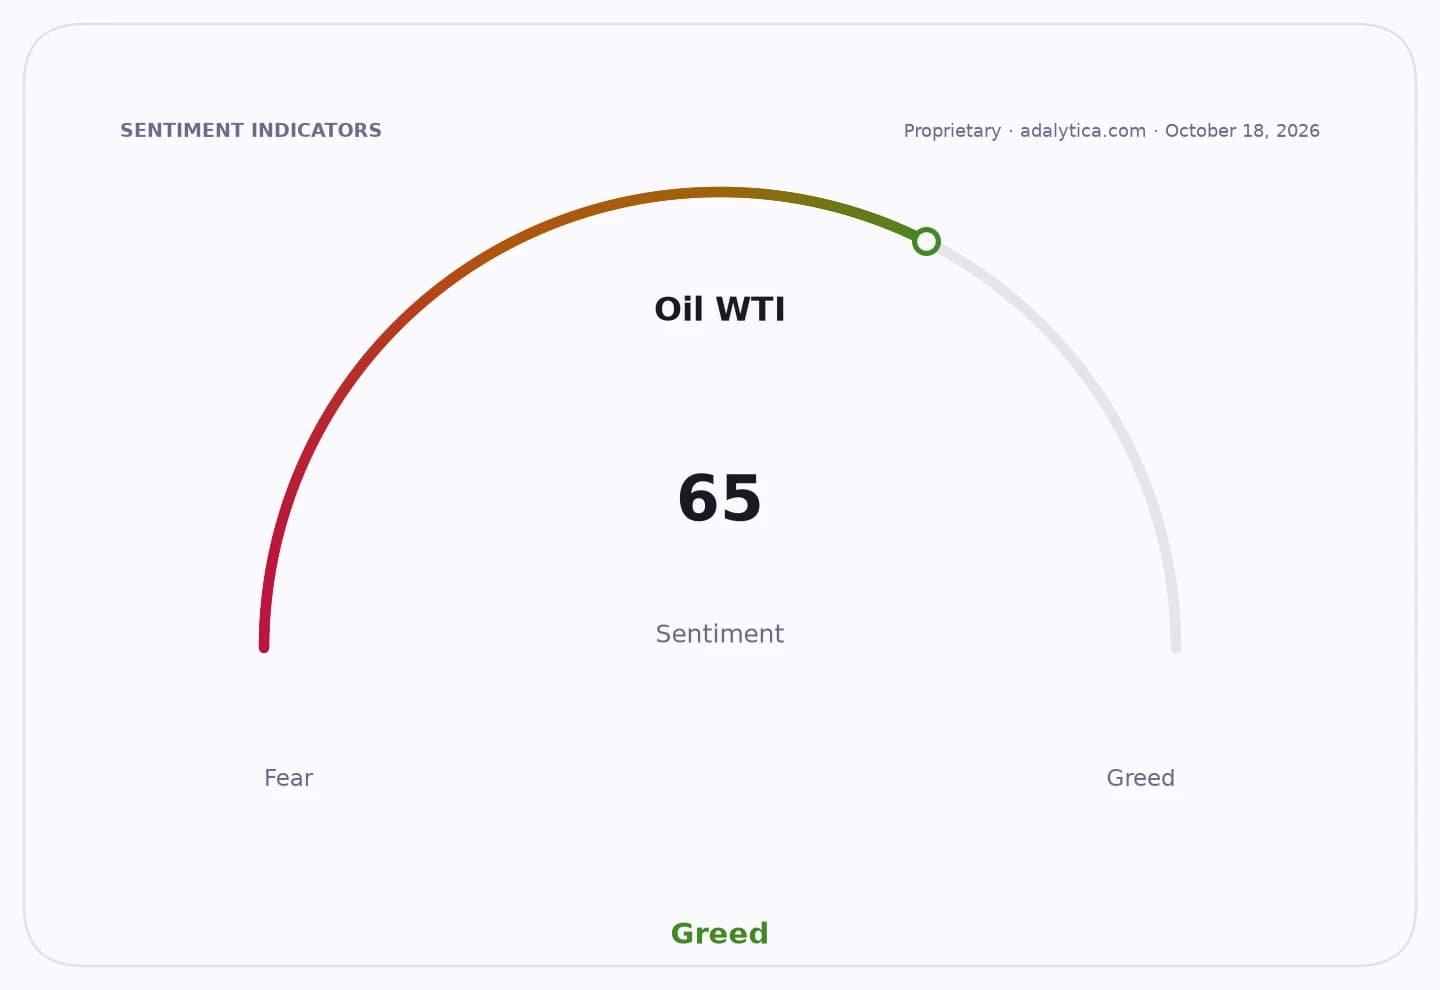
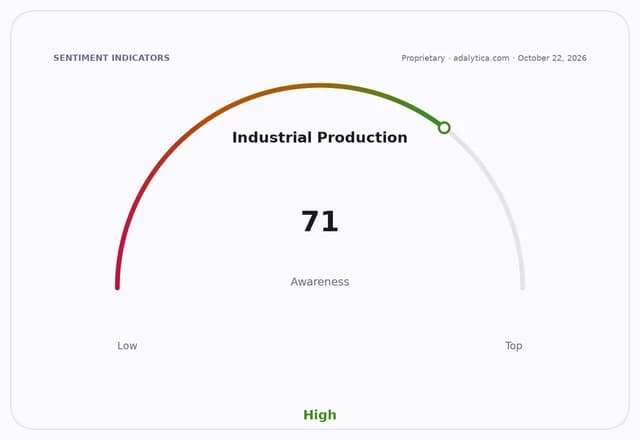
Sentiment IndicatorsⓘProprietary · adalytica.com · October 22, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Revenue came in at $3.7 billion, down 6.6% from the second quarter but still well above the roughly $3 billion it posted a year ago. Adjusted EBITDA was $789 million, down from $901 million in the prior quarter but sharply ahead of $270 million in the third quarter of 2025. Alcoa also generated $643 million in cash from operations and $472 million in free cash flow, giving it more room to invest, pay down debt and support strategic deals.
For investors, the bigger story is balance-sheet strength and execution. Alcoa ended the quarter with $4.4 billion in cash, including $2.6 billion in financing tied to its planned acquisition of South32’s bauxite, alumina and aluminum assets, known as AliGroup. That acquisition could deepen Alcoa’s control over key parts of the aluminum supply chain, a long-term advantage if demand improves and input costs stay manageable.
The numbers also sit against a cautious backdrop for the wider aluminum market. U.S. tariffs, soft industrial demand and volatile pricing have weighed on the sector, while inventories in China have been moving lower and alumina stocks have risen, underscoring a market still searching for a cleaner recovery. Industrial production sentiment remains in “extreme fear,” even as awareness around the sector stays elevated, suggesting investors are watching for a turn but not yet pricing in a broad rebound.
For long-term investors, Alcoa’s quarter is less about a single earnings beat than about whether management can turn higher output into durable free cash flow through the cycle. If aluminum prices stabilize and the AliGroup transaction closes on favorable terms, the company could be positioned for a stronger earnings run over the next few years. For now, it remains a cyclical name worth watching, not chasing.
| Entity | Gains | Losses |
|---|---|---|
| Alcoa | ▲Higher profit and cash flow | ▼Revenue softness from weaker pricing |
| South32 asset sellers | ▲$2.6 billion financing support | ▼Loss of bauxite/alumina/aluminum interests |
| Aluminum buyers | ▲More supply and potentially steadier availability | ▼Less upside from tight supply |
| Alcoa shareholders | ▲Stronger balance sheet, strategic expansion | ▼Cyclical earnings volatility |