Alphabet’s shares held near record territory on Thursday, with investors still weighing whether the company’s heavy AI investment can keep translating into faster cloud growth and advertising resilience.
Alphabet Shares Hold Near Record as AI Spending Continues
The stock closed at $349.28, little changed on the day, but the bigger picture is that Alphabet remains well above its 50-day moving average of $344.83 and its 200-day moving average of $340.42, suggesting the market is still giving the company the benefit of the doubt even after recent volatility.
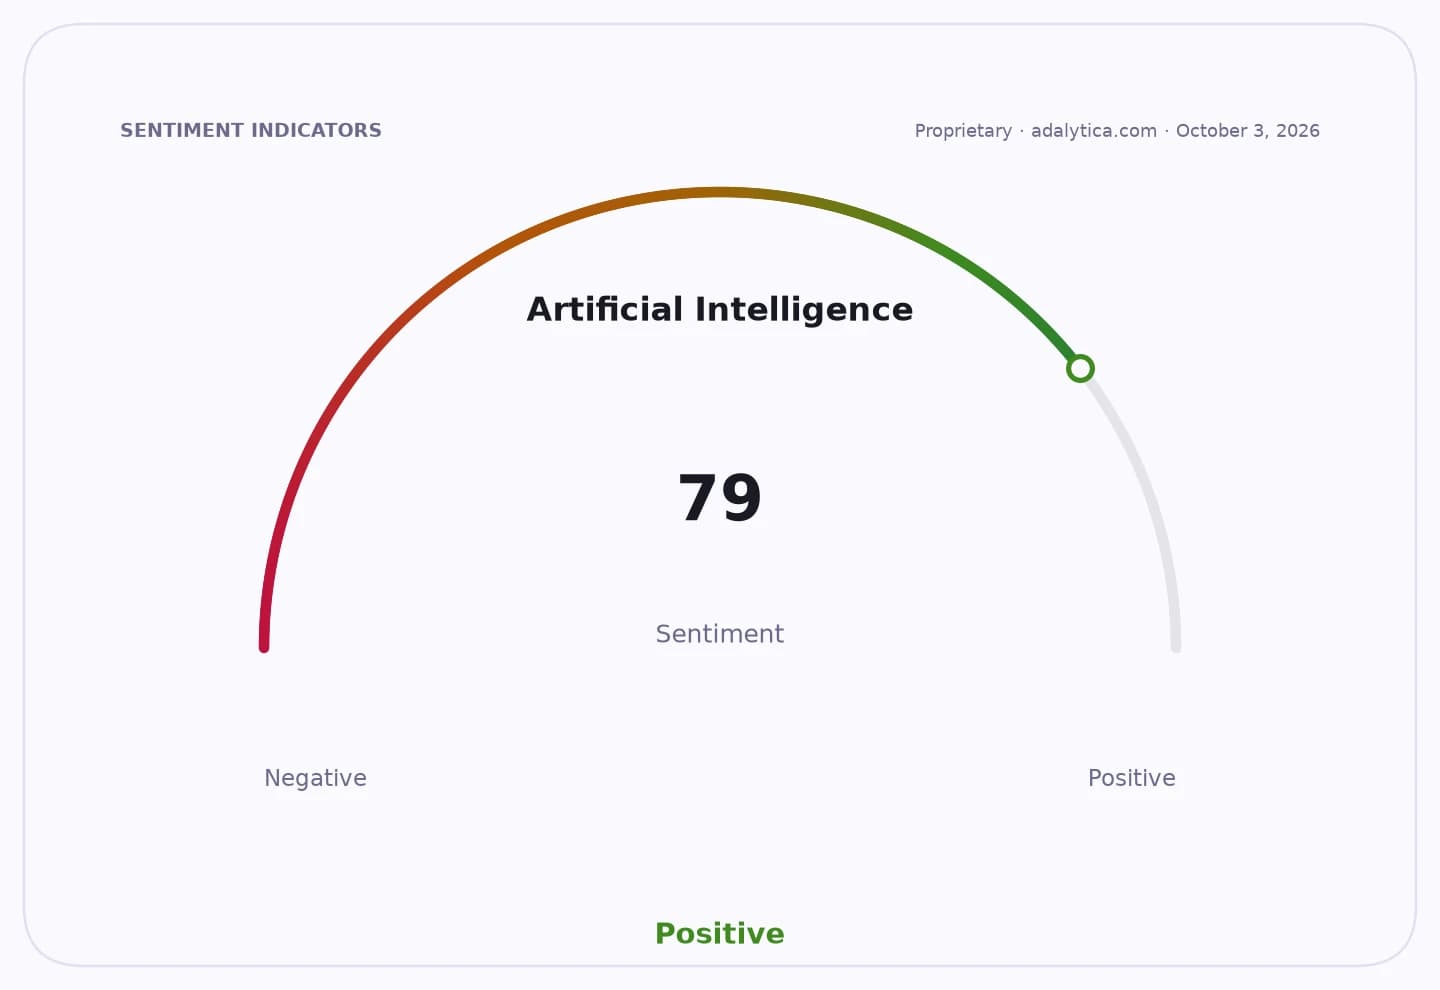
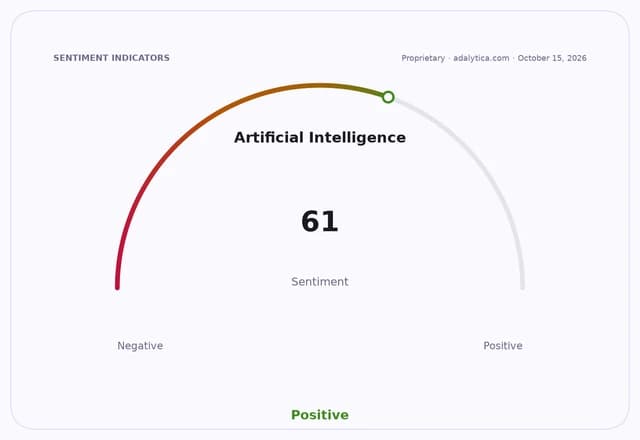
Sentiment IndicatorsⓘProprietary · adalytica.com · October 15, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That matters because Alphabet is one of the clearest read-throughs for the current market debate over artificial intelligence: whether the largest platforms can fund the buildout, monetize it quickly enough and avoid margin pressure if spending outruns demand. The company’s latest filing said Google Cloud revenue can swing with customer usage, demand and supply availability, while also noting limited agreements to supply TPU systems to customers — a sign that AI infrastructure is becoming a more direct revenue driver, not just a cost center.
For investors, the key issue is not just whether Alphabet can defend its search franchise, but whether cloud and AI can justify the capital intensity that comes with them. That question has become more important across the mega-cap technology complex as Microsoft and Meta also describe demand for cloud and AI products as difficult to forecast, reinforcing that the sector’s growth story is still being tested by execution risk.
Technically, Alphabet’s stock is still constructive. The 50-day average remains above the 200-day average, and the shares are holding in the middle of a recent trading range after touching as high as $353.78 this week. The relative strength index at 56.7 points to neither overbought nor oversold conditions, while the MACD remains positive, suggesting momentum has not broken down even if it has cooled from earlier highs.
The bullish case is that Alphabet’s scale in search, YouTube and cloud gives it more room than peers to absorb AI spending while still producing cash flow. The bearish case is that the market is already pricing in a smooth monetization path that could be delayed if AI infrastructure costs stay elevated or if cloud demand proves uneven. For now, investors appear willing to own the stock through that uncertainty — but the next leg higher will likely require proof that AI is lifting revenue faster than it is lifting expense.
| Entity | Gains | Losses |
|---|---|---|
| Alphabet | ▲AI and cloud monetization | ▼Cost discipline if spending outruns revenue |
| Long-term investors | ▲Exposure to AI platform growth | ▼Near-term multiple expansion if execution slips |
| Microsoft / Meta | ▲Validation of AI capex demand | ▼Pressure to sustain heavy infrastructure spending |
| Short-term traders | ▲Range-bound technical setup | ▼Breakout conviction from current levels |