Europe is emerging as one of the clearest beneficiaries of the artificial intelligence trade, with SAP, ASML and Salesforce-related demand showing investors that the AI buildout is not limited to U.S. megacaps. The shift matters because the region is capturing spending on software, chips and enterprise systems even as U.S. investors fret over the cost of the AI race and the concentration of returns.
Europe AI winners: SAP, ASML and Salesforce
SAP, Europe’s most valuable software company, has climbed back to $214.72 from a spring low near $148 after a sharp rebound in enterprise software demand tied to AI adoption and cloud migration. The stock is now trading above both its 50-day and 200-day moving averages, a sign that buyers have regained control after a volatile first half. Its recovery has come as investors increasingly favor profitable AI enablers over speculative names.
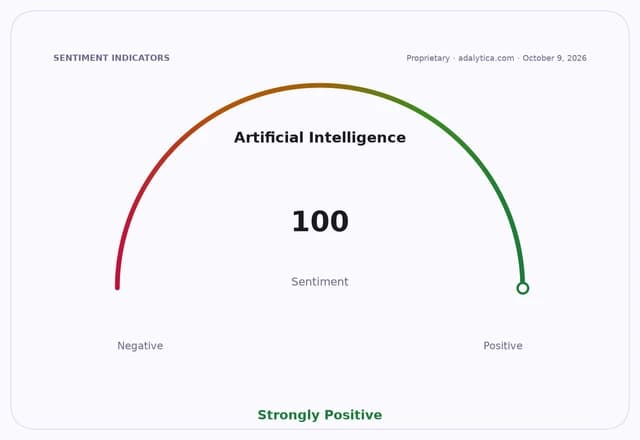
Sentiment IndicatorsⓘProprietary · adalytica.com · October 9, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
ASML remains the industrial linchpin of the boom. The Dutch supplier, whose machines are essential for advanced chip production, closed at 1,791.49 on Oct. 9, holding well above its 200-day moving average and reinforcing its role as a critical beneficiary of long-cycle semiconductor investment. As AI workloads drive demand for cutting-edge chips, ASML sits at the center of the supply chain regardless of whether the final customer is in the U.S., Europe or Asia.
The backdrop also helps Europe. The 10-year Treasury yield is forecast around 5.297%, keeping U.S. financing conditions relatively tight and raising the hurdle rate for the heaviest AI spenders. That environment tends to favor established, cash-generating companies with real pricing power, a profile that fits many of Europe’s software and equipment leaders better than the high-burn AI names Wall Street has piled into.
Salesforce’s shares, meanwhile, have bounced to $228.85 from the summer lows, underscoring that enterprise software remains in the AI basket even after a sharp reset in sentiment. Adalytica’s AI sentiment gauge is flashing “Extreme Greed” at 100, while Microsoft’s earnings sentiment has slipped to 29, suggesting investors are still sorting winners from losers as capital spending and margin pressure collide.
For investors, the message is that Europe may offer cleaner exposure to AI infrastructure and adoption than the crowded U.S. trade. If AI spending keeps broadening beyond chips and cloud hyperscalers, Europe’s software and equipment names could continue to attract flows even as the market questions how much profit the biggest American platforms can ultimately keep.
| Entity | Gains | Losses |
|---|---|---|
| SAP | ▲AI-driven enterprise software demand | ▼Buyers of lagging software names |
| ASML | ▲Semiconductor capex tied to AI | ▼Chipmakers facing supply bottlenecks |
| Salesforce | ▲CRM demand and AI adoption | ▼Short-term skeptics on AI monetization |
| U.S. megacaps | ▲More cautious capital allocation | ▼High-cost AI spenders under margin pressure |