The AI data center trade is broadening beyond Big Tech, and investors are rewarding the picks-and-shovels names that stand to profit from the buildout without taking on the same capital intensity or execution risk as Microsoft. Vertiv, Equinix and American Tower have all held up better than the broader market as the sector’s spending cycle deepens, while U.S. industrial production and factory-gate prices point to an economy still capable of absorbing heavy infrastructure investment.
Vertiv, Equinix, American Tower Gain From AI Buildout
The shift matters because the AI buildout is no longer just a software story or a hyperscaler race. It is becoming a real-economy cycle that pulls in power, cooling, chips, towers, fiber, land and financing, creating revenue streams for infrastructure providers even when the largest cloud firms are the ones writing the biggest checks.
Vertiv, which supplies power and cooling systems for data centers, is the clearest stock-market expression of the theme. The shares closed at $250.62 on Oct. 2, down from a 52-week-like peak above $358 in May, but still well above the 200-day moving average near $264.50 and the 50-day moving average near $260.69, underscoring how much of the AI premium remains embedded despite the pullback. Its RSI reading of 59.8 suggests momentum has cooled from overbought levels, but the stock remains tied to one of the market’s strongest secular spending trends.
Equinix, the largest pure-play colocation name, is also benefiting from the same demand. The stock finished at $1,025.47 on Oct. 2, roughly flat versus its 200-day moving average around $980 and below its 50-day moving average near $1,042, after earlier this year touching above $1,066. The company sits at the center of enterprise and cloud interconnection, giving it exposure to AI deployment without requiring it to build frontier models or own the expensive chips behind them.
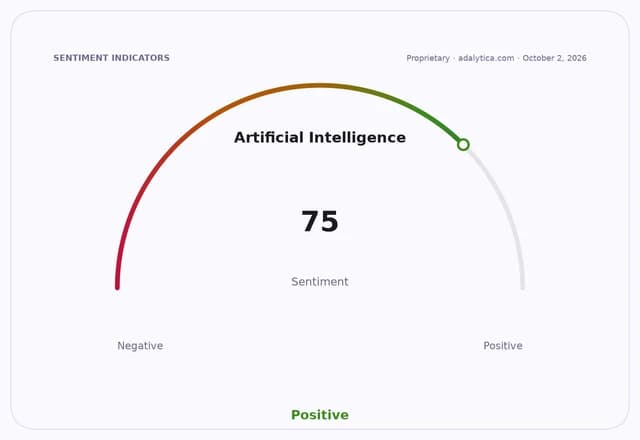
Artificial Intelligence vs VRTadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
American Tower, meanwhile, gives investors a different way to play the infrastructure theme through global communications sites and edge connectivity. Shares closed at $163.13 on Oct. 2, with the stock still below both its 50-day moving average near $171.17 and 200-day moving average around $173.24, suggesting the market has yet to fully re-rate the tower business on AI demand alone. That gap may matter if data traffic, edge compute and private network demand keep rising.
The macro backdrop is still supportive. U.S. industrial production rose to 103.0682 in August from 102.842 in June, while core producer prices have edged up to 287.928 from 285.181 over the same period, signaling an economy that is absorbing new investment without obvious strain in the near term. The 10-year Treasury yield at 5.29% is higher than levels seen earlier in the cycle, but not high enough to stop capital from flowing into assets linked to AI infrastructure.
For investors, the implication is straightforward: the AI opportunity set is wider than the mega-cap names that dominate the conversation. The next leg of the trade may come from companies selling the shovels, real estate and power systems needed to keep the boom running, even as rising electricity demand, local permitting fights and cost pressure test how fast the buildout can go.
The key catalyst is whether spending on AI facilities keeps accelerating into 2027 without triggering a sharper slowdown in financing, regulation or customer demand.
| Entity | Gains | Losses |
|---|---|---|
| Vertiv | ▲AI cooling/power orders | ▼Margin pressure if buildout slows |
| Equinix | ▲Colocation and interconnect demand | ▼Higher capex and rates risk |
| American Tower | ▲Edge connectivity growth | ▼Slower tenant demand |
| Microsoft and hyperscalers | ▲Faster AI capacity | ▼Bigger capital spending burden |