Digital Realty Trust and Equinix are emerging as the clearest public-market way to play the AI data-center boom, but the bigger investor question is no longer demand — it is whether scarce power, higher capital spending and rich valuations will still produce attractive returns.
Digital Realty and Equinix in AI data-center boom
Both REITs own powered, connected capacity that is hard to replace in a market where AI buildouts are colliding with tighter permitting and electricity constraints. That scarcity supports pricing, but it also raises the bar on new development and makes financing discipline as important as leasing momentum.
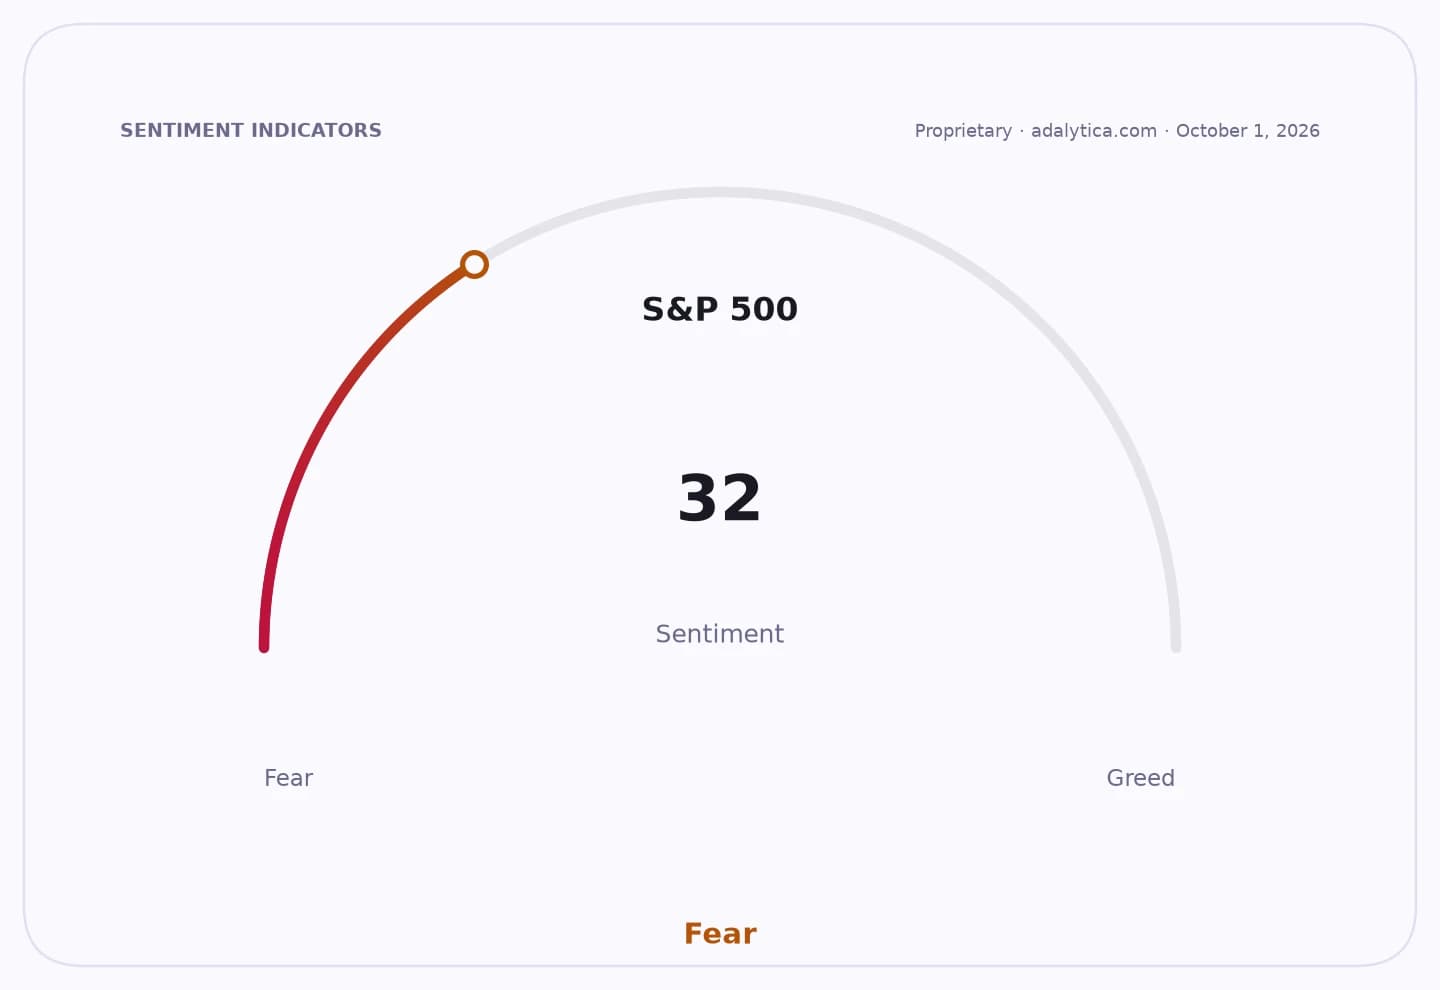
Sentiment IndicatorsⓘProprietary · adalytica.com · September 30, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Digital Realty has the sharper near-term earnings setup. Second-quarter revenue jumped 29% to $1.9 billion, core FFO per share excluding promote income rose to $2.13 from $1.87 and signed-but-not-commenced backlog reached $1.4 billion of annualized base rent at its share. July added two hyperscale leases worth another $205 million of annualized rent at its share, while cash renewal rents increased 25.4%.
The trade-off is heavier funding needs. Digital Realty sold 13.5 million shares through its ATM program in the first half, raising about $2.5 billion, and lifted net development capex guidance to $4.25 billion to $4.75 billion. The stock trades at about 22 times the midpoint of its 2026 core FFO guidance, cheaper than Equinix but still demanding for a capital-intensive expansion story.
Equinix has the stronger moat, and investors are paying for it. The company’s network density and interconnection ecosystem helped second-quarter monthly recurring revenue rise 11% year over year, while normalized constant-currency AFFO per share increased 18%.
Management now expects 2026 revenue growth of 11% to 12% and AFFO-per-share growth of 10% to 12%, with adjusted EBITDA margins around 51%. But Equinix also carries about 4.9 times net debt to EBITDA and trades at roughly 24 times 2026 AFFO-per-share guidance, a premium that leaves less room for execution slips.
That premium is sitting alongside a sector-wide reality: AI infrastructure spending is still accelerating, with about $6 billion committed to new data-center developments in the latest wave of announcements. The opportunity is real, but so is the risk that a slowdown in AI-related investment, power bottlenecks or rising financing costs could delay returns on new capacity.
Investor positioning shows the market is not ignoring the story. Insider Monkey tracked 73 funds holding Digital Realty, up from 46 in the prior quarter, while Equinix also had 73 holders, up from 65. D. E. Shaw lifted its Digital Realty stake 43% to 1.54 million shares, and Coatue Management increased its Equinix position 17% to 1.27 million shares.
Technically, both stocks have cooled from earlier highs. Equinix has slipped back from the upper end of its recent trading range, while Digital Realty is sitting below its 50-day moving average, suggesting the market is re-testing how much growth is already priced in. The next catalysts are the companies’ ability to convert backlog into revenue, fund expansion without diluting returns and prove that AI demand can keep absorbing scarce power and new capacity.
| Entity | Gains | Losses |
|---|---|---|
| Digital Realty | ▲Near-term leasing momentum | ▼Heavy capex and dilution risk |
| Equinix | ▲Premium moat and recurring growth | ▼Higher valuation multiple |
| AI hyperscale tenants | ▲Access to scarce capacity | ▼Higher power and rent costs |
| Existing REIT holders | ▲Tighter supply supports pricing | ▼Slower returns if financing costs rise |