Americold Realty Trust’s 6.5% dividend yield is still attractive to income investors, but the market is signaling that the payout is compensating for sluggish growth rather than a fast-moving business.
Americold Realty Trust Yield and Growth Outlook
That tension is the core story for the cold-storage REIT. Americold owns and operates 224 warehouses globally, including 179 in North America, and says it accounts for about 18% of the domestic cold-storage market. That scale gives it strategic value in food logistics, but it has not translated into strong share-price momentum. The stock has been drifting below both its 50-day and 200-day moving averages, a sign that investors are still skeptical about near-term fundamentals even as the dividend yield remains elevated.
Sentiment Indicators
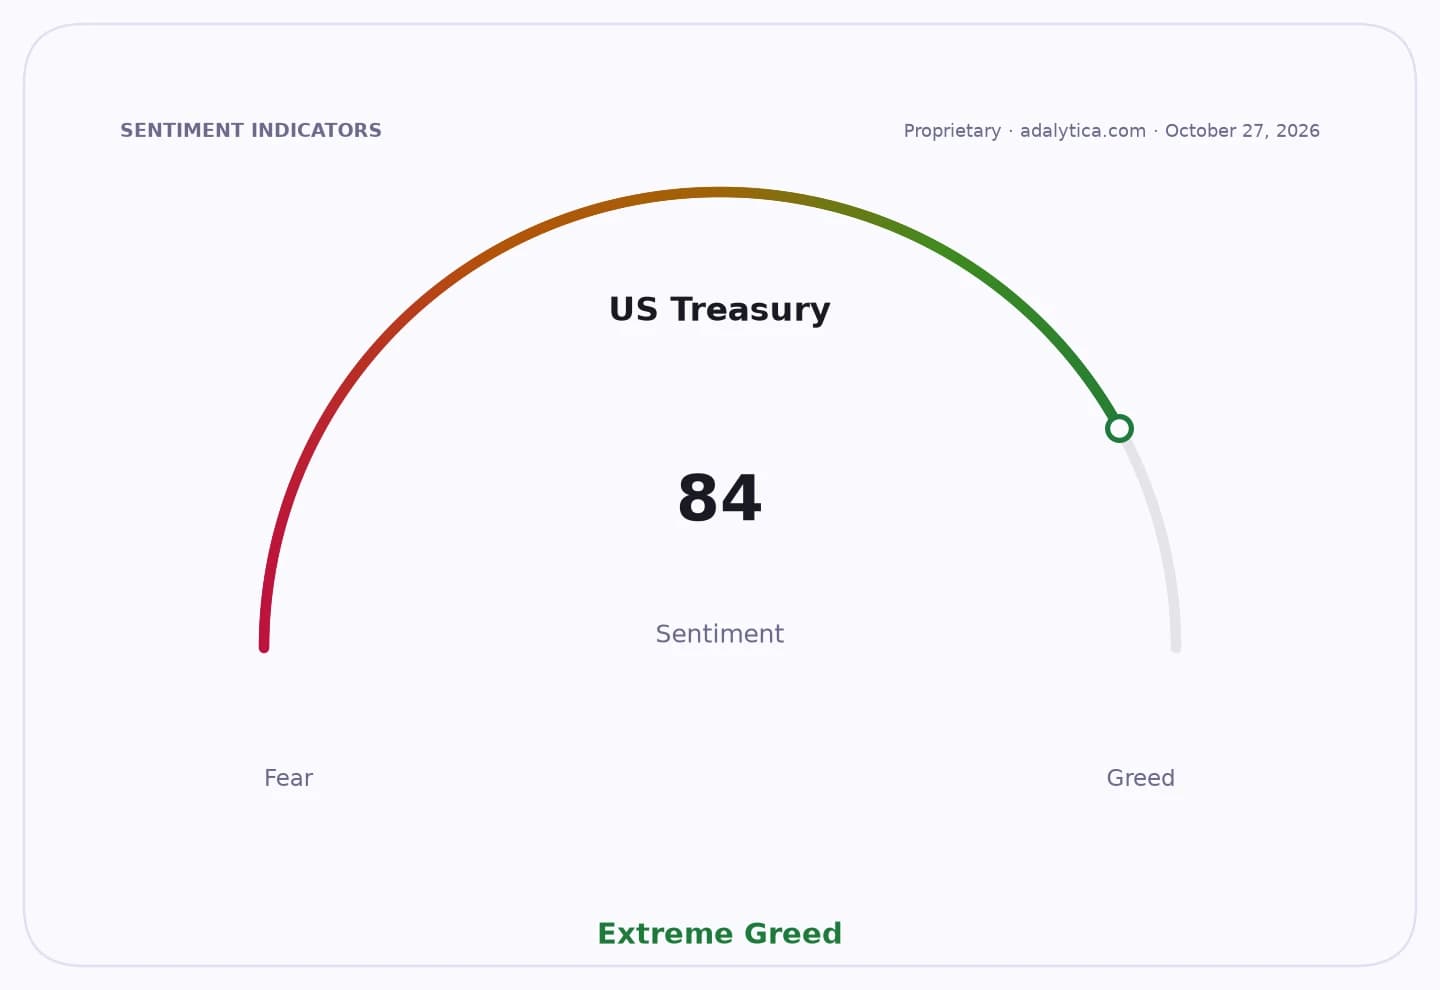
The broader backdrop matters. U.S. 10-year Treasury yields are near 5% and the federal funds rate is still around 3.75%, leaving income assets under pressure to compete with risk-free cash and bonds. In that environment, REITs with limited earnings growth are harder to rerate because investors can collect similar income elsewhere without taking equity risk. Adalytica’s S&P 500 trade signals show “Extreme Fear” in sentiment even as awareness remains elevated, underscoring how defensive capital has become. For REITs, that often means high yields are viewed less as a gift and more as a warning that distribution growth is constrained.
Americold’s appeal is its defensible niche. Cold storage is expensive to build, highly regulated and difficult to replicate, which supports long-term pricing power. Food supply-chain complexity and inventory management needs should keep demand stable over time. But the near-term thesis is weaker: growth is being capped by a still-tight rate environment, limited catalyst visibility and investor preference for names with clearer rent and same-store growth. That helps explain why the market has been more willing to own larger REIT platforms with stronger operating momentum and broader diversification, such as Simon Property Group, whose shares have been more resilient.
For investors, the question is whether the 6.5% yield is enough compensation for a period of flat fundamentals. If rates stay elevated and cap rates remain under pressure, Americold may continue to look like a bond substitute with equity volatility rather than a growth REIT. The bull case is that its market share, asset scarcity and essential infrastructure role eventually support steadier cash flow and valuation support. The bear case is that income seekers can find similar or better yields elsewhere while waiting for growth that may take longer to arrive.
| Entity | Gains | Losses |
|---|---|---|
| Americold Realty Trust | ▲Income seekers | ▼Growth investors |
| Bondholders / cash holders | ▲Higher relative yields | ▼REIT re-rating |
| Cold-storage tenants | ▲Stable logistics access | ▼Higher rental costs |
| Competing REITs with faster growth | ▲Relative valuation edge | ▼Americold as a yield substitute |