Anglo American’s iron ore sales rose in the third quarter even as production fell, underscoring how the miner is leaning on inventory drawdowns and stronger deliveries to keep volumes moving while a major upgrade at Kumba Iron Ore crimps output.
Anglo American Q3 iron ore sales rise on stock drawdown
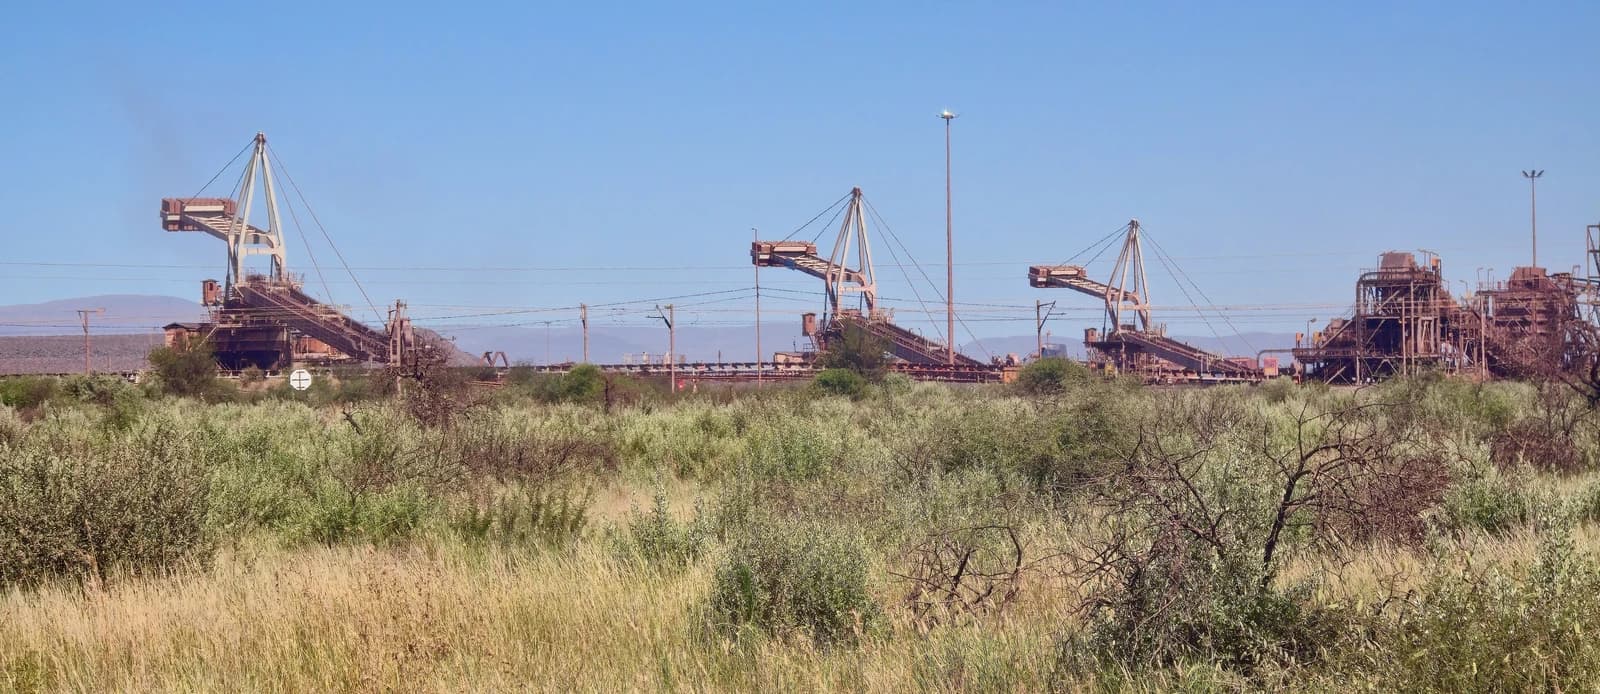
The group said combined iron ore production from Kumba in South Africa and Minas-Rio in Brazil fell 4% year on year to 13.798 million metric tons in the quarter ended Sept. 30, and dropped 10% from the prior quarter. Sales, however, climbed 9% from a year earlier to 15.75 million tons, helped by planned stock reduction at Kumba.
Sentiment Indicators
The mismatch matters because iron ore remains Anglo American’s biggest cash engine even as benchmark prices come under pressure from fading Chinese demand. The most-traded iron ore contract in Dalian recently fell to the lowest level in more than two years, adding strain across the sector and making every ton shipped more important for near-term cash flow and margins.
Kumba bore the brunt of the production decline. Output from the South African business slid 19% year on year to 7.5 million tons after a planned shutdown at the Sishen mine to integrate the first ultra-high density media separation, or UHDMS, project. Kumba’s sales still rose to 9.702 million tons as finished product inventories were drawn down to 5.1 million tons from 7 million tons at the end of the second quarter.
Minas-Rio offset part of that weakness, with production up 24% from a year earlier to 6.298 million tons as utilization improved at its beneficiation plant. Anglo said higher plant use supported Brazilian output even as quarterly production eased 4% from the second quarter.
For investors, the key point is that Anglo left its 2026 iron ore production guidance unchanged at 55 million to 59 million tons and held unit cost guidance at about $41 a ton. That suggests the Q3 production dip is being treated as a timing issue rather than a deeper operational setback, even as the company concentrates more of Kumba’s output in the first half of the year.
The next test is whether Anglo can keep volumes and costs on track into year-end while the iron ore market remains weak and China’s demand outlook stays uncertain. Any further price slippage, or a slower-than-expected recovery in shipments after the shutdown, would put more pressure on earnings from a business still central to Anglo’s portfolio.
| Entity | Gains | Losses |
|---|---|---|
| Anglo American | ▲higher quarterly sales | ▼lower Q3 production |
| Kumba Iron Ore | ▲inventory drawdown supports shipments | ▼shutdown cuts output |
| Iron ore buyers | ▲more available tons | ▼weaker price leverage |
| Competitors with higher costs | ▲none | ▼softer pricing backdrop |