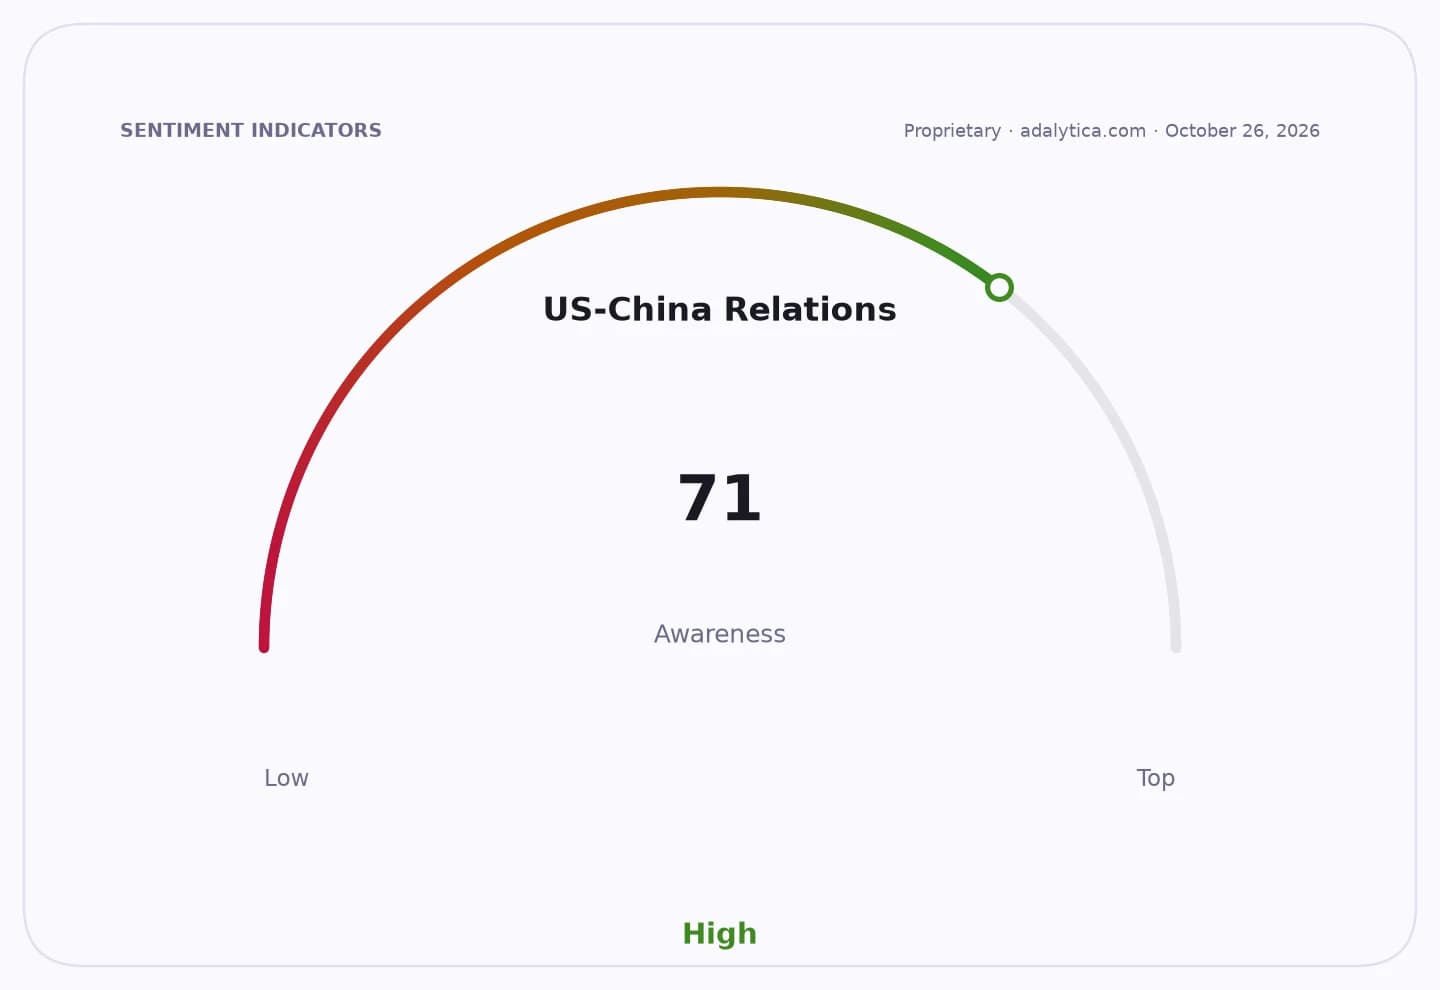
Anthropic’s coming public offering is running straight into a geopolitical and competitive reality the market may be underpricing: Chinese AI models are getting cheaper, better and harder to ignore.
Anthropic IPO Faces Chinese AI Competition
That matters because Anthropic is being valued on the assumption that demand for frontier AI will keep compounding at breakneck speed. Hedgeye Risk Management says investor questions are increasingly centered on whether low-cost Chinese rivals can compress pricing, slow enterprise adoption or force a more expensive product race just as the company prepares for a blockbuster IPO.
The concern is not theoretical. Anthropic told investors in a private briefing last week that third-quarter revenue rose nearly 50% from the previous quarter to $16.8 billion, according to a person familiar with the matter. That is the kind of growth rate that can justify a premium multiple — until competition starts eating into the narrative that only a handful of Western labs can dominate the next wave of AI spending.
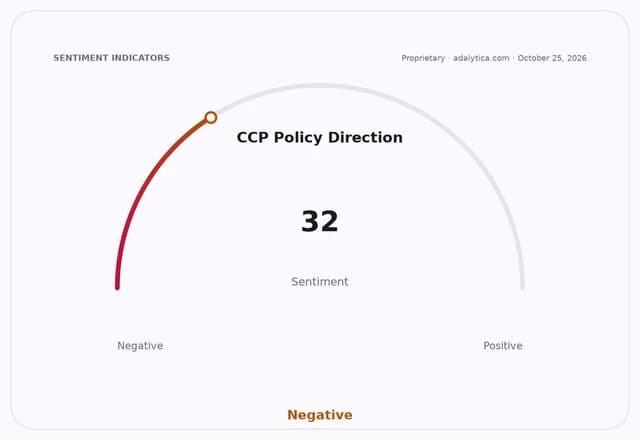
For investors, the issue is less about whether Anthropic can grow and more about how durable that growth is when Chinese models are increasingly viewed as good-enough substitutes at a fraction of the cost. If buyers can access capable domestic alternatives, the pricing power embedded in today’s AI boom becomes harder to defend. That would hit not just Anthropic’s IPO valuation, but the broader Silicon Valley trade built on assumptions of endless model-upgrade cycles, ever-rising inference spend and expanding enterprise budgets.
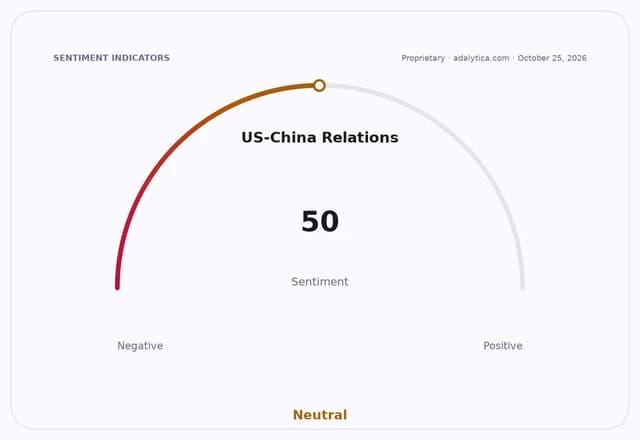
The timing is awkward. Markets are already wrestling with the second-order effects of the AI capex surge, from chip demand to cloud infrastructure to energy use. Microsoft and Nvidia have both flagged geopolitical and export-control risks in recent filings, underscoring how quickly the AI supply chain can become a political chokepoint. If China’s model ecosystem keeps improving, the winners may not be the labs with the flashiest growth headlines, but the infrastructure players that sell compute, networking, power and cooling into a still-expanding global race.
That is why this IPO deserves more scrutiny than a standard AI listing. Anthropic may still be one of the few private AI names capable of commanding real public-market attention, but the market is now pricing a global AI arms race, not a sheltered U.S.-only growth story. The market underestimates how quickly Chinese competition can turn a hypergrowth narrative into a margin and multiple debate.
The investable takeaway is clear: Anthropic’s IPO may be a benchmark event, but the better long-term opportunity may sit with the picks-and-shovels that profit regardless of which AI model wins the software layer.
| Entity | Gains | Losses |
|---|---|---|
| Anthropic IPO buyers | ▲Exposure to AI growth | ▼Premium valuation risk |
| Chinese AI model makers | ▲Share gains at lower cost | ▼U.S. scrutiny and barriers |
| AI infrastructure suppliers | ▲More compute and power demand | ▼Less if model pricing erodes |
| U.S. AI incumbents | ▲None | ▼Pricing power and margin pressure |