Argentina’s market selloff is colliding with a new political risk in Washington, where Democrats in Congress are pushing to make it harder for President Donald Trump to extend support to Javier Milei’s government.
Argentina Market Falls on U.S. Aid Risk
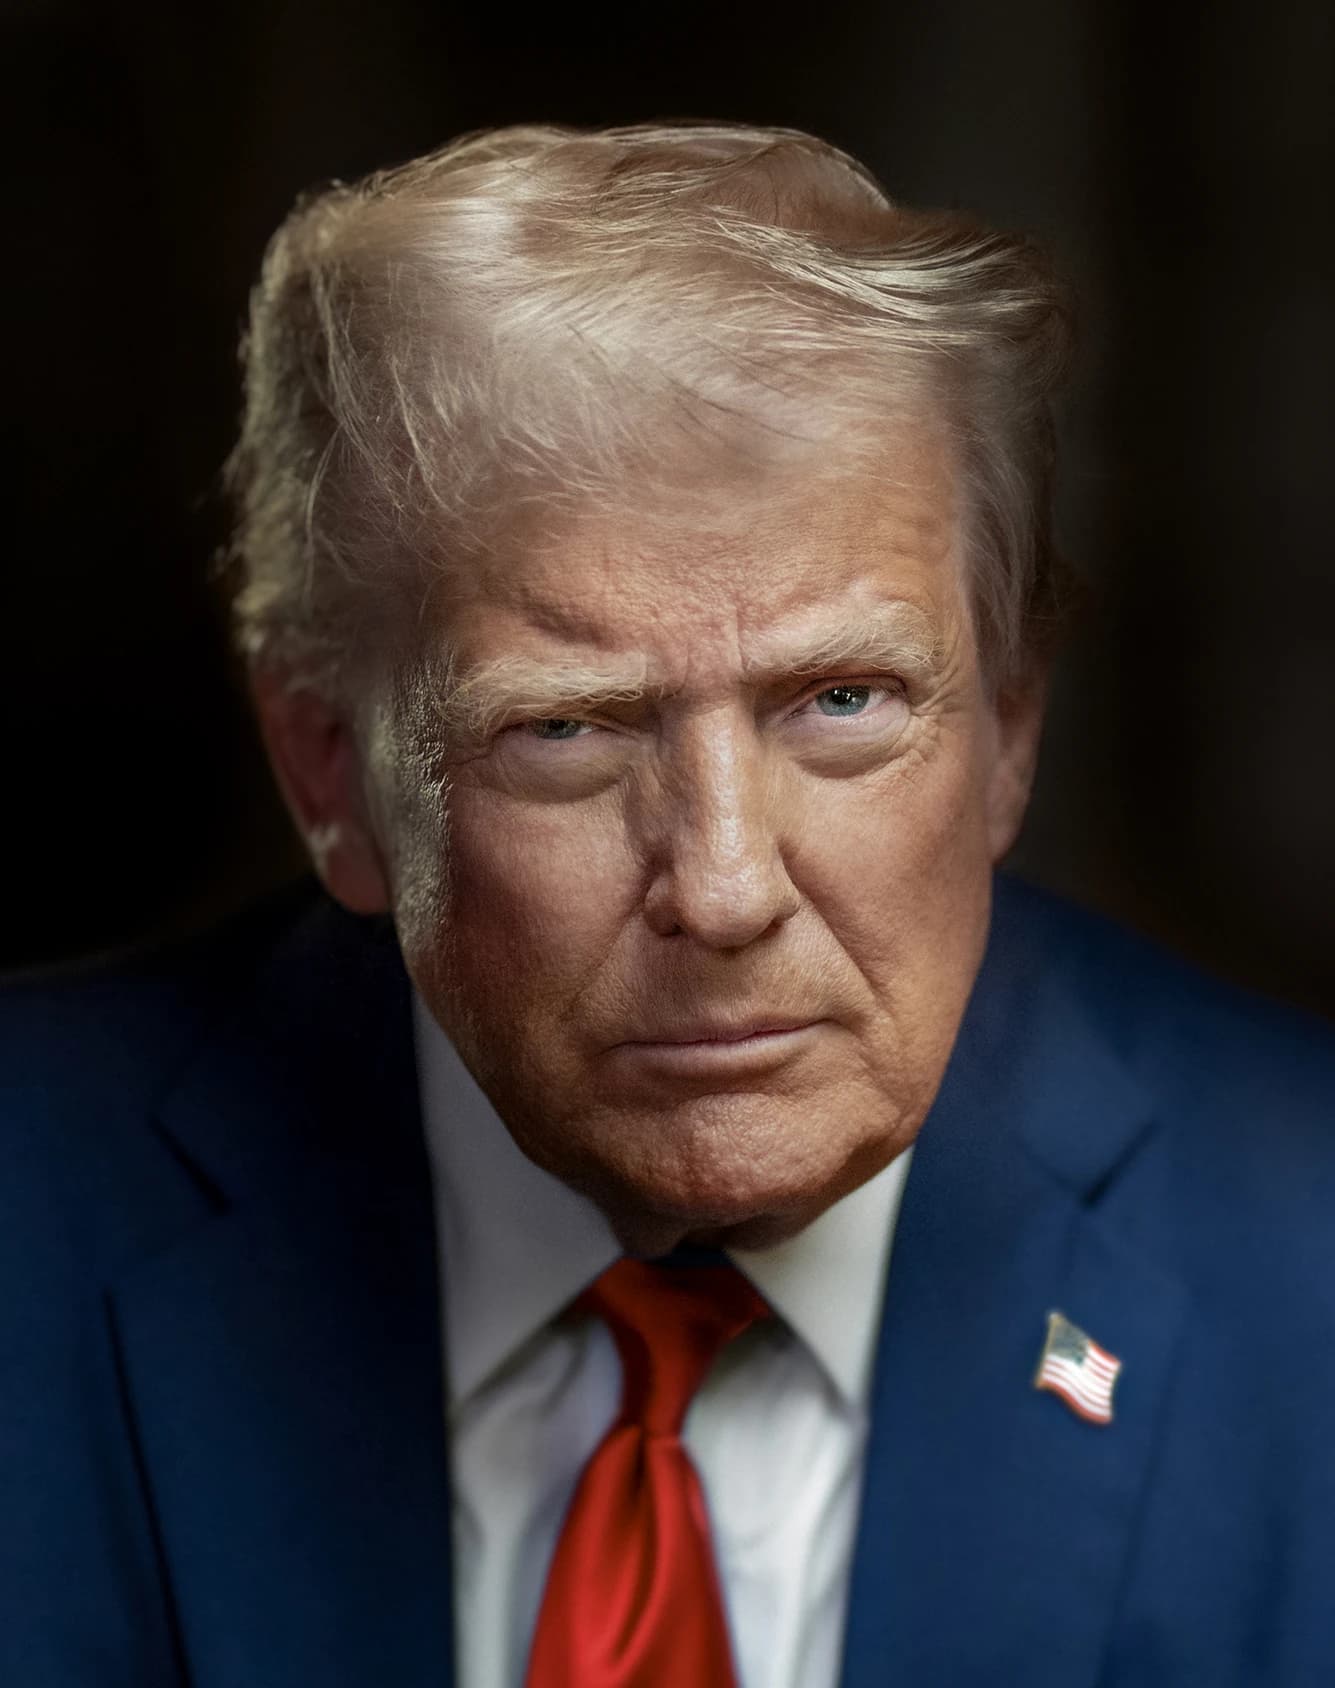
That matters because Argentina does not just need political goodwill — it needs financing, and it needs it soon. The country’s sovereign risk premium has jumped to 927 points, a level that underscores how expensive it remains for Buenos Aires to borrow in global markets. Dollar bonds have fallen as much as 4%, showing investors are still demanding a steep discount to hold Argentine debt even after earlier hopes that Milei’s austerity program could restore credibility.
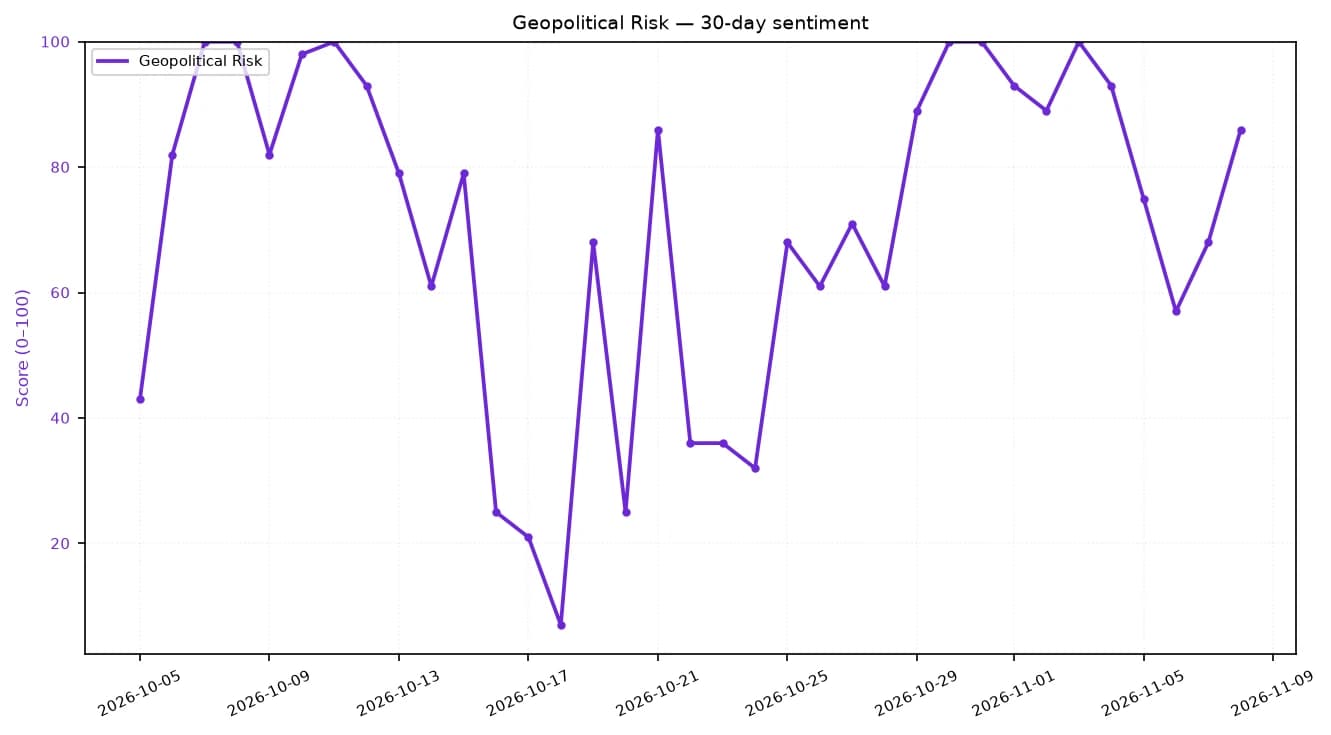
Sentiment Indicators
The weakness is spilling into Argentine assets more broadly. The Argentina-focused ETF ARGT has fallen to $73.72, down sharply from $96.39 in July, while the telecom name Telecom Argentina, traded in New York under TEO, has dropped to $10.31 from $15.98 in June. Those declines reflect more than day-to-day volatility: they point to a market that is still pricing in fragile growth, thin confidence and limited room for policy mistakes.
For long-term investors, the core issue is whether Milei can keep delivering reform without fresh external support, or whether U.S. politics and Argentina’s own financing needs force another cycle of stress. The country’s risk profile is still being driven by the same familiar forces — debt burden, currency pressure and dependence on foreign capital — but the added uncertainty around Trump’s willingness, and ability, to back Argentina makes the investment case even more binary.
Geopolitical Risk vs ARGTadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.
There is also a broader lesson here. When political support is uncertain and bond markets are already signaling distress, equity upside becomes highly dependent on policy execution rather than just cheap valuations. That can create opportunity for patient investors if reforms take hold, but it also argues for caution until Argentina proves it can finance itself on better terms.
For now, Argentina remains a high-risk, high-reward bet best suited to investors who can tolerate volatility and wait years, not months, for a turnaround.
| Entity | Gains | Losses |
|---|---|---|
| Argentine bondholders | ▲Higher upside if support arrives | ▼Mark-to-market losses now |
| Milei government | ▲Easier financing if backed | ▼Less room to maneuver |
| Democrats in Congress | ▲Political leverage | ▼Faster aid for Argentina |
| Argentine equity investors | ▲Rebound potential on reform | ▼Ongoing volatility and dilution risk |