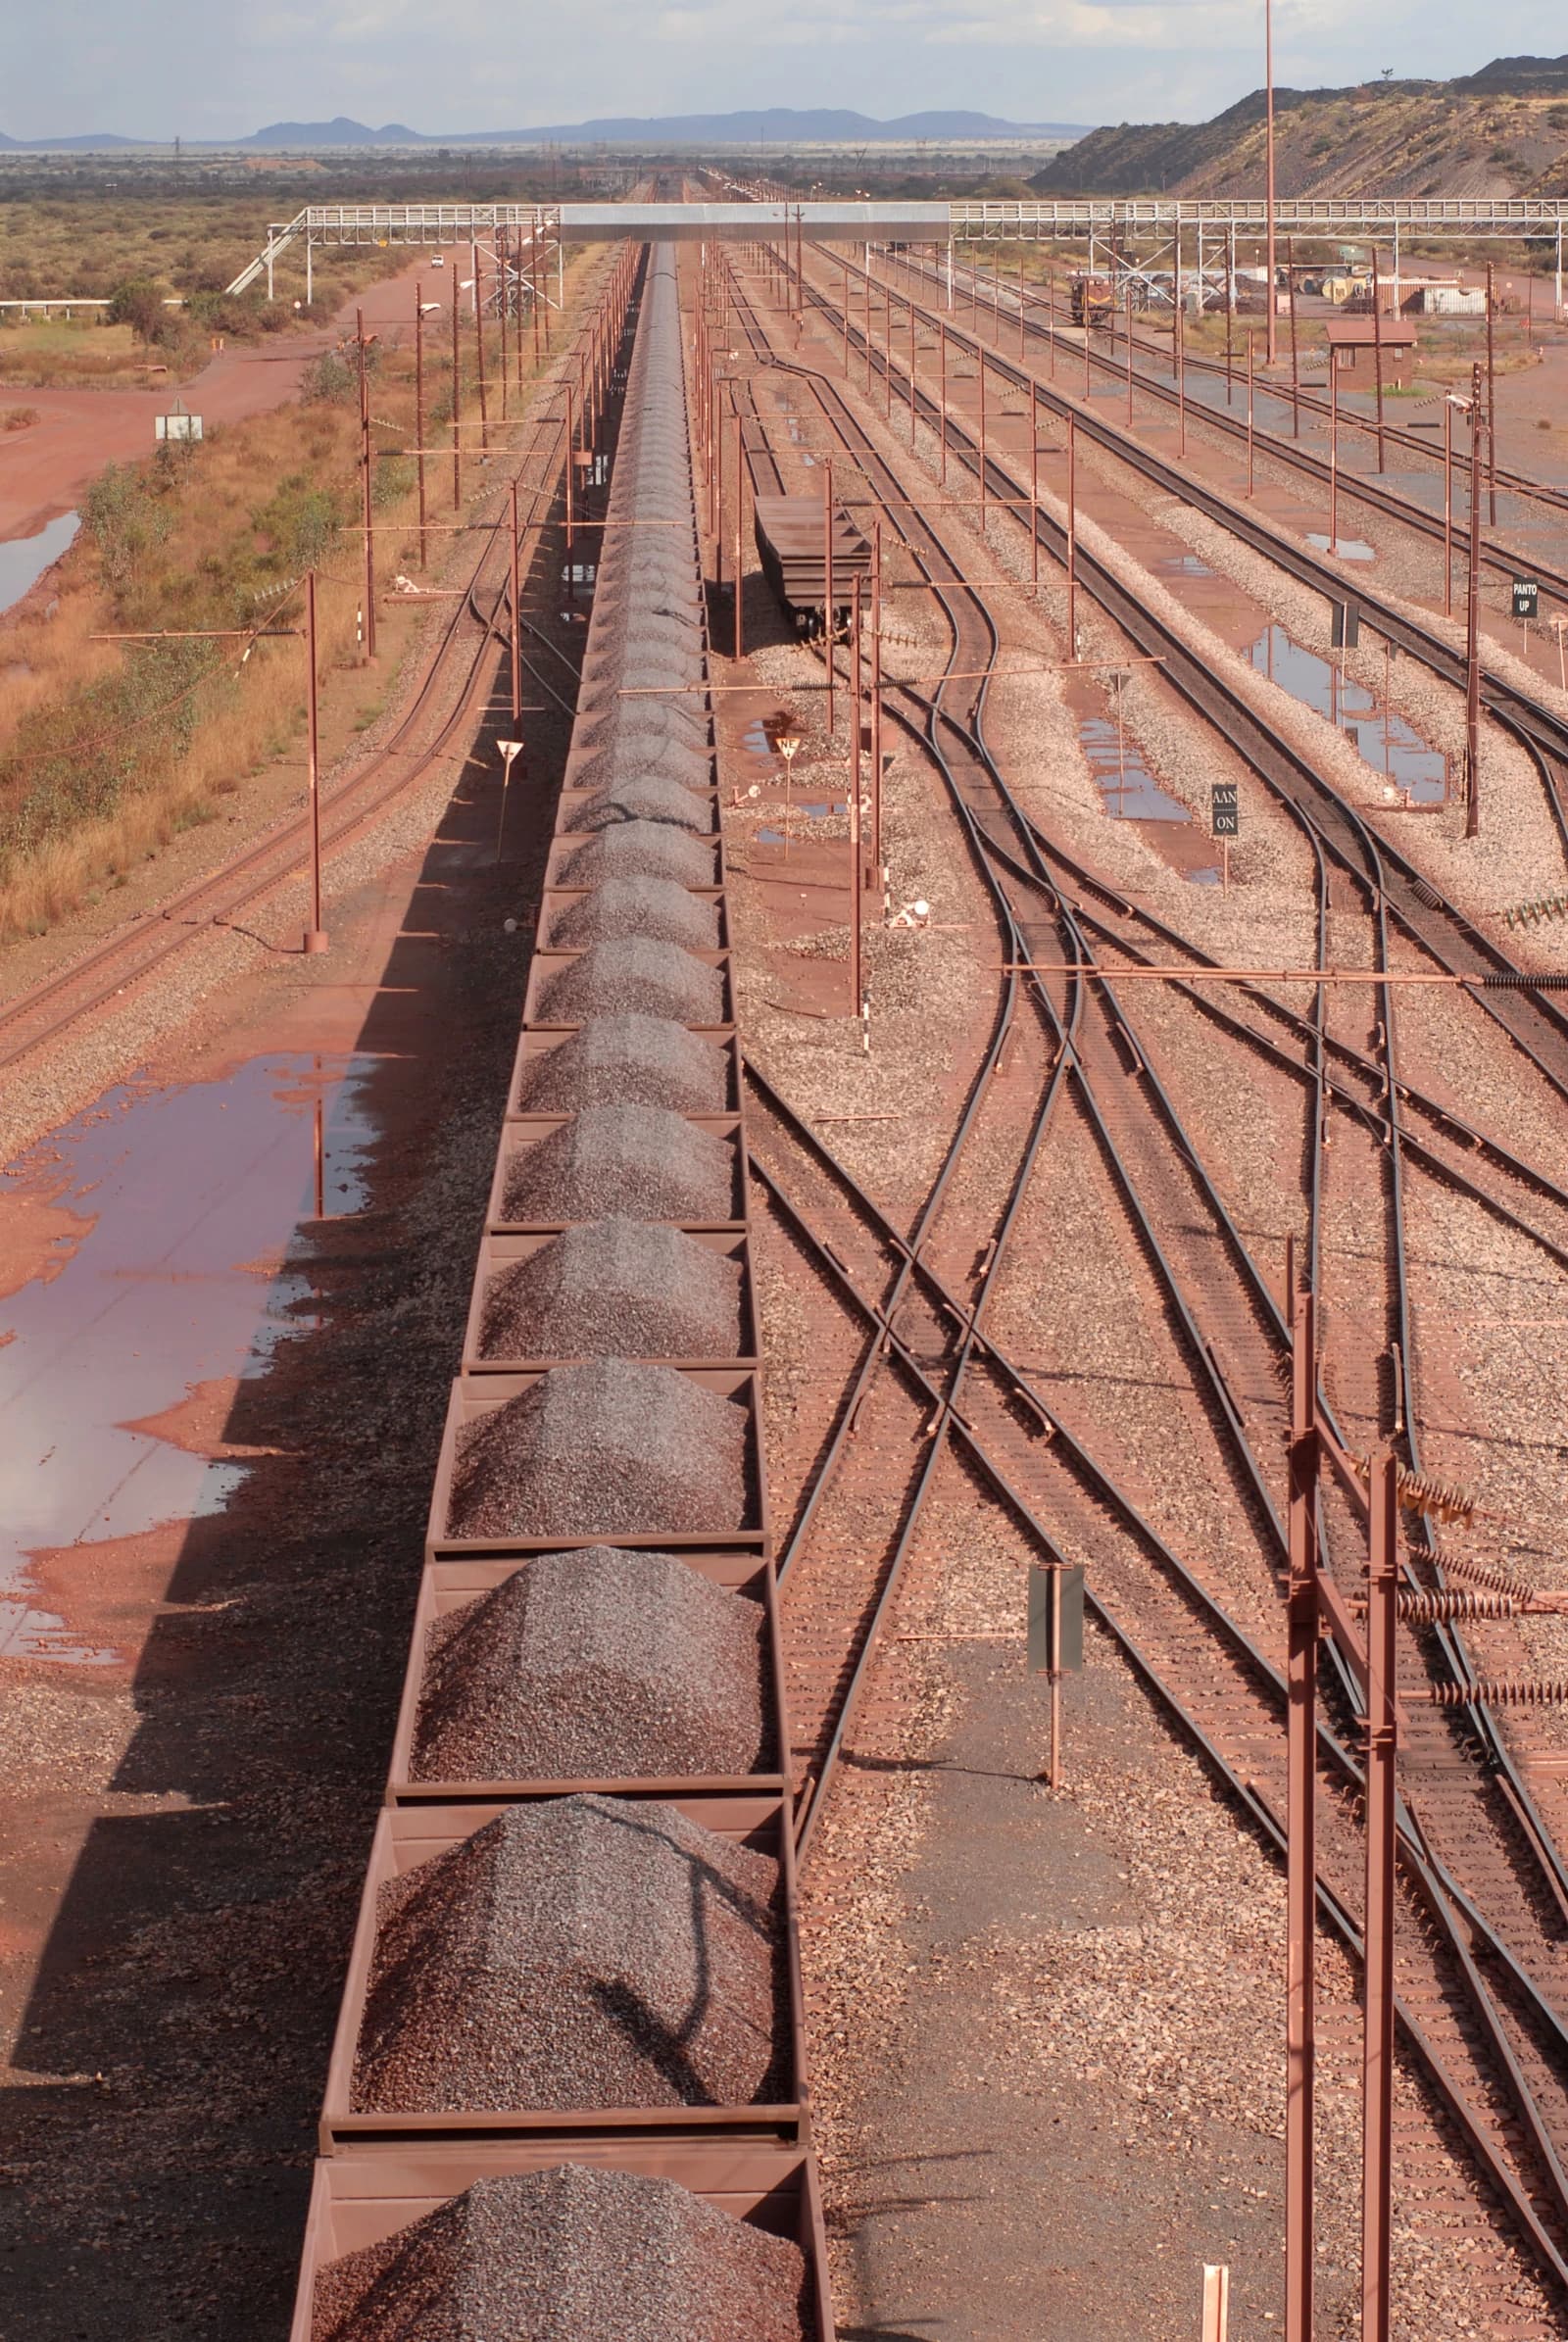
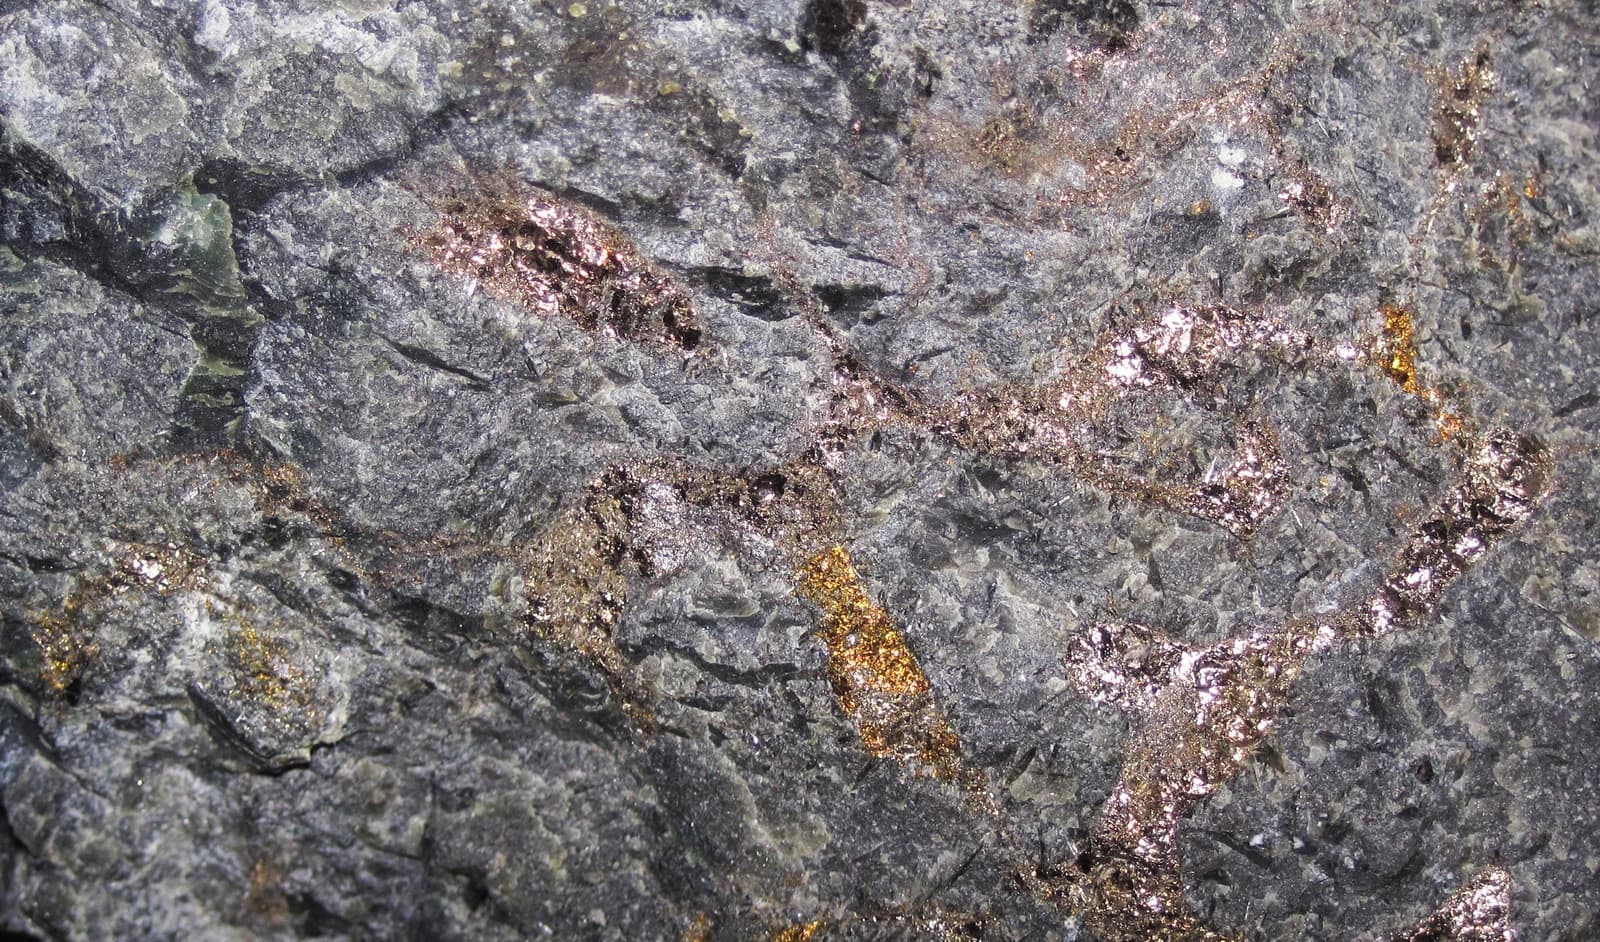
Arrow Minerals is rapidly enlarging its footprint in Western Australia’s Pilbara with an agreement to acquire the Turee Creek Iron Ore Project and 12 new exploration licence applications, a move that could give the junior miner more than 1,600 square kilometres of tenure in one of the world’s most closely watched iron ore regions.
Arrow Minerals expands Pilbara iron ore tenure
The deal matters because Arrow is not just adding ground — it is assembling a larger exploration platform around major producers including Rio Tinto, BHP rival Fortescue Metals Group, Mineral Resources and Hancock Prospecting. In a sector where the quality of land position often determines future drilling optionality and eventual takeover appeal, the company is trying to secure scale in a proven iron ore belt before committing to a major exploration campaign.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Arrow said the acquisition and applications will expand its Pilbara iron ore landholding by more than 400% to over 1,600 km². Roughly 833 km² of tenure is now held in the Turee Creek area through the acquisition and related applications, including 48 km² of mapped land in the Brockman Iron Formation, a key iron-bearing geological unit.
The Turee Creek project sits about 40 km from Rio Tinto’s Paraburdoo and Channar mines and covers a 48 km strike of the Brockman Iron Formation. Around 40% of the package is under transported cover, which Arrow says could conceal channel iron and detrital deposits that have not yet been properly tested.
Exploration at the project has been shallow. Previous operators, including FMG and Rio Tinto, drilled 51 reverse circulation holes totaling 3,372 metres, with testing on less than 5% of the prospective geology. Historical work returned an 8-metre intercept grading 54% iron from 22 metres depth, while rock chip samples averaged 45.2% iron and peaked at 64.2%.
Arrow will pay Ground Risk A$150,000 in shares and A$20,000 in cash for the Turee Creek acquisition. Ground Risk will also retain a 1.5% royalty, although Arrow has the right of first refusal to buy that royalty interest.
For investors, the deal is a low-cost land grab with leverage to any improvement in iron ore sentiment. The stock has traded above its 50-day moving average in recent sessions, but iron ore prices remain under pressure near two-year lows as China demand worries hang over the sector, keeping a lid on valuations for smaller exploration names.
Arrow managing director David Flanagan said the company is “fast building a potentially company-making land position” in the Pilbara. The next catalyst is whether Arrow can turn its enlarged tenure into drill targets and prove the project holds enough ore to matter in a market still dominated by demand uncertainty and heavyweight miners with far greater scale.
| Entity | Gains | Losses |
|---|---|---|
| Arrow Minerals | ▲Larger Pilbara land package | ▼Near-term capital and exploration risk |
| Ground Risk | ▲Cash, shares and royalty | ▼Loss of project control |
| Rio Tinto, FMG, Hancock, Mineral Resources | ▲Potential regional upside from exploration activity | ▼More competition for adjacent ground |
| Iron ore bulls | ▲New exploration catalyst in proven province | ▼Weak China demand backdrop |