ASML is emerging as one of the most important long-term winners from the AI buildout because every leading chipmaker still needs its lithography machines to make the next generation of advanced chips. That matters because Nvidia and AMD may design the AI accelerators everyone wants, but they cannot get those chips built at scale without the equipment ASML supplies.
ASML Gains on AI Chip Manufacturing Demand
The investment case is bigger than a single supplier relationship. AI spending is moving from the model-training phase into a much broader industrial upgrade cycle, and that requires more advanced semiconductors, more memory and more factory capacity. ASML sits at the center of that chain with a monopoly in extreme ultraviolet lithography, the process used to print the tiniest circuits on the most advanced wafers. In other words, the company gets paid whether Nvidia, AMD, TSMC, Intel or the memory makers ultimately win market share.
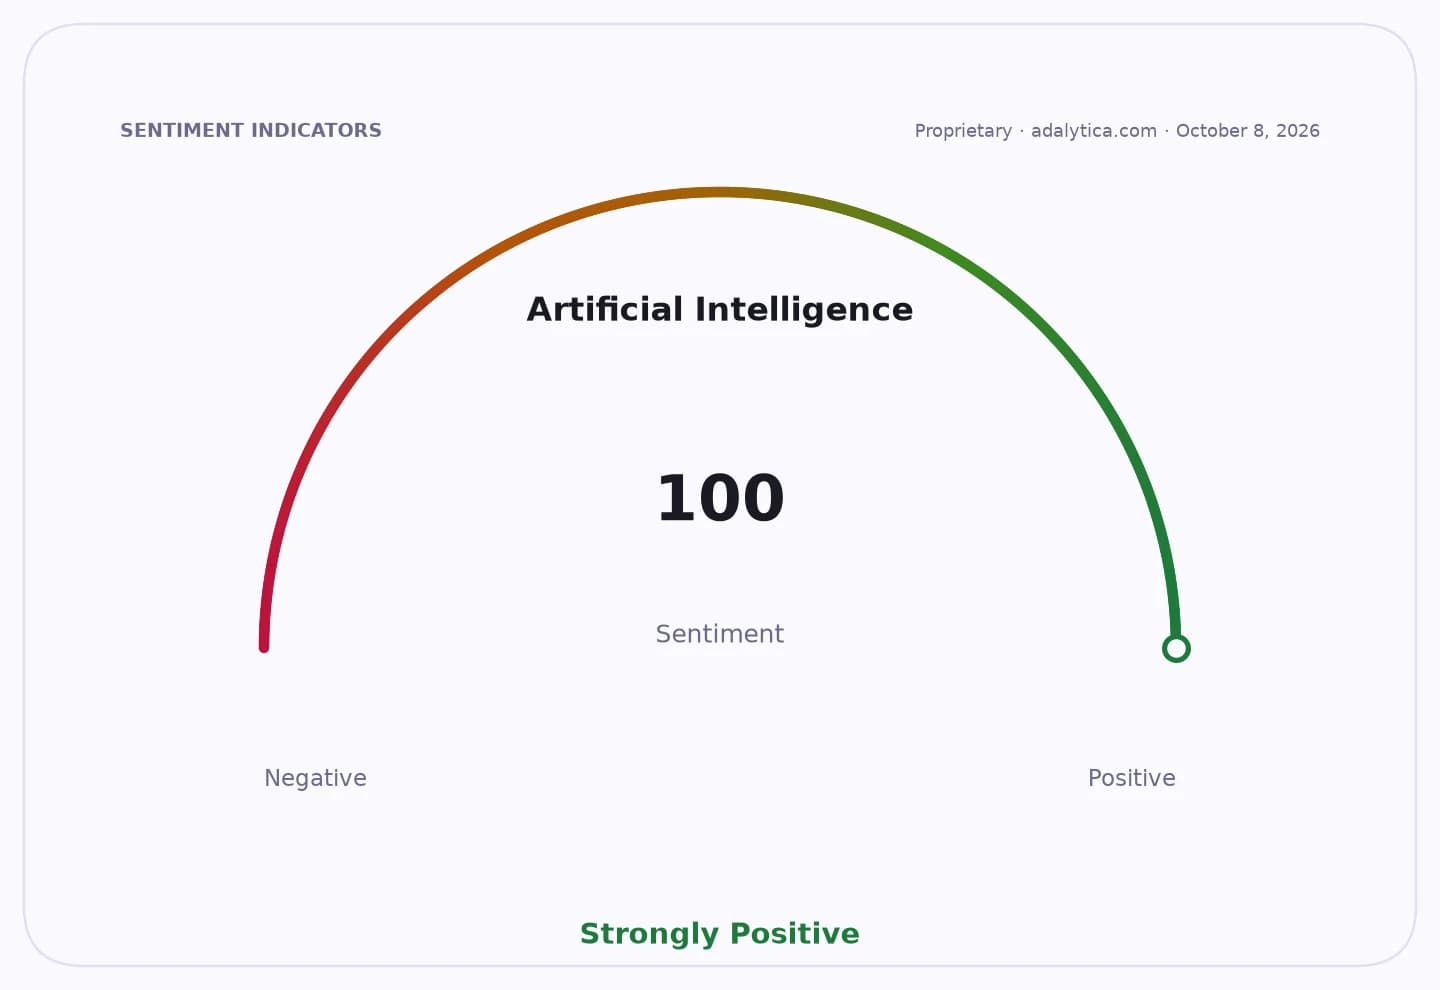
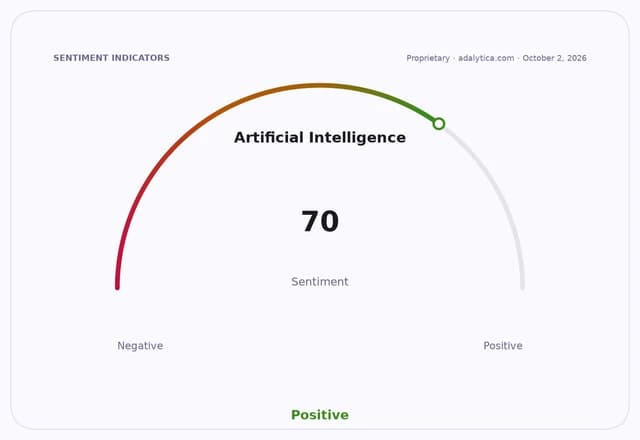
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That is why the stock’s latest run matters. ASML shares have climbed about 60% this year and recently traded around $1,808 to $1,834, well above the 50-day moving average and far above the 200-day moving average, a sign of strong momentum by conventional technical indicators. Nvidia and AMD are also holding firm, but the better question for patient investors is which business has the most durable tollbooth on the AI economy. ASML’s answer is simple: its machines are required for 3-nanometer, 2-nanometer and eventually 1.4-nanometer manufacturing, and demand is still broadening.
The numbers underline the opportunity. ASML said in July that it expects sales to foundry and logic customers to rise 25% this year, while system sales to memory makers should jump 75% in 2026. That second figure is especially important because high-bandwidth memory has become a bottleneck for AI servers, and memory shortages are expected to last until 2030, according to SK Hynix. For investors, that means ASML is not just riding one product cycle — it is serving multiple layers of AI infrastructure spending.
That is also why ASML has become a cleaner way to invest in the AI hardware boom than trying to pick the ultimate chip winner. Nvidia and AMD have been spectacular beneficiaries of AI demand, but they remain fabless, relying on TSMC for manufacturing and a wider ecosystem for memory and other components. ASML sells the equipment that makes that ecosystem possible. As AI design tools improve too — including new efforts such as Synopsys’ partnership with OpenAI to co-develop chip-design models — the industry’s demand for ever more sophisticated manufacturing should only increase.
Valuation still leaves room for optimism. ASML trades at about 28 times forward earnings, not cheap in absolute terms but not excessive for a company with a dominant moat, strong free cash flow and expected long-term earnings growth above 30% a year. For buy-and-hold investors, that combination is compelling: a mission-critical supplier, secular demand, and a business that can compound as AI spending spreads from chips to memory to manufacturing equipment. The main risks remain export controls and geopolitical friction, but the long-term setup still looks powerful enough to keep ASML on investors’ watchlists — and possibly in portfolios for years.
| Entity | Gains | Losses |
|---|---|---|
| ASML | ▲AI chip equipment demand | ▼Chipmakers needing lower capex |
| Nvidia | ▲Advanced chip demand | ▼Higher manufacturing bottlenecks |
| AMD | ▲AI accelerator growth | ▼Supply chain constraints |
| Memory makers | ▲HBM investment boom | ▼Buyers facing shortage pricing |