Australia is set to loosen a long-standing funding constraint on its banks, a move that could lower borrowing costs for mid-sized lenders and sharpen competition in a banking system dominated by the biggest players.
Australia raises bank covered bond cap
Treasurer Jim Chalmers said the government is releasing draft regulations to raise the cap on covered bond issuance, currently set at 8% of an institution’s total assets by the prudential regulator. The change is aimed at improving access to cheaper, longer-term funding and reducing reporting burdens for smaller banks, according to the government’s review of small and medium-sized lenders.
Sentiment Indicators
That matters because covered bonds are one of the few funding tools that can deliver stable money at scale while still appealing to conservative investors. In practice, easing the cap gives mid-tier Australian banks a better shot at matching the funding advantage of the majors, which already benefit from larger deposit franchises and easier market access. The policy is therefore less about headline deregulation than about changing the economics of competition in domestic lending.
For investors, the immediate read-through is positive for smaller and regional banks, which should gain more flexibility to issue secured debt at lower spreads and over longer maturities. That can support net interest margins, reduce refinancing risk and, over time, improve profitability relative to larger rivals. It may also appeal to income-focused bond buyers, who typically like covered bonds for their security and tighter credit profile compared with unsecured bank debt.
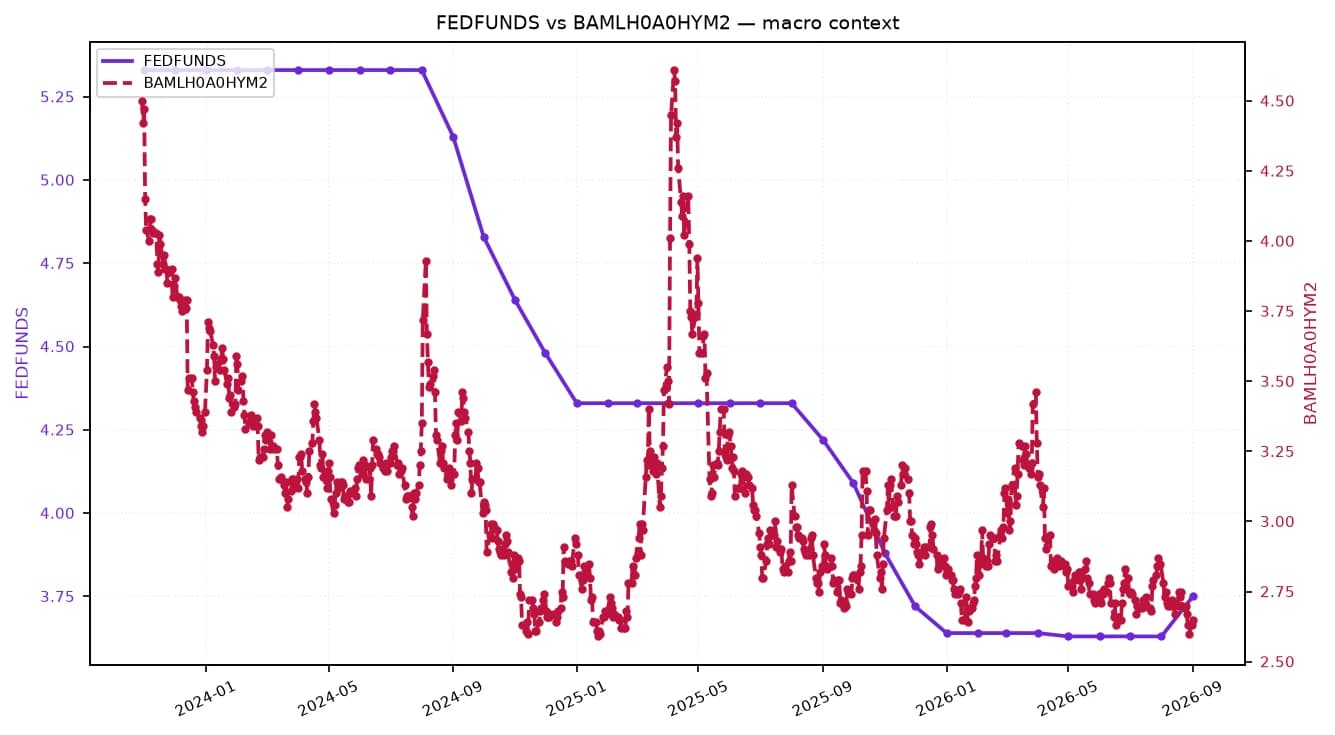
The timing also fits a market in which funding costs remain sensitive to global rates and term premia. With the U.S. 10-year yield hovering around 5% and credit markets still adjusting to higher-for-longer borrowing costs, any policy that expands access to stable domestic funding is economically relevant. It reduces dependence on more volatile wholesale markets and should make banks less exposed to swings in investor appetite.
Chalmers’ move fits a broader push to make Australia’s financial system more competitive without loosening core prudential safeguards. If the draft rules are enacted in their current form, the biggest beneficiaries will likely be the banks that sit below the top tier but still need to compete aggressively for mortgage and business lending. The market should watch for which lenders move first to tap the revised regime — and whether cheaper secured funding eventually translates into tougher competition on loan pricing.
| Entity | Gains | Losses |
|---|---|---|
| Mid-sized Australian banks | ▲Cheaper, longer-term funding | ▼Smaller relative funding disadvantage |
| Big four Australian banks | ▲Limited direct benefit | ▼Less pricing power in funding |
| Covered bond investors | ▲More supply of high-quality paper | ▼Tighter spreads over time |
| Unsecured bank debt holders | ▲— | ▼Possible relative demand shift away from unsecured issuance |