Australian home sellers have wiped nearly A$1.64 billion from asking prices, a sign that the country’s housing market is cooling fast enough to force discounts after years of relentless gains.
Australia Home Sellers Cut Asking Prices
The drop matters because housing is one of the biggest transmission channels for household wealth, consumer confidence and mortgage demand. When sellers trim expectations, it usually means buyers have more leverage, listings are taking longer to clear and price discovery is shifting away from the froth that defined the pandemic-era boom.
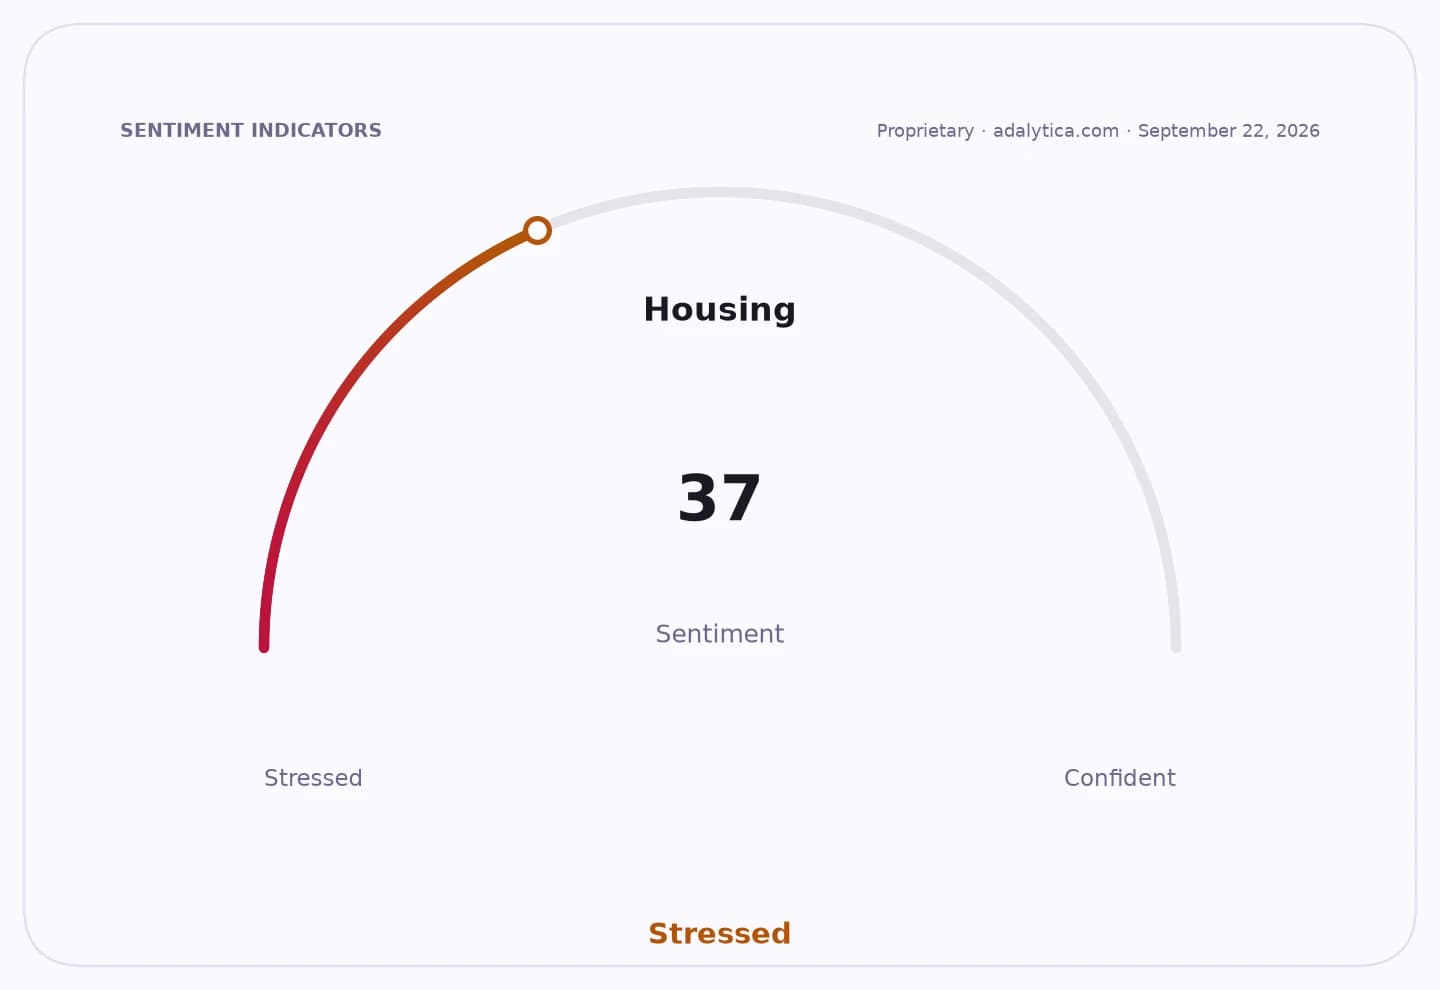
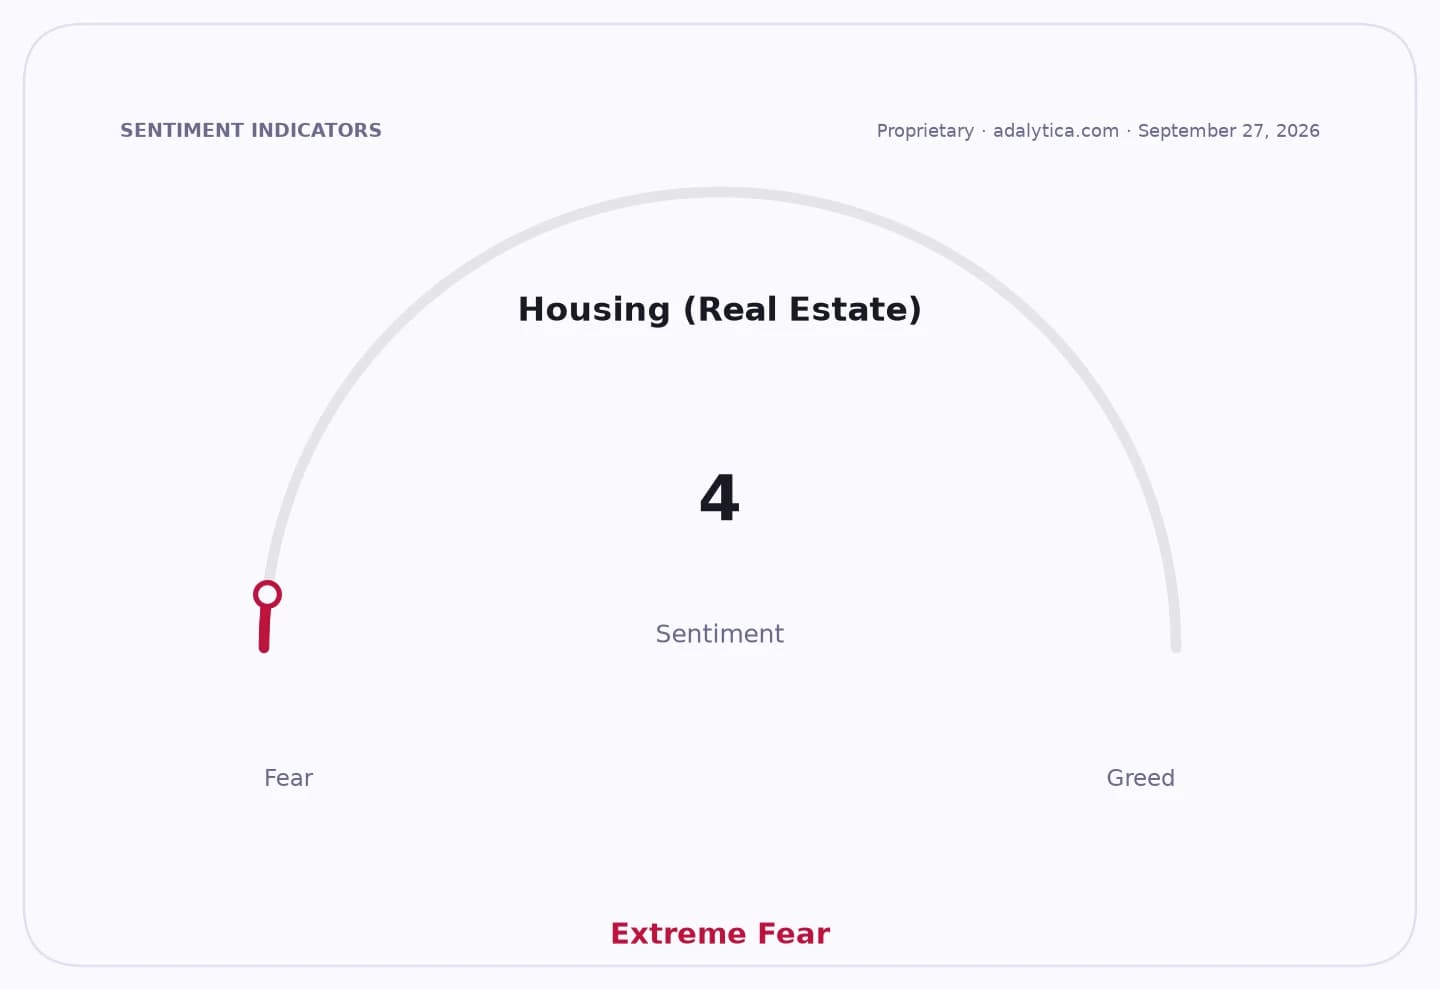
Sentiment IndicatorsⓘProprietary · adalytica.com · September 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The pressure is showing up against a backdrop of still-elevated borrowing costs. Australia’s policy rate is well above the emergency levels of 2020, and global bond yields remain high enough to keep mortgage servicing costs painful for many households. In the U.S., the 10-year Treasury yield has moved back toward 5%, underscoring how stubbornly restrictive financing conditions remain across developed housing markets.
For investors, softer asking prices are a warning for homebuilders, brokers, listings platforms and lenders exposed to transaction volumes. Lower sticker prices can help affordability at the margin, but they also tend to signal weaker turnover and thinner commissions, which can hit earnings even if underlying demand is holding up.
The move also fits a broader pattern in housing markets where affordability has become the main constraint, not demand alone. In Australia, as in parts of Europe and North America, higher rates are forcing sellers to choose between waiting for better conditions or taking a cut now.
For property investors, the key question is whether this is a short-lived adjustment or the start of a broader re-rating. The next read on mortgage rates, listings and clearance rates will show whether sellers keep conceding ground or whether buyers step back in.
| Entity | Gains | Losses |
|---|---|---|
| Home buyers | ▲Better affordability | ▼Less urgency to bid |
| Sellers | ▲Faster sale chances if they cut | ▼Lower proceeds |
| Mortgage lenders | ▲More rate-sensitive demand if prices reset | ▼Weaker loan growth if turnover stays low |
| Property platforms and agents | ▲More listings activity | ▼Lower transaction commissions |