Australia and New Zealand faced the same inflation shock, but they did not make the same policy choice — and the labour-market gap that opened up matters for workers, growth and the long-term health of both economies.
Australia and New Zealand inflation policy split
That is the core message from a new Australian Council of Trade Unions report, which argues that Australian policymakers chose to protect employment through the post-pandemic inflation surge while New Zealand’s government and policy mix put far more of the burden on workers. For investors, the lesson is bigger than an election-season talking point: when inflation is driven by global supply shocks rather than overheating domestic demand, the difference between defending jobs and deliberately slowing the economy can shape everything from consumer spending to recession risk.
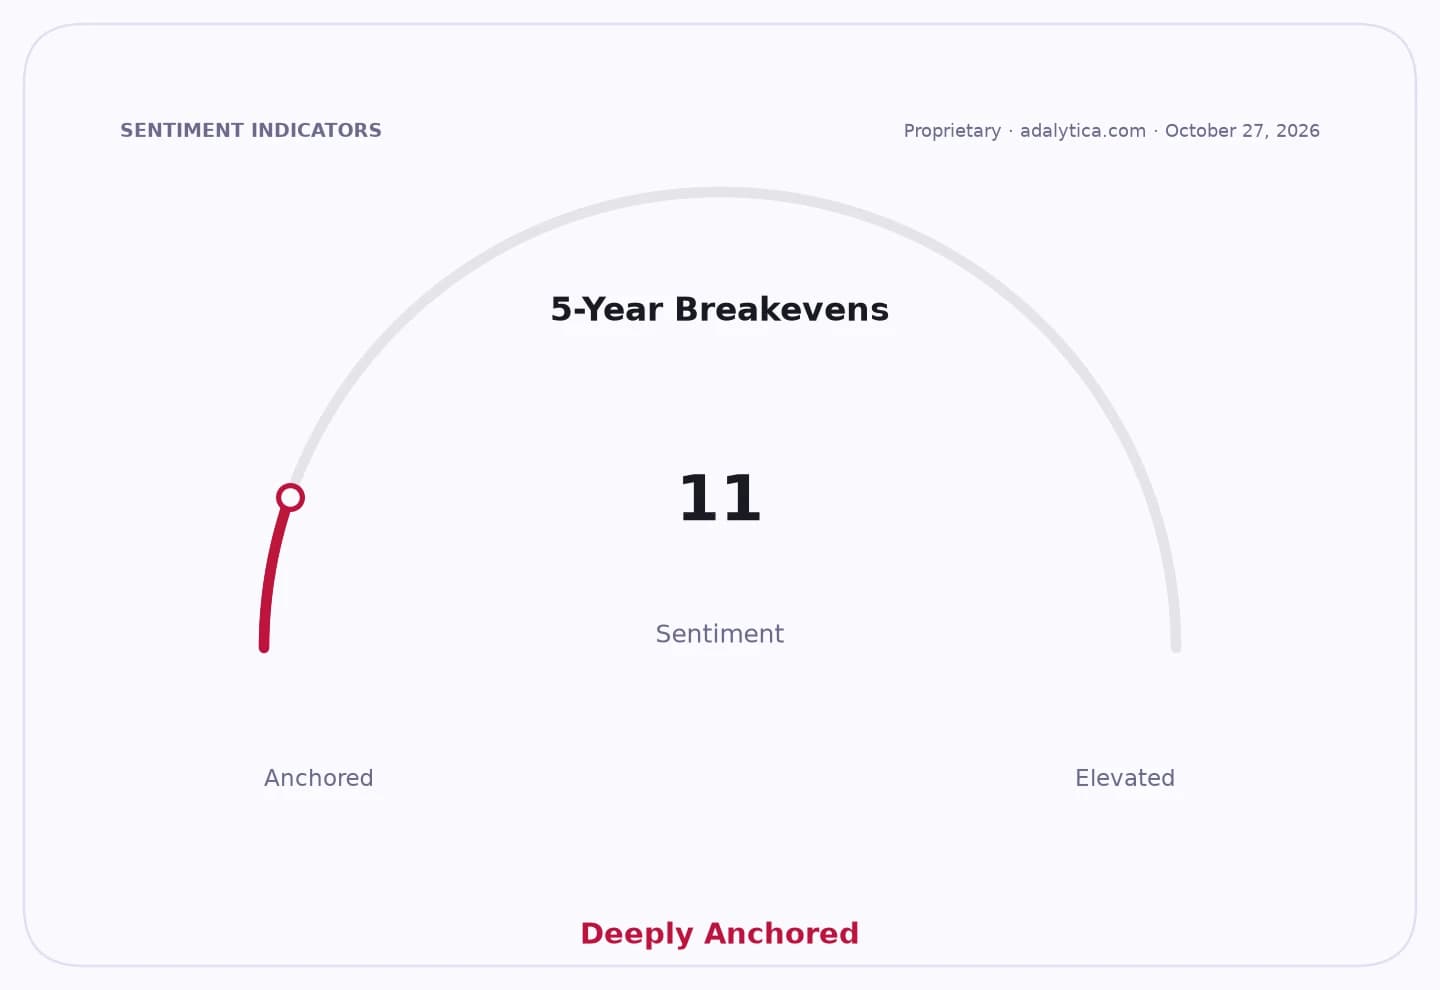
Sentiment Indicators
The report says the two countries delivered broadly similar inflation outcomes over the past five years, but very different outcomes for employment and wages. Australia has kept unemployment about a percentage point lower, preserved gains in full-time hiring and avoided the kind of broad labour-market deterioration seen across the Tasman. New Zealand, by contrast, has seen job numbers fall, unemployment and underutilisation rise, and real wages deteriorate sharply. That divergence is exactly what long-term investors should care about, because labour-market strength supports household demand, tax receipts and corporate earnings.
The political and policy split is just as important. In New Zealand, the report points to public spending cuts, cancelled infrastructure projects and weaker workplace protections as part of a tightening stance that helped push the economy into recession in 2024. Australia took the opposite route, backing public services and preserving employment conditions through reforms that supported wages. One country tried to squeeze inflation down quickly. The other accepted that inflation would cool gradually while keeping more people in work. The result, according to the unions, is that Australia protected its growth base while New Zealand paid a bigger economic price.
That distinction has real market implications. A labour market that holds up better tends to support bank credit quality, consumer spending and earnings in domestic-facing sectors such as retail, housing and services. It also reduces the odds of a deeper downturn that forces central banks into sharper policy reversals. New Zealand’s weaker employment backdrop, by contrast, raises the risk of more caution from households and more pressure on rate-sensitive businesses. Even where inflation outcomes are similar, the path to get there matters for valuations and for the sustainability of demand.
The report also underscores a broader point investors often miss: inflation is not always a simple test of monetary toughness. Sandra Grey of the New Zealand Council of Trade Unions said the recent pickup in inflation in both countries has been driven by higher fuel and energy costs tied to global geopolitics, not just domestic wage pressure. If that is true, then aggressive domestic austerity delivers fewer inflation gains than politicians promise, while imposing a larger hit on jobs and incomes. Melissa Donnelly of the ACTU said Australia’s experience shows governments can support workers without losing control of inflation when the shock is largely external.
For investors, the long game is straightforward. Economies that preserve employment through volatile inflation tend to emerge with stronger consumption, less social strain and better odds of steady corporate growth. Economies that rely too heavily on job destruction to cool prices may win a shorter inflation battle, but they can weaken the very demand base that drives compounding over time. New Zealand’s next policy turn will tell markets whether it wants to keep prioritising disinflation at any cost or pivot back toward growth and labour stability. Either way, Australia’s experience is a reminder that protecting jobs is not just a social choice — it can be a superior investing backdrop.
| Entity | Gains | Losses |
|---|---|---|
| Australian workers | ▲More jobs, stronger wages | ▼Less pressure on employment |
| New Zealand workers | ▲None | ▼Higher unemployment, weaker real wages |
| Australian economy | ▲Stronger demand, lower recession risk | ▼Slower disinflation at times |
| New Zealand policymakers | ▲None | ▼Credibility on growth and jobs |