Bank of America is committing $100 million in deposits to minority depository institutions, a move that matters less for the headline amount than for the signaling effect in a banking system under pressure to prove it can still widen access to credit and basic financial services.
Bank of America Commits $100 Million to Minority Banks
The bank’s pledge is aimed at strengthening institutions that serve underserved communities, a segment that has long struggled with scale, funding costs and deposit stability. In practice, the deposits give minority lenders more balance-sheet flexibility, helping them extend loans, manage liquidity and compete for customers in neighborhoods where larger banks often have the advantage in technology, brand and funding access.
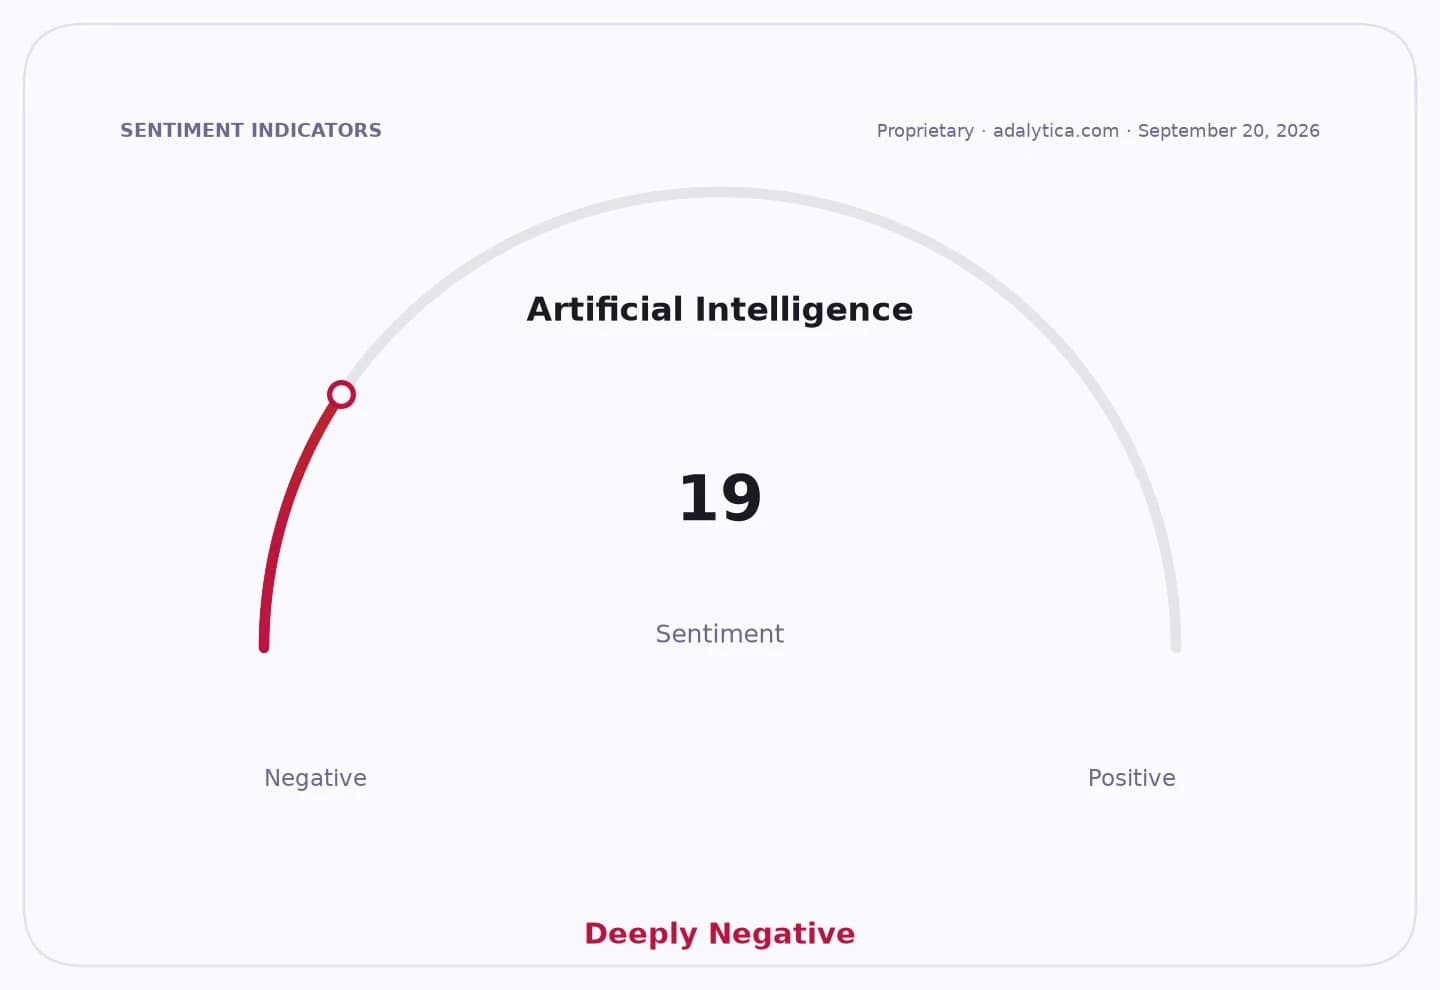
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For Bank of America, the step fits a broader strategy of using its deposit base — one of the industry’s most valuable funding franchises — to support community finance without materially straining capital. The company reported average deposits of roughly $651.9 billion in the latest quarter, underscoring how small a fraction of its overall funding base this initiative represents. That scale also makes the move inexpensive relative to the reputational and policy benefits it can deliver.
The initiative also lands at a time when investors are closely watching whether large banks can maintain deposit growth while absorbing slower loan demand, higher funding costs and tougher scrutiny over how they deploy capital. BAC shares recently traded below their 50-day moving average and have been volatile, reflecting a market that has been more focused on margin pressure and rate expectations than on social-impact initiatives. Still, programs like this can help banks deepen relationships with regulators, local communities and commercial clients, particularly when policy makers are pushing for broader access to financial services.
The economic case is straightforward: minority depository institutions tend to recycle capital locally, and even modest balance-sheet support can have a multiplier effect in underserved areas. That matters in lower-income communities, where access to deposit funding can determine whether small businesses get working capital, mortgages are approved and community lenders can absorb shocks.
For investors, the key question is not whether the $100 million is large enough to move Bank of America’s earnings — it is not — but whether the bank can continue to generate stable, low-cost deposits while demonstrating that it can meet social and regulatory expectations without compromising returns. Bulls will see a disciplined use of excess liquidity and a low-cost way to reinforce customer loyalty. Bears may view it as immaterial to near-term fundamentals, especially if loan growth remains subdued and funding competition tightens.
The broader narrative is that the largest U.S. banks are being asked to do more with their balance sheets than simply maximize spread income. Bank of America’s deposit commitment shows how financial giants can use their scale to support smaller lenders, while also reinforcing their own standing in a market where reputation, funding depth and regulatory goodwill remain strategic assets.
| Entity | Gains | Losses |
|---|---|---|
| Minority depository institutions | ▲Lower-cost funding | ▼Funding constraints ease |
| Underserved communities | ▲More local lending capacity | ▼Limited access narrows |
| Bank of America | ▲Reputation and deposit stewardship | ▼Some liquidity flexibility |
| Shareholders focused on returns | ▲Long-term franchise value | ▼No near-term earnings lift |