The Bank of England is poised to lift borrowing costs on Thursday, a move that would extend the global tightening cycle as surging energy prices push UK inflation higher and threaten to squeeze households heading into the winter.
Bank of England set to raise rates to 4%
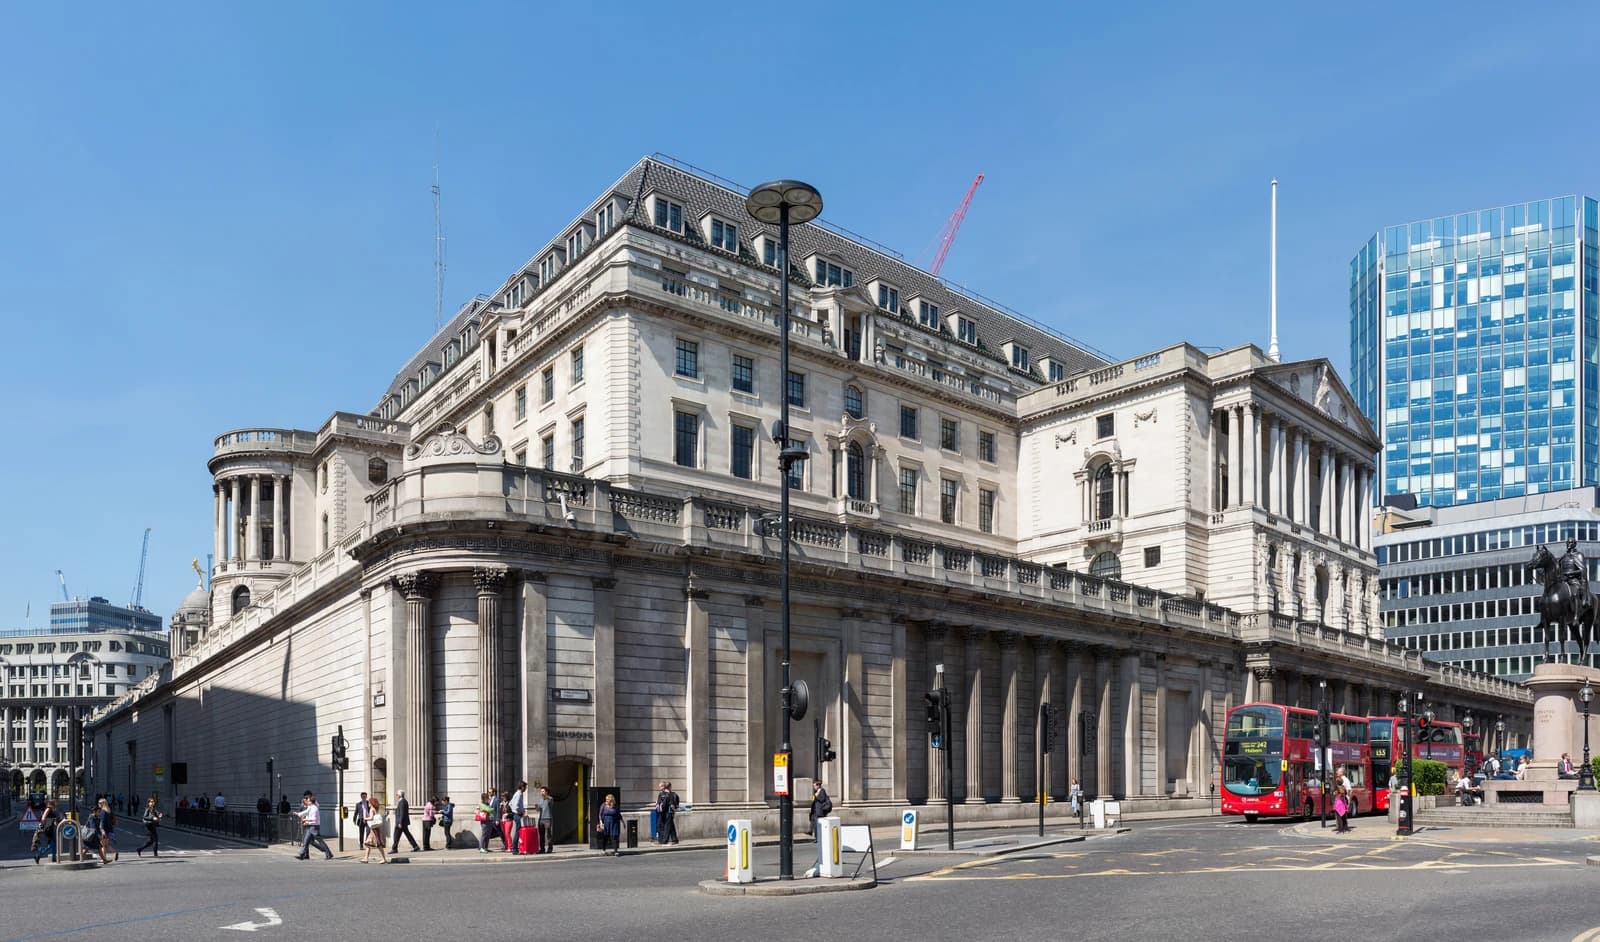
The Monetary Policy Committee is forecast to raise the benchmark rate by a quarter point to 4.0%, the first increase in more than three years and a sign the BoE is catching up with the Federal Reserve and European Central Bank after lagging their response to the inflation shock. The decision would take the Bank’s rate to its highest level since August 2023 and leave policymakers balancing an inflation problem driven by fuel costs against signs that growth could weaken further ahead.
Sentiment Indicators
Britain’s annual inflation rate accelerated to 3.5% in September, faster than expected, as fuel prices jumped. Economists now see inflation moving close to 4% early next year as millions of households face higher energy bills, even after government support in last week’s budget softened the blow.
For investors, the immediate focus is whether the BoE signals that Thursday’s move is the start of a broader tightening cycle or a one-off response to imported inflation. Higher rates typically support sterling and punish rate-sensitive sectors such as housing and consumer discretionary shares, while banks can benefit from wider net interest margins if loan demand holds up.
The pound has already firmed against the euro as traders price in a more hawkish BoE relative to the ECB, while UK equity exposure has been more measured. The iShares MSCI United Kingdom ETF, EWU, has eased from a recent high, even as the broader market remains sensitive to rate expectations.
The central bank will also publish updated growth and inflation forecasts, which are likely to show stronger near-term price pressure but a softer outlook later if energy costs keep draining consumer spending. The key risk for markets is that inflation remains sticky enough to force more than one hike, even as households and businesses absorb another hit to real incomes.
| Entity | Gains | Losses |
|---|---|---|
| Banks | ▲Wider lending margins | ▼Higher credit risk |
| Pound sterling | ▲Rate-supportive flows | ▼Exporters’ competitiveness |
| UK households | ▲None | ▼Higher mortgage and bill costs |
| UK retailers/housing stocks | ▲None | ▼Demand pressure from tighter policy |