Basra crude weakened even as benchmark Brent and West Texas Intermediate advanced, underscoring a widening split in the oil market that is reshaping pricing for Middle East grades and the traders who move them.
Basra Crude Lags Brent and WTI as Spreads Widen
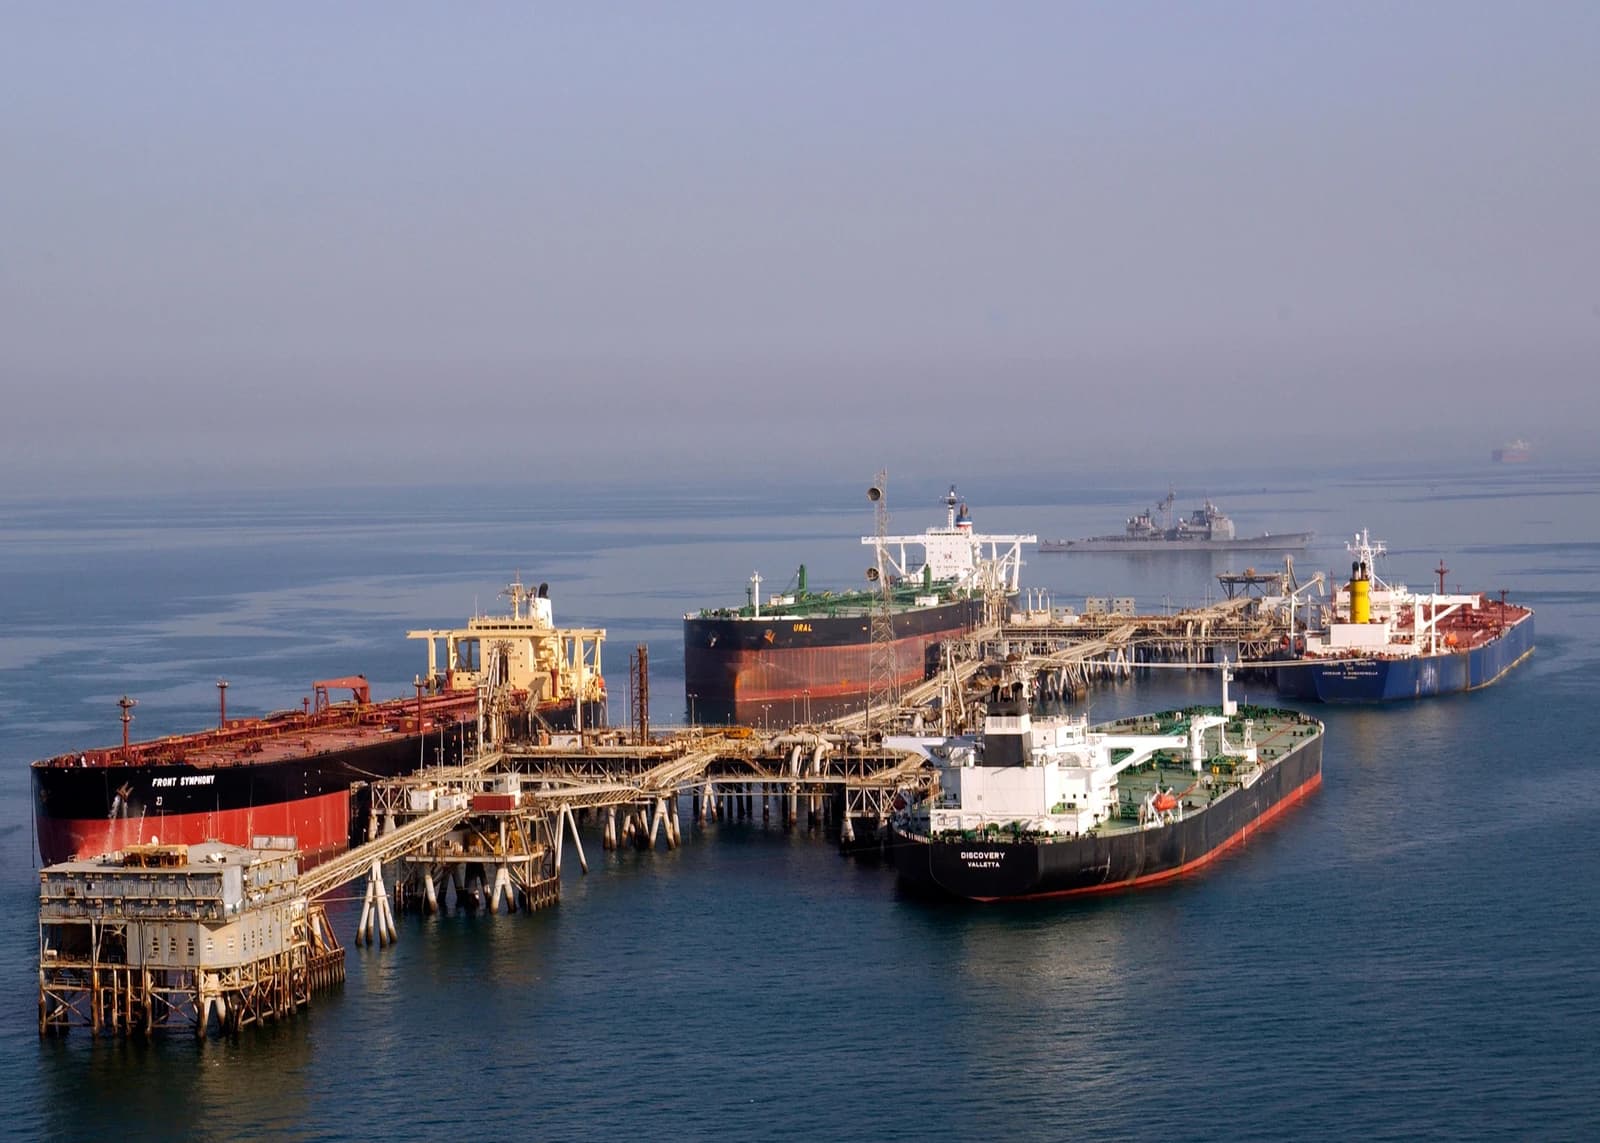
The divergence matters because Basra is priced off the global benchmarks, yet it is also heavily influenced by regional supply-demand balances, freight economics and refinery appetite. When Brent and WTI firm while Basra eases, the spread can squeeze producers and Middle Eastern exporters while improving economics for refiners and buyers of cheaper sour crude. For investors, the move highlights that not all oil grades participate equally in a rally: paper benchmarks can rise while physical differentials soften, changing the margins for producers, refiners and trading desks.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Recent trading in oil-linked funds shows the broader market remains firm but volatile. The USO ETF, which tracks front-month West Texas Intermediate exposure, closed at 143.91 on Oct. 7, down from 161.86 on Sept. 15 but still far above its moving averages, with the 50-day average at 138.38 and the 200-day at 116.33. That suggests crude prices remain elevated by historical standards even after a pullback. Technical readings also point to a cooling but still constructive trend: USO’s RSI was 38.1 on Oct. 7, while the MACD remained positive, indicating the market has eased from overheated conditions without fully reversing.
Adalytica’s Oil WTI Trade Signals snapshot shows sentiment on WTI at 32, labeled neutral, while awareness sits at 73, or greed, implying traders remain alert to upside risks even as the immediate tone is less euphoric. By contrast, the Global Stability Sentiment gauge was at 100, labeled extreme greed, with awareness at just 7, a combination that points to persistent geopolitical anxiety in the background. That matters for crude because Middle East grades such as Basra are especially sensitive to shipping routes, regional supply security and refinery demand for sour barrels.
The market narrative is straightforward: benchmark crude is being supported by a risk premium, but physical differentials are moving on their own track. If Brent and WTI keep rising while Basra lags, upstream producers may see weaker realizations even in a stronger headline market, while refiners with access to discounted barrels could see margin relief. Traders will be watching whether the spread is a temporary pricing dislocation or the start of a more durable rerating in the sour-crude complex, especially if geopolitics keeps the global benchmark bid but regional trade flows remain uneven.
| Entity | Gains | Losses |
|---|---|---|
| Brent/WTI buyers | ▲Maintain benchmark strength | ▼Pay higher headline prices |
| Basra crude buyers | ▲Get cheaper sour barrels | ▼Face weaker supply confidence |
| Basra producers/exporters | ▲— | ▼Lower realized selling prices |
| Refiners | ▲Better feedstock margins | ▼Lose if benchmark rally tightens costs |