BlueScope Steel is guiding to stronger full-year earnings after positive updates from its US and Australian businesses, a sign the steelmaker is finding support even as inflation and interest rates remain the market’s central worry.
BlueScope Steel Raises Full-Year Earnings Outlook
For investors, that matters because BlueScope sits at the intersection of two of the biggest forces shaping industrial earnings right now: cost inflation and demand resilience. When rates stay restrictive and prices are still sticky, the market usually expects cyclical manufacturers to soften. Instead, BlueScope is pointing to better operating momentum in the two markets that matter most to its profit pool, suggesting margins may be holding up better than feared.
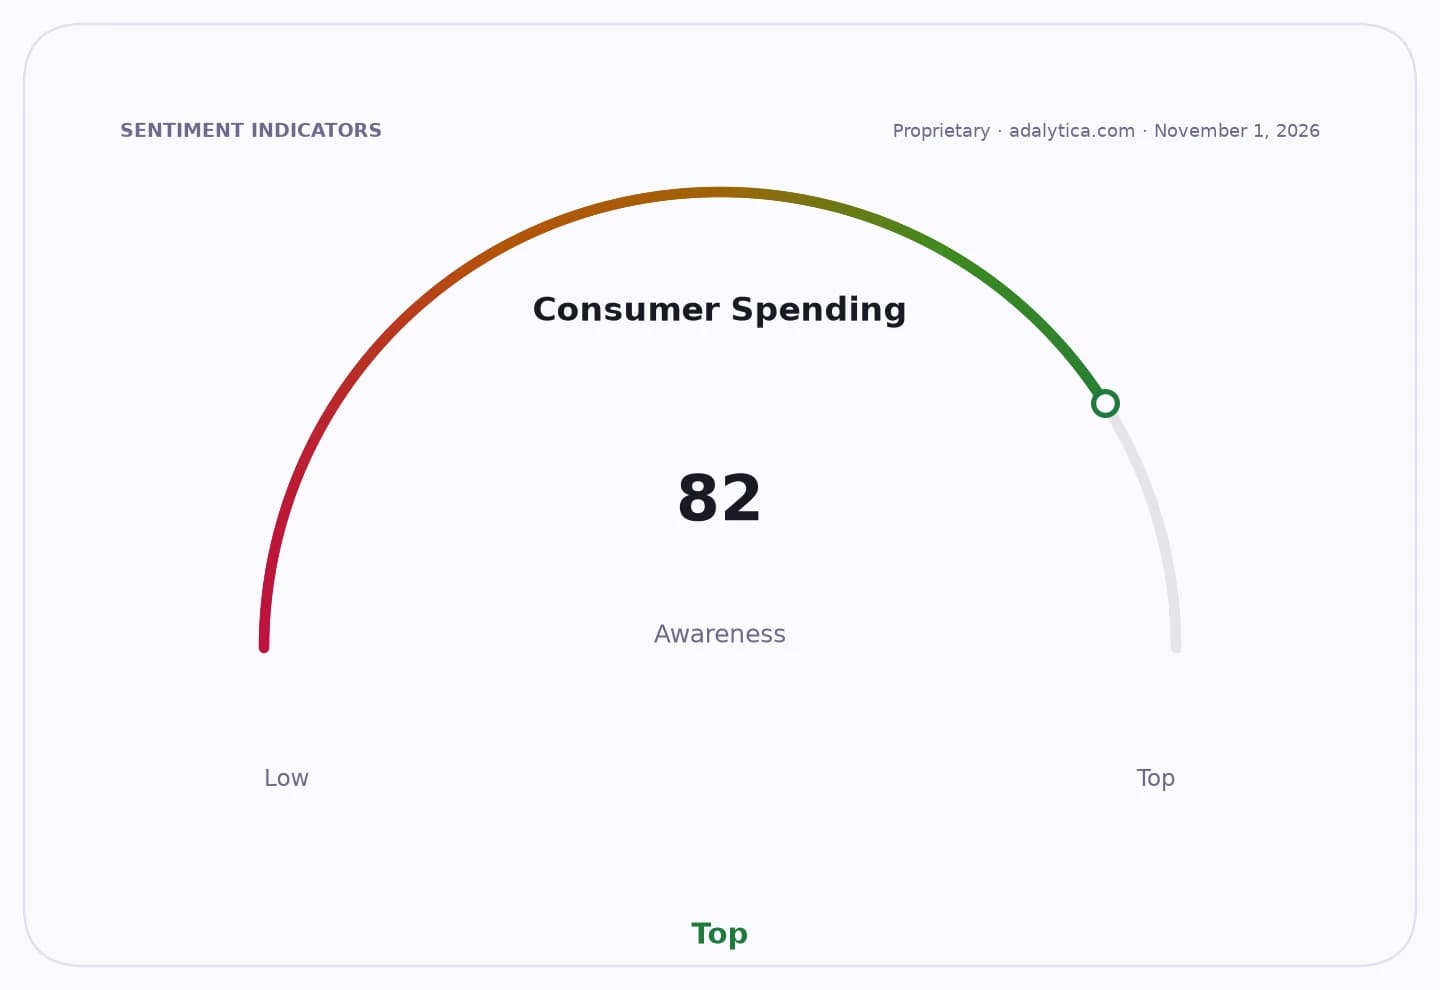
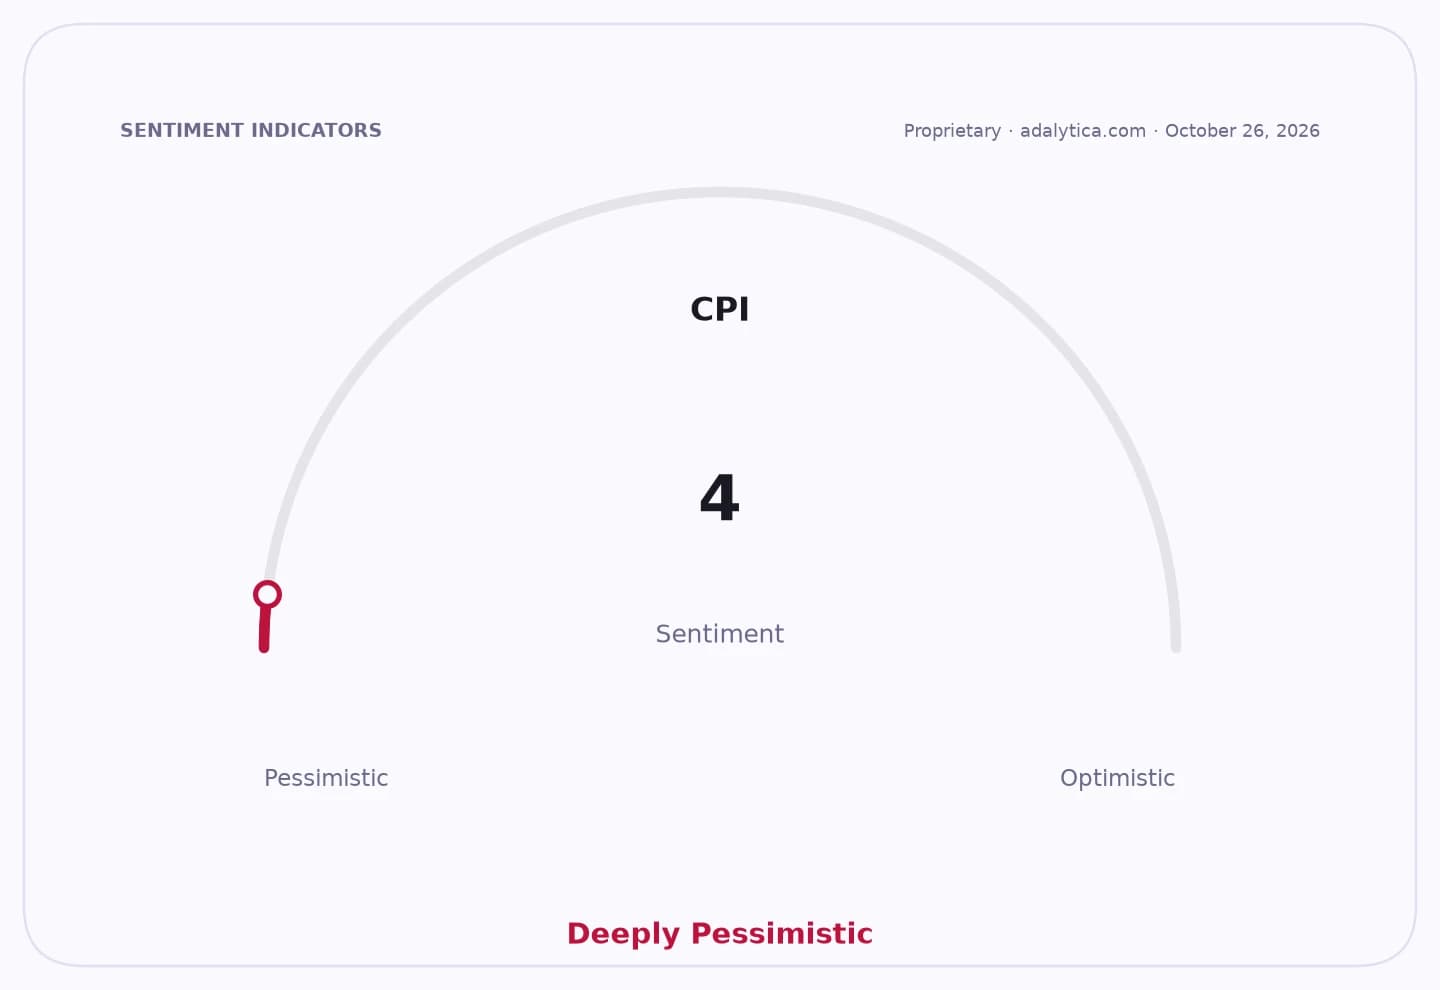
Sentiment Indicators
That is not a trivial shift. The Federal Reserve’s policy rate is still around 3.75%, according to the latest data, with 10-year Treasury yields near 5%, a level that keeps financing conditions tight and limits the scope for an easy cyclical rebound. Inflation is still running hot enough to stay in focus, with the US CPI up to 336.298 in September from 332.813 in July. In that setting, a better earnings guide from a steel producer implies real operating leverage, not just a macro tailwind.
BlueScope shares have already responded sharply. The stock closed at A$33.29 on October 30, up from A$19.93 late last year, and sits well above both its 50-day and 200-day moving averages. The move has also pushed the RSI into overbought territory, which suggests momentum is strong, though it also means the market has started to price in a more constructive earnings backdrop.
The broader read-through extends beyond BlueScope. Steel is a classic bellwether for industrial demand, construction activity and capex appetite. If BlueScope can lift guidance while US and Australian operations improve, that argues for better pricing discipline and firmer end-market demand than many investors have been modeling. It also fits with what is happening across the US steel group: Nucor has seen its own shares move higher this year, even as management has flagged margin pressure from higher input costs.
The real investment takeaway is that the market may still be underestimating the durability of industrial earnings in a high-rate world. BlueScope’s update suggests the winners are likely to be the companies with pricing power, regional diversification and exposure to infrastructure and replacement demand rather than pure commodity volume plays. I believe investors should keep BlueScope, and the broader steel and materials complex, on watch for further guidance upgrades if inflation stays sticky and rates fall only slowly.
| Entity | Gains | Losses |
|---|---|---|
| BlueScope | ▲Higher earnings outlook | ▼Short sellers |
| US, Australia operations | ▲Better margins | ▼Cost pressure |
| Steel bulls | ▲Guidance upside | ▼Recession bets |
| Rate-sensitive cyclicals | ▲— | ▼Tighter-for-longer rates |