Bougainville Copper’s shares are trading against a sharply stronger copper backdrop, but the company’s valuation still depends less on metal prices than on whether its flagship project can clear political, financing and execution hurdles.
Bougainville Copper Falls 3.94% as Copper Hits Six-Month Highs
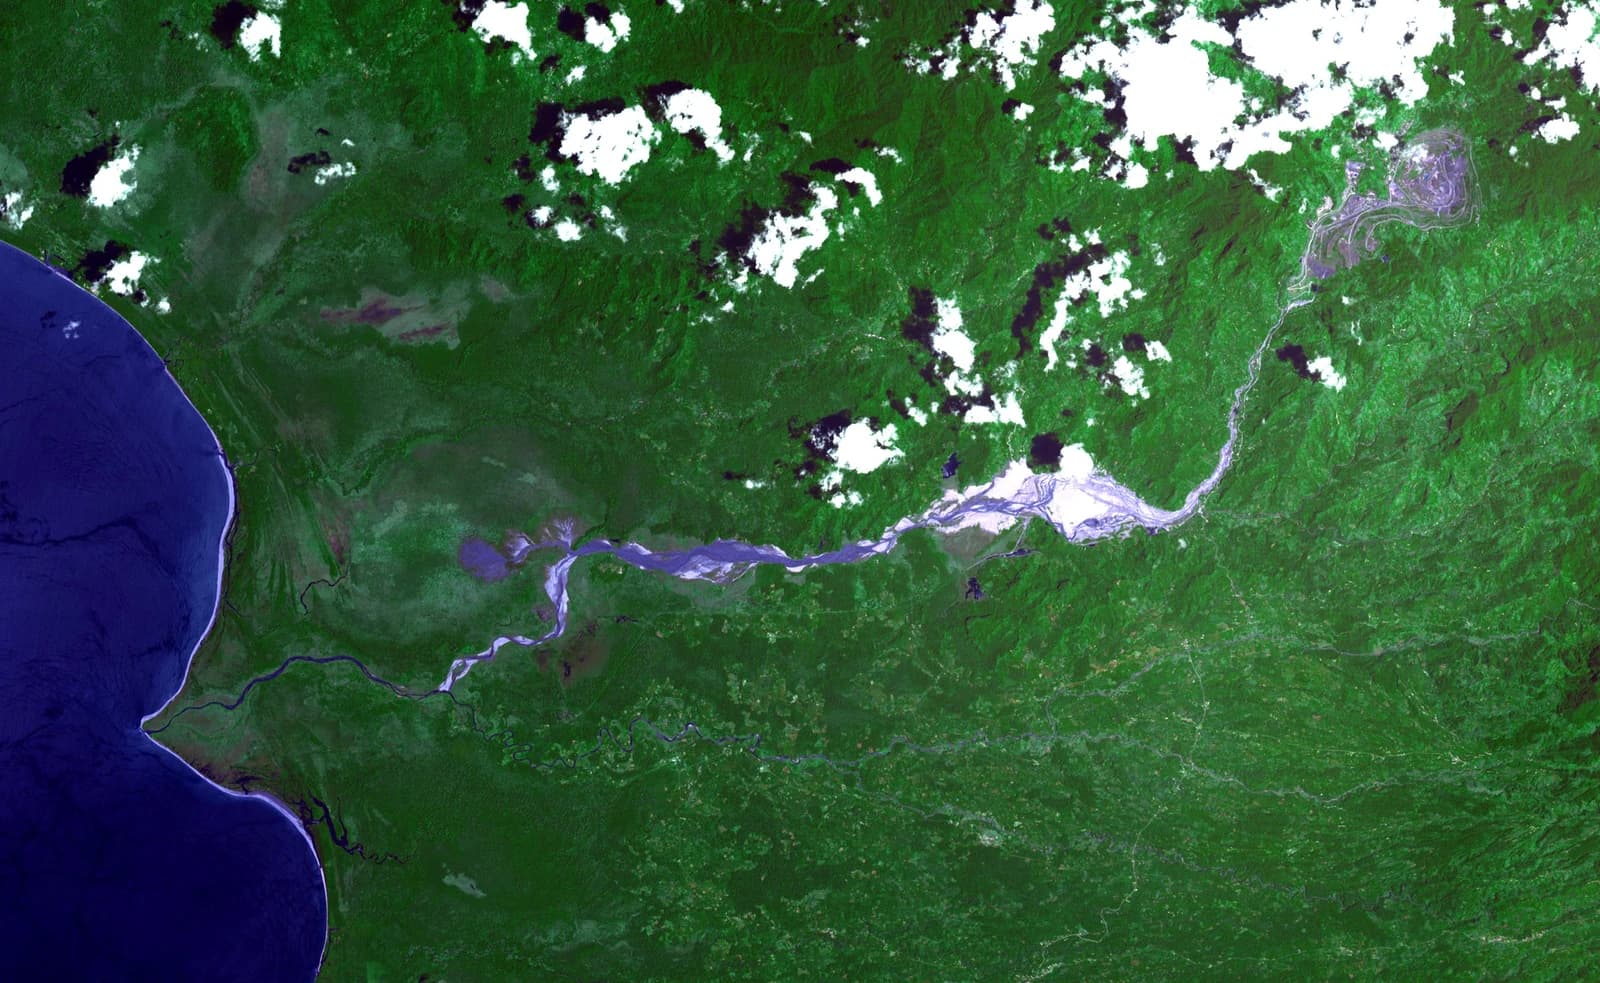
Copper has climbed toward six-month highs after the Democratic Republic of Congo restricted exports of copper and cobalt concentrates, tightening a market already supported by demand from power grids, electrification and artificial intelligence infrastructure. That has lifted sentiment across the copper complex and driven gains in major miners, with Southern Copper and Freeport-McMoRan both trading far above their autumn levels. Yet for Bougainville Copper, which fell 3.94% in the latest move, the key issue is not the commodity tape alone: it is whether the company can convert its resource exposure into a bankable development path.
Sentiment IndicatorsⓘProprietary · adalytica.com · August 9, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That distinction matters economically because Bougainville is essentially a long-duration option on a large copper asset in a jurisdiction with a difficult political history. Higher copper prices improve the economics of any future project by expanding margins and potentially reducing the hurdle for external funding, but they do not solve permitting, community consent or sovereign risk. In other words, the metal price can widen the prize, but it does not guarantee the project gets built.
Investors are therefore likely weighing two competing narratives. The bull case is straightforward: if copper stays elevated, the net present value of undeveloped deposits rises, strategic buyers become more interested and financing terms can improve. That has been visible elsewhere in the sector, where miners with operating leverage to copper have rallied as markets price tighter supply. The bear case is that Bougainville Copper remains a speculative story whose equity can be highly sensitive to headlines while the underlying asset still faces binary execution risk. In that scenario, the stock can underperform even when copper itself is strong.
The broader backdrop is also supportive for copper valuations generally. Supply disruptions in Africa, project delays elsewhere and resilient demand from energy transition and data-center buildout have tightened the market. Adalytica’s Gold Fear & Greed Index and S&P 500 trade signals both sit at extreme-greed levels, reinforcing a risk-on tone in commodities and equities, while the U.S. dollar has also shown strong trading momentum. But Bougainville’s shares will not be rerated purely by macro flows unless there is evidence of progress on the project itself.
For investors, the near-term question is whether the recent copper rally provides a better backdrop for strategic valuation and deal interest, or simply a more attractive exit window for holders of a high-risk name. Unless Bougainville Copper can show clearer milestones on development, ownership structure or financing, the stock is likely to trade more as a leveraged proxy for copper sentiment than as a fundamentals-driven miner.
| Entity | Gains | Losses |
|---|---|---|
| Copper price bulls | ▲Higher producer margins | ▼Consumers and fabricators |
| Bougainville Copper potential project value | ▲Stronger asset economics | ▼Discount for execution risk |
| Strategic miners / acquirers | ▲More attractive optionality | ▼Higher acquisition costs |
| Existing shareholders | ▲Upside from rerating | ▼Dilution and project delays |



