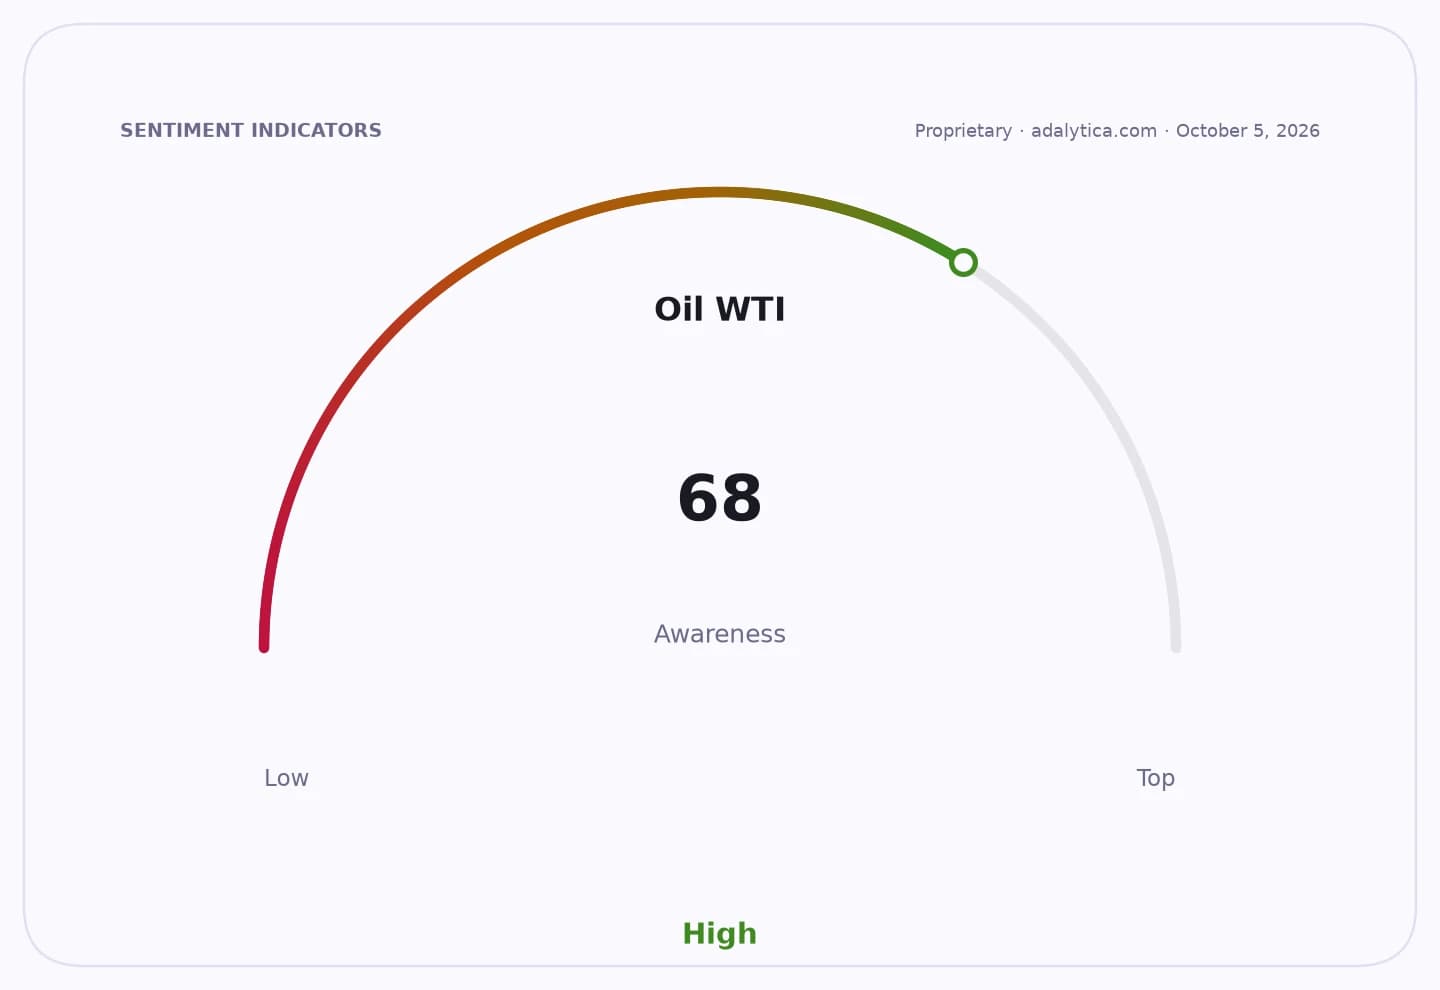
Brazil’s national oil and gas production passed 6 million barrels of oil equivalent a day for the first time in August, underscoring the country’s growing weight in global supply and supporting domestic cash flow for producers and the state.
Brazil oil output tops 6 million boed in August
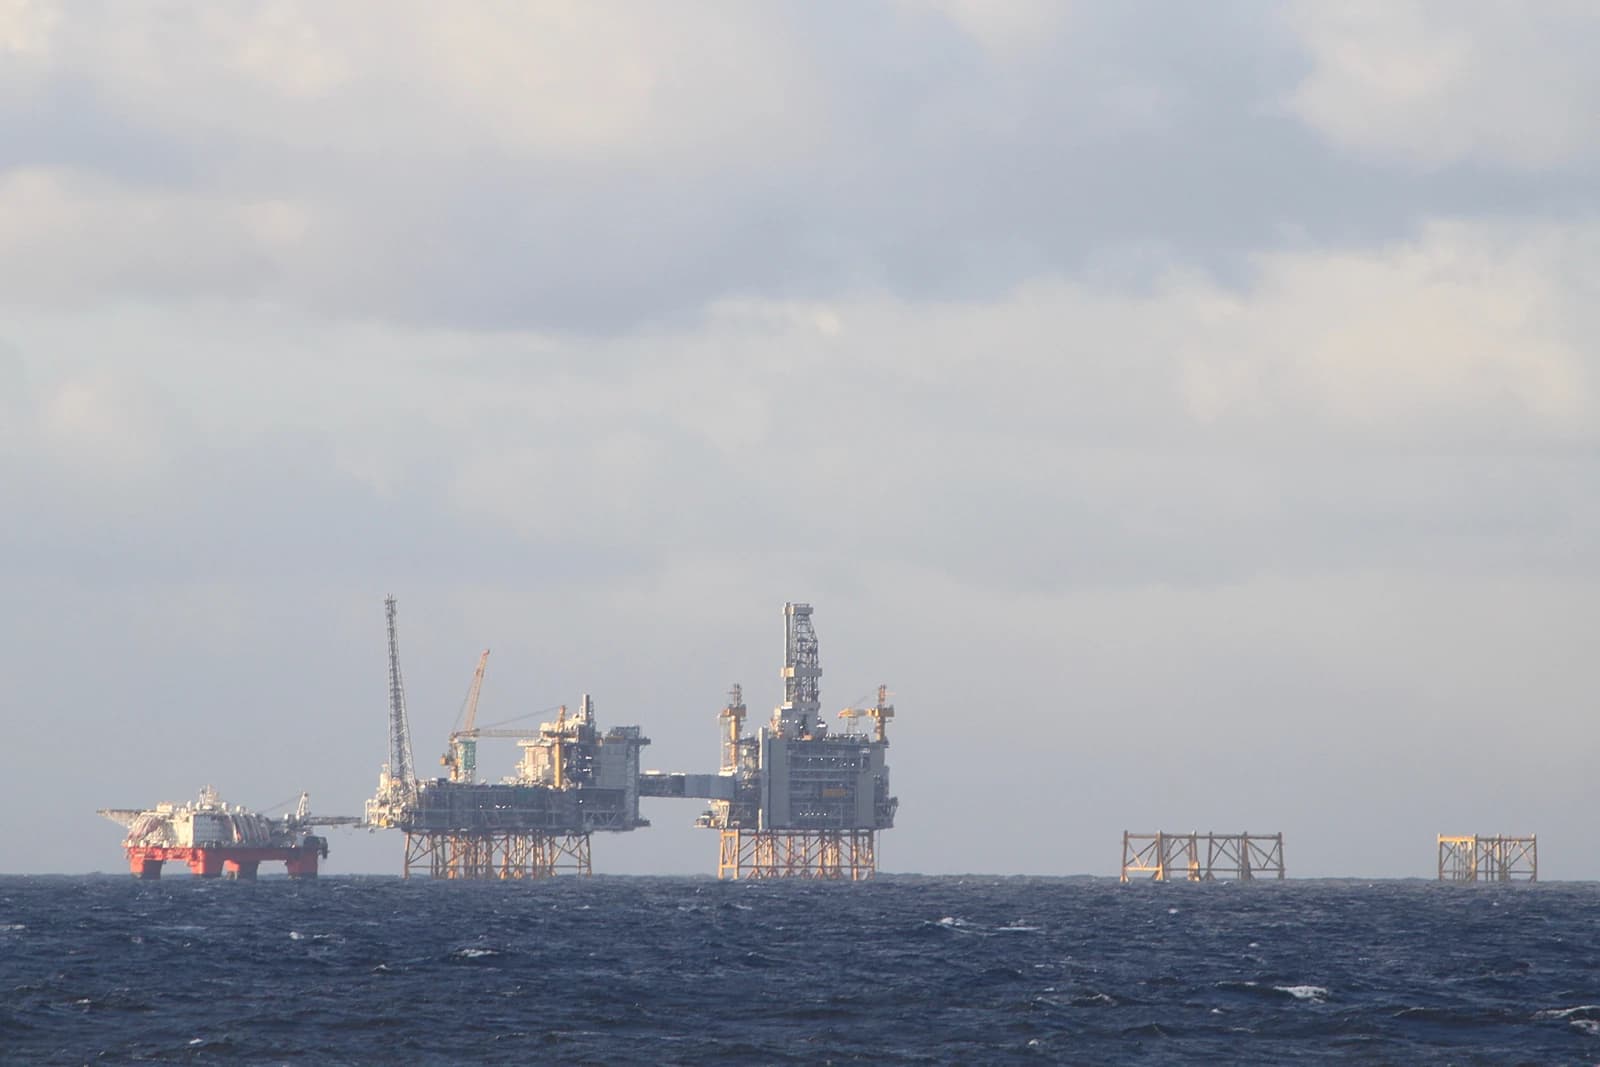
Preliminary data from regulator ANP show output rose 2.61% from July to 6.0 million boed, with crude production up to 4.613 million barrels a day and natural gas output rising to 220.5 million cubic meters a day. The pre-salt province accounted for 82.64% of total production, or 4.958 million boed, highlighting how Brazil’s offshore deepwater basins continue to dominate the national energy mix.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 1, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the milestone matters because Brazil is one of the few non-OPEC producers still delivering meaningful growth at a time when global supply remains vulnerable to geopolitical disruptions. Higher output can bolster export earnings, support Petrobras and other operators’ upstream revenue, and improve the country’s trade balance while helping offset swings in crude prices.
The data also reinforces the importance of pre-salt assets, which delivered 3.841 million barrels a day of oil and 177.5 million cubic meters a day of gas in August. That concentration of production in high-quality offshore fields tends to favor companies with exposure to Brazil’s deepwater basin and the services firms that support them, even as it leaves the broader market sensitive to maintenance, outages and drilling performance.
Oil prices have been volatile as traders weigh supply disruptions abroad and signs of resilient output elsewhere, with conventional indicators on crude still showing a market that has backed off recent highs but remains elevated. Brazil’s record production adds another layer of non-OPEC supply that could ease pressure on global balances if the increase proves sustained.
The next test is whether August marks a one-off surge or the start of a new plateau above 6 million boed, with investors watching monthly ANP figures, Petrobras operational updates and any changes to offshore project ramp-ups.
| Entity | Gains | Losses |
|---|---|---|
| Brazil upstream producers | ▲Higher output and export revenue | ▼Operational strain if outages rise |
| Petrobras and pre-salt operators | ▲Stronger volumes from core assets | ▼Less upside if crude weakens |
| Global oil buyers | ▲More non-OPEC supply | ▼Less pricing power for sellers |
| Oilfield service firms | ▲More offshore activity | ▼Margin pressure if activity slows |