Brazil’s Treasury is kicking off the first stage of its new debt-relief program with a potentially huge pool of old consumer and micro-entrepreneur loans, a move that could wipe out as much as R$90 billion in arrears and reset access to credit for millions of borrowers.
Brazil Treasury launches Novo Desenrola debt buyback
That matters because the government is not just offering another round of refinancing. Under Novo Desenrola, the state will buy delinquent loan portfolios from banks, funds and other lenders at steep discounts and pass the full discount on to the borrower. In practice, that means debts that have sat unpaid for years could be cleared at a fraction of face value, cleaning up balance sheets for lenders while giving households and MEIs a fresh start.
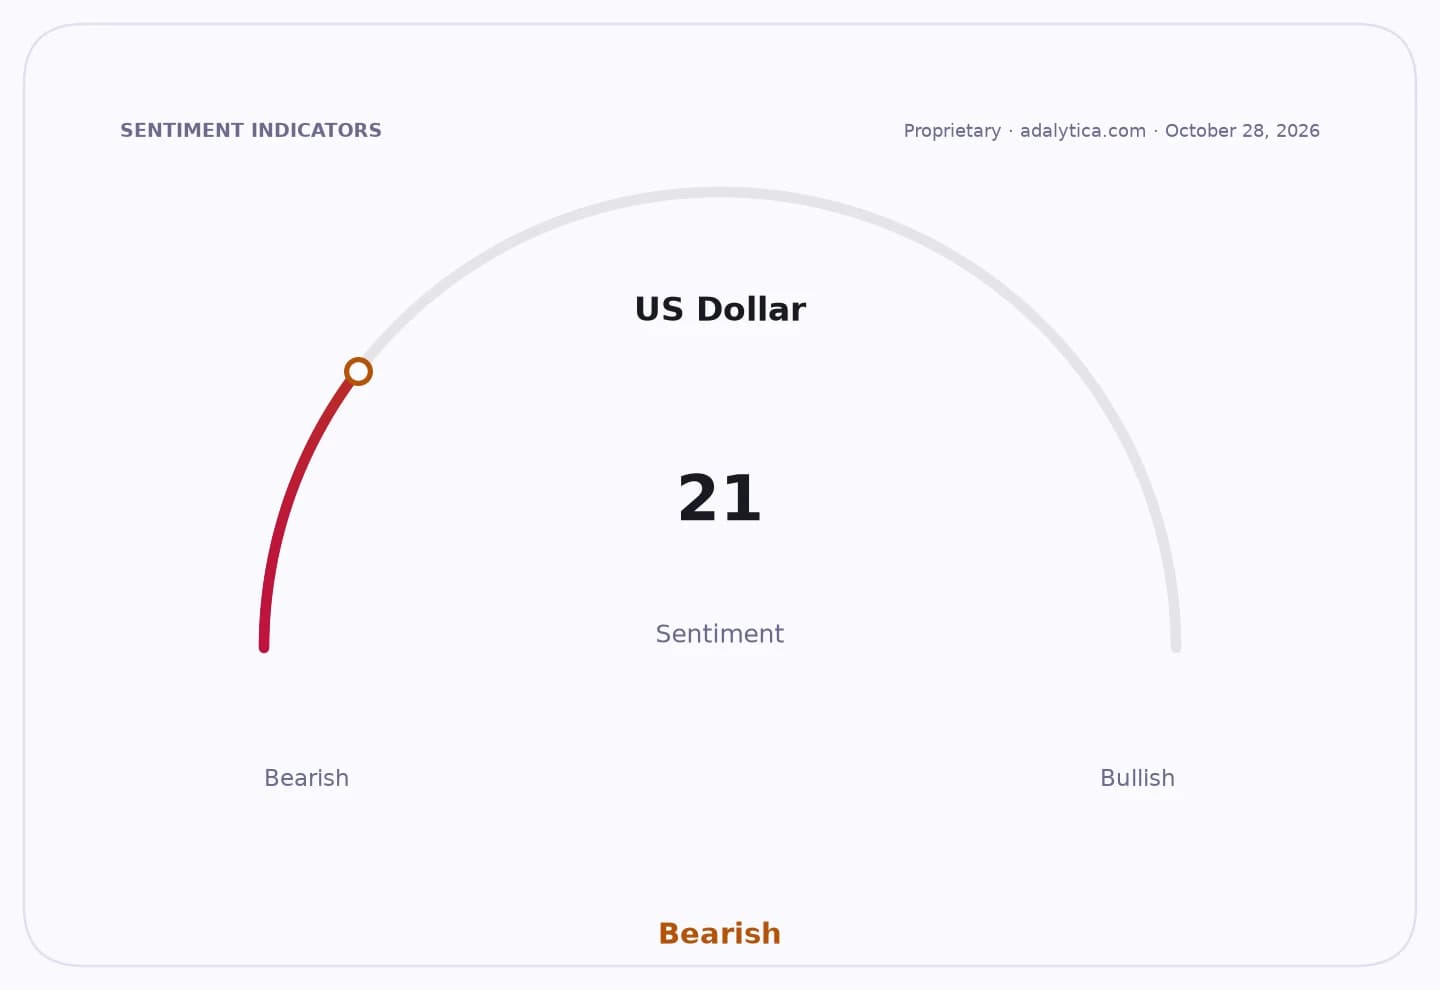
Sentiment Indicators
The Treasury said creditors will have five business days after the tender notice is published Thursday to submit portfolios of debts that are two to four and a half years past due. The initial estimate is that up to R$90 billion of eligible debt could be offered in this first call, according to Finance Ministry officials. If the government were to buy all of it, the cost would be capped at about R$9 billion under the program’s minimum 90% discount rule.
That price tag is manageable for the state, but the bigger economic effect could be on credit supply. By forcing lenders to bring forward old, hard-to-recover loans, the government can help banks and credit funds reduce legacy risk and free up room on their books. For borrowers, the appeal is obvious: debts up to R$10,000 can be included, and the public leilão could push discounts beyond 90%, potentially as high as 95% or more if the Treasury decides to demand deeper cuts.
For investors, the story is less about the direct fiscal outlay than about what it says about Brazil’s consumer-credit cycle. Programs like this can improve the quality of loan books across the financial system, especially for banks with exposure to lower-income borrowers and for FIDCs that specialize in receivables. They can also support retail spending over time if families and small entrepreneurs regain access to formal credit instead of staying trapped in delinquency.
The Treasury is also signaling that it intends to use the program aggressively, not symbolically. Officials said they may exclude portfolios that do not meet the right pricing or income mix, and the final auction could favor smaller borrowers if the supply of lower-income debt falls short. That makes this as much a credit-market operation as a social policy.
The political backdrop matters too. Novo Desenrola was launched just before Brazil’s runoff election, but Finance Ministry officials are now framing it as a long-term state policy rather than an electoral gesture. That should matter to investors watching for continuity: if the auction goes ahead in November or slips into early December, the bigger issue is whether this becomes a repeatable tool for clearing bad debt without destabilizing the banking system.
For long-term investors, the takeaway is straightforward: when governments start moving old debt off the system at scale, it can be a quiet positive for lenders, credit funds and eventually consumption. The auction is worth watching, but the real story is whether Brazil can turn a pile of stranded debt into healthier credit growth.
| Entity | Gains | Losses |
|---|---|---|
| Borrowers and MEIs | ▲Debt cleared at steep discounts | ▼Long-delinquent balance sheets |
| Banks and FIDCs | ▲Cleaner loan books | ▼Forced haircuts on old receivables |
| Brazilian Treasury | ▲Lower systemic credit drag | ▼Up to R$9 billion fiscal cost |
| Credit investors | ▲Better recovery visibility | ▼Reduced upside on distressed debt |