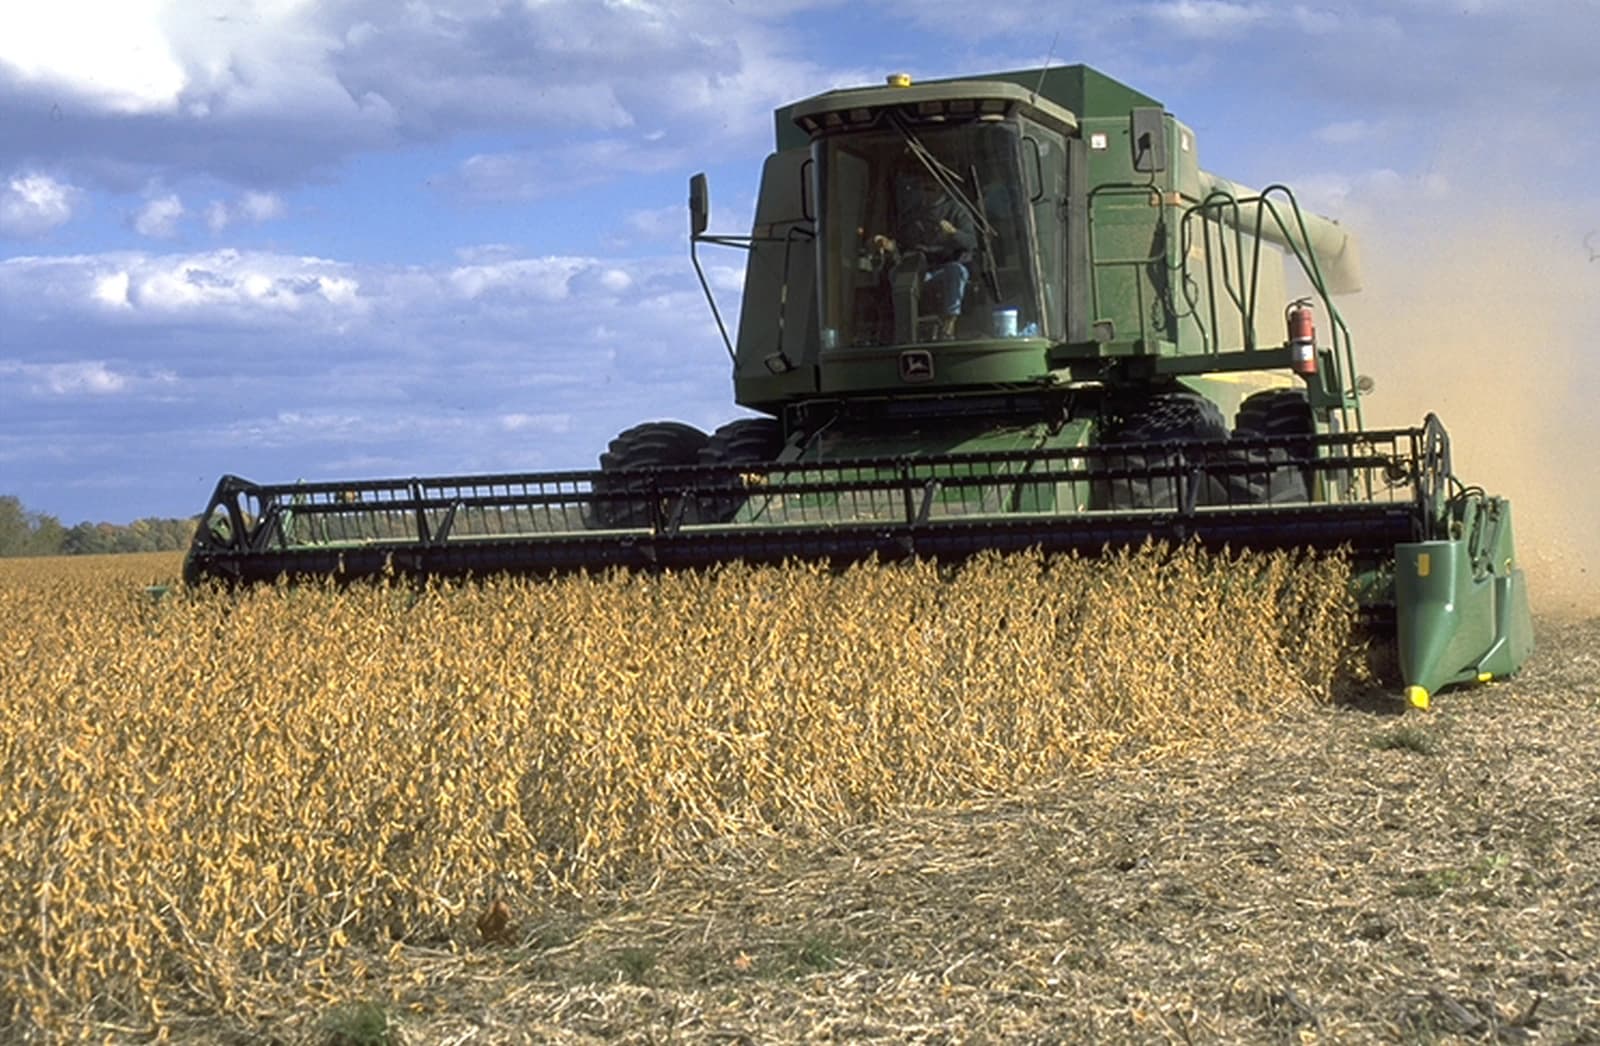
Wheat futures lead a broad CBOT pullback, with corn and soybeans also lower as traders weigh abundant world supplies, strong harvests in key exporting regions and soft momentum across the grain complex.
CBOT wheat corn soybeans fall on supply pressure
The move matters economically because lower grain prices can ease food and feed inflation, but they also pressure farm revenues and commodity-linked earnings for merchants, processors and exporters. It also reinforces a market that is increasingly focused on logistics, export competition and the pace at which surplus grain can actually reach buyers.
Sentiment Indicators
Corn
Chicago wheat was down 4 to 5 cents in early trade, with corn off 2 to 3 cents and soybeans lower by 1 to 4 cents, extending weakness in futures that have already been under pressure from fading weather risk and improving supply prospects. Corn futures near $17.40 a bushel remain well below their recent highs but are still above the 50-day and 200-day moving averages, while the Relative Strength Index has fallen to deeply oversold levels near 22, underscoring how fast the market has sold off. Soybeans at $25.57 are also sitting below both the 50-day and 200-day moving averages, with RSI near 14, a reading that points to a technically washed-out market even after the latest drop.
The bearish tone lines up with global grain headlines showing Kazakhstan exporting 2.26 million tonnes of new-harvest grain in the first two months after a record crop, while Turkey and Belarus are also reporting strong production. At the same time, Russian grain exports have slumped, but the loss of one supplier has not been enough to offset the wider supply picture, and Ukraine’s large harvest is still moving through transit channels rather than disappearing from the market.
For investors, the slide matters most for ag-trading houses, grain handlers and crop-linked funds. Archer-Daniels-Midland, Bunge and other commodity merchants tend to benefit from volatile flows and export dislocations, but sustained price weakness can squeeze margins tied to merchandising and processing spreads. Farmers, meanwhile, face softer cash prices just as planting and storage decisions are being made for the next marketing cycle.
Macro data also adds to the pressure. The latest U.S. producer price and core inflation forecasts point to only modest monthly gains, while the broader inflation backdrop remains contained enough to keep attention on the supply side of grains rather than on demand destruction. That leaves weather, export demand and Black Sea logistics as the next catalysts for wheat, corn and soybeans.
| Entity | Gains | Losses |
|---|---|---|
| Livestock feeders | ▲Cheaper feed costs | ▼Grain producers |
| Grain merchants | ▲Trading volatility, arbitrage | ▼Long-only grain holders |
| Food manufacturers | ▲Lower input prices | ▼Farm income |
| Exporters with surplus grain | ▲More competitive shipments | ▼Countries with bottlenecks |