China’s economic slowdown is leaving Xi Jinping with less leverage just as Beijing tries to project strength in trade talks with the United States and broader Asia-Pacific partners.
China Slowdown Weakens Xi's Trade Leverage
What matters most is not the optics of another Trump-Xi encounter, but the underlying balance of vulnerabilities. Trump still faces sticky inflation, high borrowing costs and political damage from Republican losses, yet China’s domestic economy has deteriorated from a modest recovery earlier this year into renewed deflationary weakness. That shift matters because it reduces Xi’s ability to rely on domestic demand, forcing Beijing to lean even harder on exports at a time when trade frictions are intensifying.
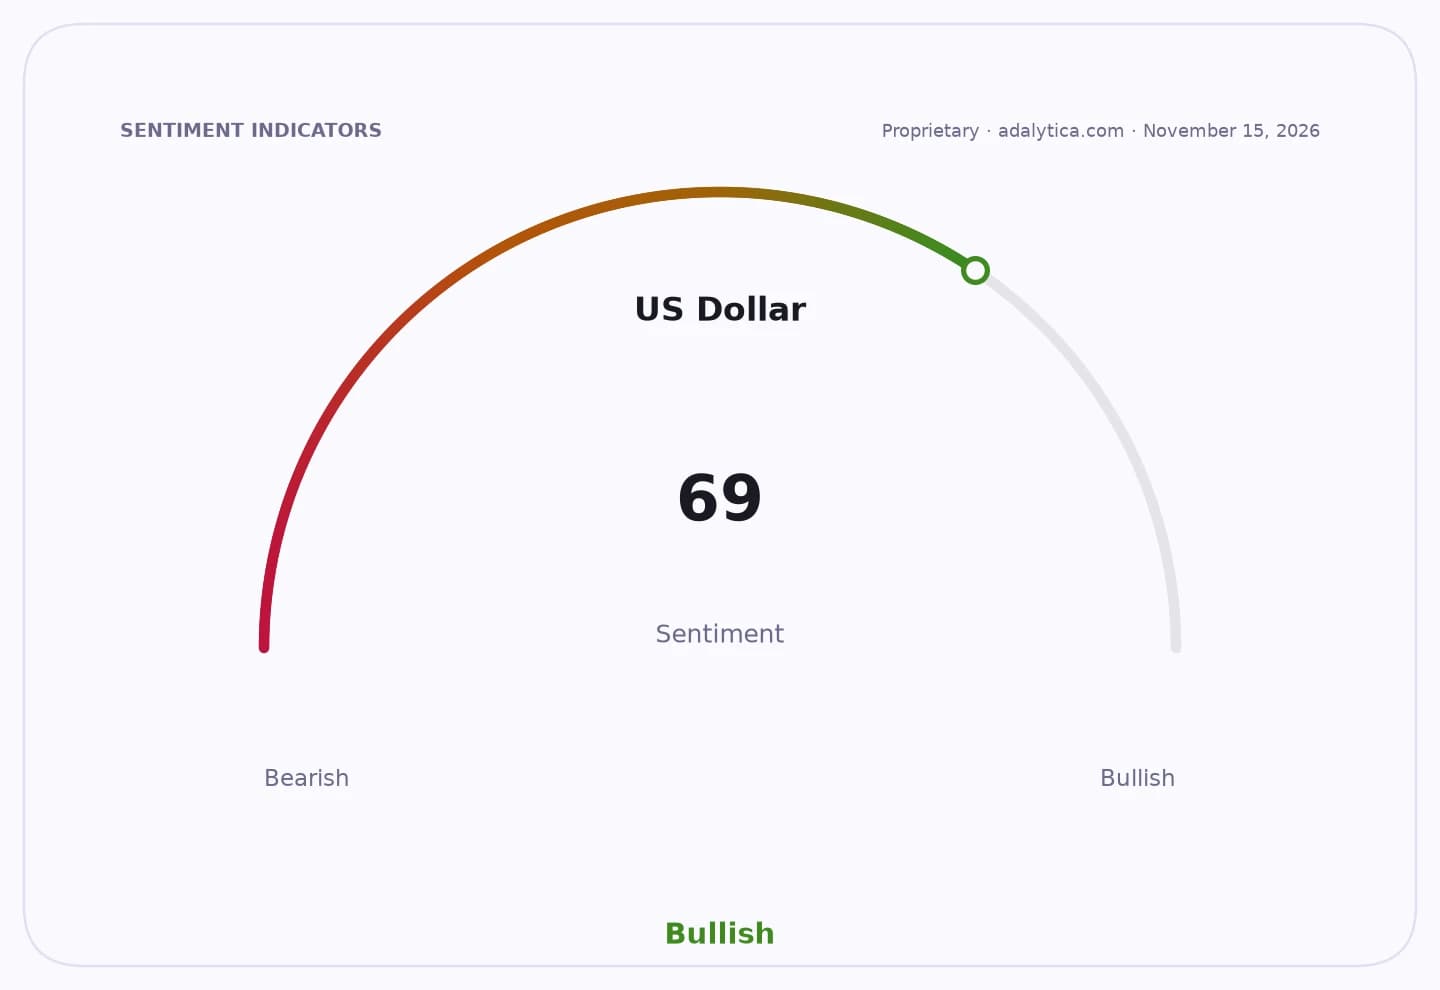
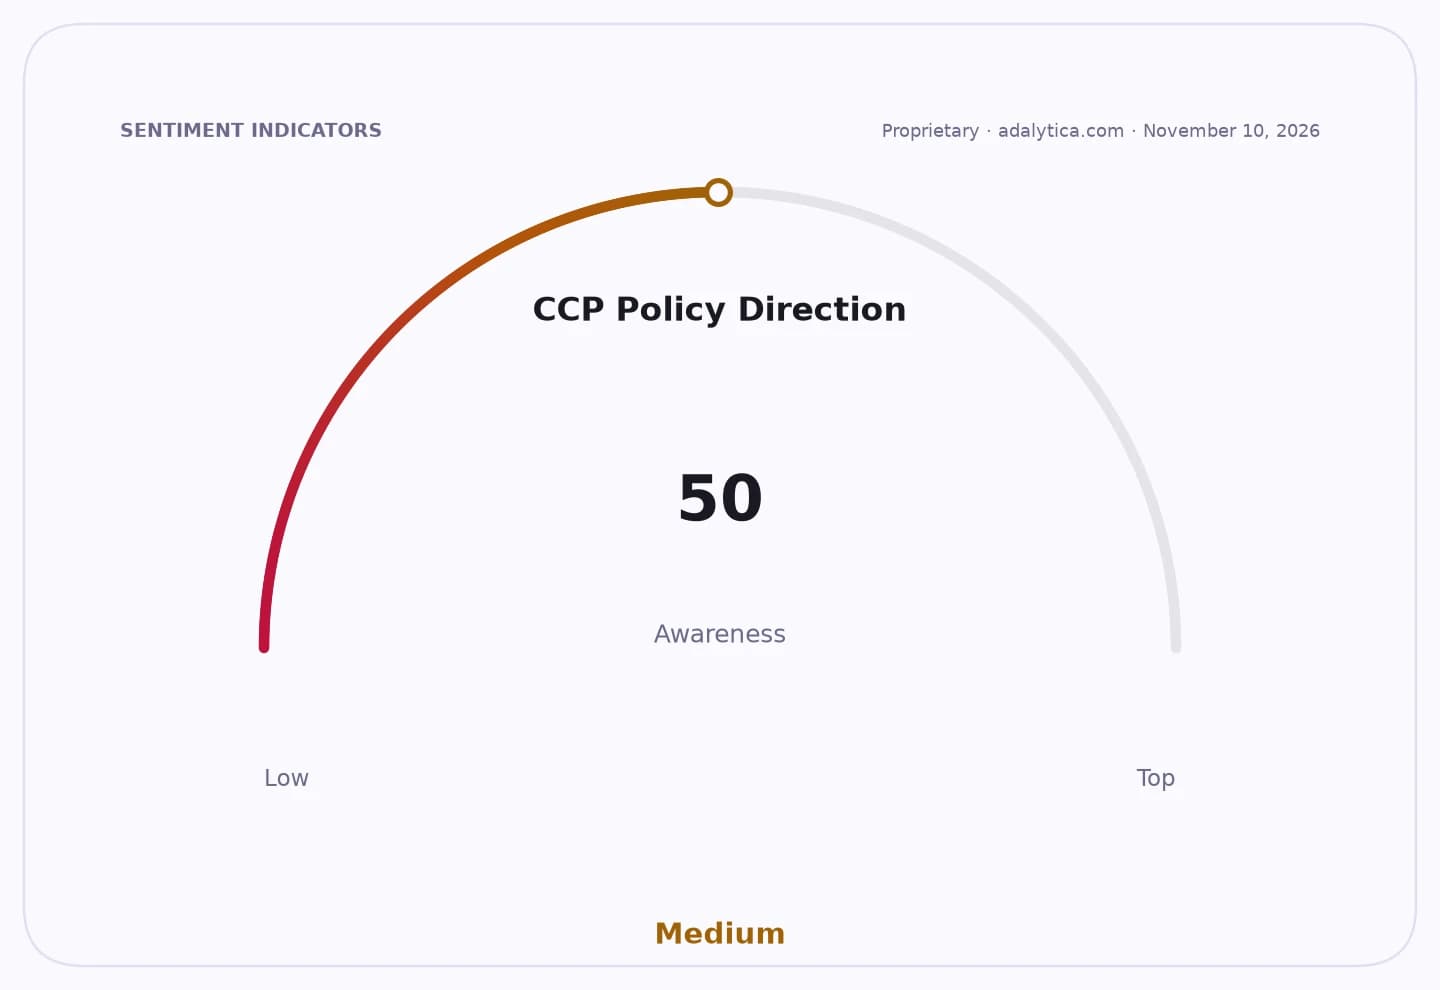
Sentiment Indicators
Six months ago, China looked as if it might be crawling out of the deflationary trap triggered by its property bust. Retail sales, industrial production and investment were improving, annual consumer inflation had picked up to a three-year high and the economic surprises index had climbed to its best level in three years. That rebound has faded. The latest figures show lending, spending and investment still weak, while fixed-asset investment is falling at the fastest pace since the pandemic, and, excluding that period, at the steepest rate in 30 years of comparable data.
The market evidence lines up with that deterioration. Chinese equities have fallen more than 20% since the summer, Hong Kong technology stocks are at a more than two-year low and the 10-year government bond yield has dropped to a record low, underscoring expectations of sluggish nominal growth and persistent disinflation. In FX and broader risk markets, that combination usually points to weak domestic demand rather than a temporary lull.
Exports remain the one clear offset. Record shipments of higher-value goods — from semiconductors and integrated circuits to converters and storage batteries — helped generate a trade surplus of more than $1 trillion last year, a figure China has already repeated this year. Analysts estimate net exports contributed about 2 percentage points to China’s 4.5% third-quarter growth rate, an unusually large share for an economy of China’s size. But that dependence is also a warning sign: if the AI investment boom cools, China loses one of the few engines compensating for its property and investment malaise.
That is why the AI cycle sits at the center of the geopolitical story. Both Washington and Beijing want to capture the upside of artificial intelligence, yet both are exposed if spending turns. In the U.S., an AI-led market correction would hit growth through wealth effects and capex pullbacks. In China, the risk is arguably greater because the rest of the economy is weaker. The Trump administration is already weighing new restrictions on US firms using Chinese AI models while tightening chip controls, suggesting the competition is becoming more, not less, economically consequential.
For investors, the implication is that China’s macro floor remains precarious. The bull case is that Beijing can still use trade surpluses, policy support and AI-linked manufacturing exports to stabilize growth. The bear case is that external demand is masking a deeper domestic slump, with deflation pressures, weak fixed investment and fragile sentiment limiting any durable rerating of Chinese assets.
That helps explain why Xi’s hand is weaker than it looked earlier in the year. Beijing can still point to export strength, but the economy underneath is not in a position to absorb much more shock. If AI spending stays hot, it can buy time. If it cools, China’s bargaining position — and its markets — look far more exposed.
| Entity | Gains | Losses |
|---|---|---|
| China exporters | ▲Stronger overseas sales | ▼Dependence on external demand |
| Beijing | ▲Short-term growth support | ▼Domestic weakness and deflation |
| US consumers/importers | ▲Potentially lower inflation | ▼Higher trade frictions if curbs tighten |
| Chinese equities | ▲Upside from AI/export boom | ▼Rerating risk from weak investment |