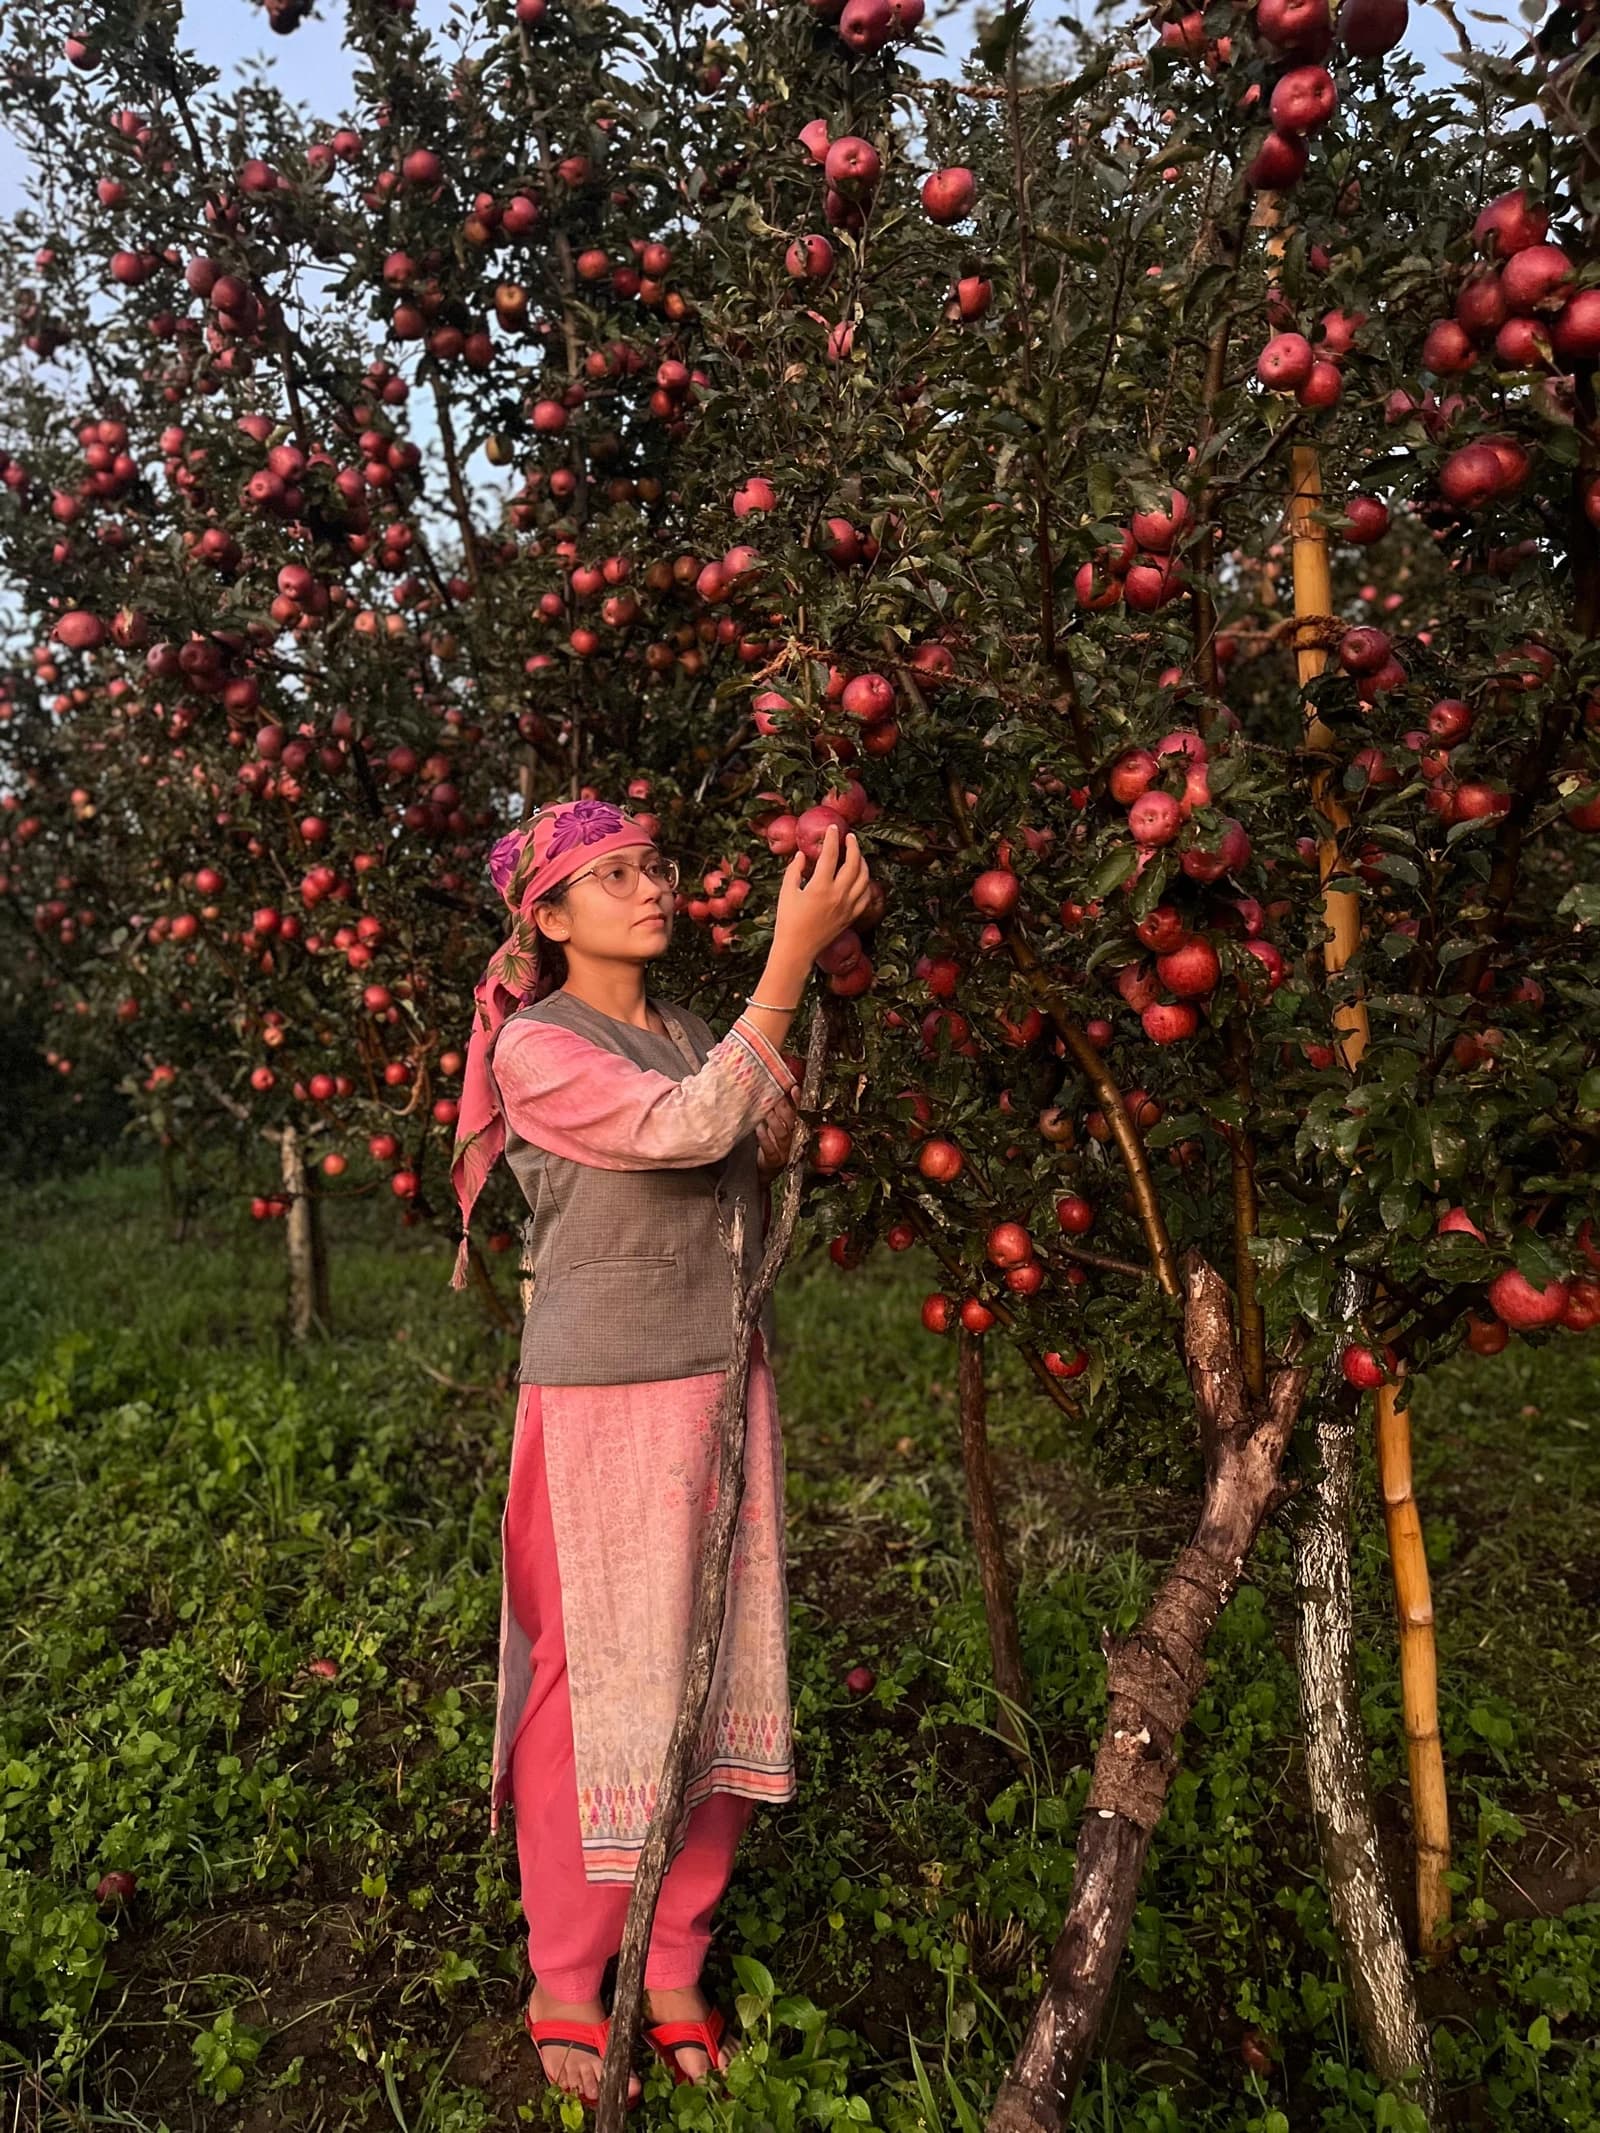
Farmers are increasingly turning to second-crop planting, drought-tolerant sweet sorghum, higher-performing wheat varieties and no-till systems as climate pressure makes traditional growing plans less reliable, and that shift could reshape demand across the agricultural supply chain.
Climate Resilience Reshapes Agricultural Demand

The economic significance is simple: when yields become more fragile, growers look for ways to stretch every acre, reduce input costs and protect margins. That makes crop diversification and conservation agriculture more than an agronomy trend. It becomes a capital-allocation decision on the farm, with spillover effects for seed makers, grain traders, fertilizer suppliers and equipment manufacturers.
For investors, that means the winners are likely to be the companies that help farmers produce more with less risk. Archer-Daniels-Midland and Bunge stand to benefit if more diversified crop rotations keep grain moving through elevators, processors and export channels. Deere can also gain if no-till and precision planting remain the preferred answer to soil degradation and drought, because those systems favor machinery, guidance tools and recurring technology upgrades over one-time purchases.
The move toward second harvests and more resilient crop mixes also fits a broader pattern in global agriculture: farmers are adapting to land degradation, water stress and erratic weather rather than waiting for conditions to normalize. That is why the story matters beyond one region or one growing season. It points to a structural change in how food is produced, stored and traded, with more emphasis on resilience, not just volume.
For long-term investors, that usually rewards the companies with scale, pricing power and embedded relationships across the farm economy. It also argues for patience. Agricultural cycles can be messy, and stock prices often swing well ahead of fundamentals — ADM and Bunge have both shown that with sharp moves around earnings and crop expectations, while Deere’s shares can get ahead of itself when the market prices in a strong equipment cycle.
The bigger takeaway is that farmers are not just reacting to bad weather; they are redesigning production systems. If no-till, wheat improvement and sorghum adoption keep expanding, that should support a more durable demand base for the best-run ag inputs and farm machinery companies. For investors building wealth over years, not weeks, that makes this a trend worth watching and, in the right diversified portfolio, worth owning.
| Entity | Gains | Losses |
|---|---|---|
| Farmers using rotation and no-till | ▲Lower weather risk | ▼Higher transition complexity |
| ADM and Bunge | ▲More grain flow and handling demand | ▼Margin pressure if crop failures persist |
| Deere | ▲Demand for no-till and precision equipment | ▼Weakness if farmers delay big purchases |
| Traditional single-crop growers | ▲— | ▼Greater yield and income volatility |