CoreWeave is tapping the convertible market for $3 billion, underscoring how aggressively the AI infrastructure race is still being financed even after a violent reset in high-growth stocks.
CoreWeave Plans $3 Billion Convertible Offering
That matters because CoreWeave sits at the center of the market’s most important capital cycle: the buildout of data-center capacity, GPU fleets and power-heavy compute infrastructure for artificial intelligence. A deal of this size says the company is still leaning on outside capital to keep scaling, and that investors are willing to underwrite the next leg of the AI buildout despite sharp volatility in the shares.
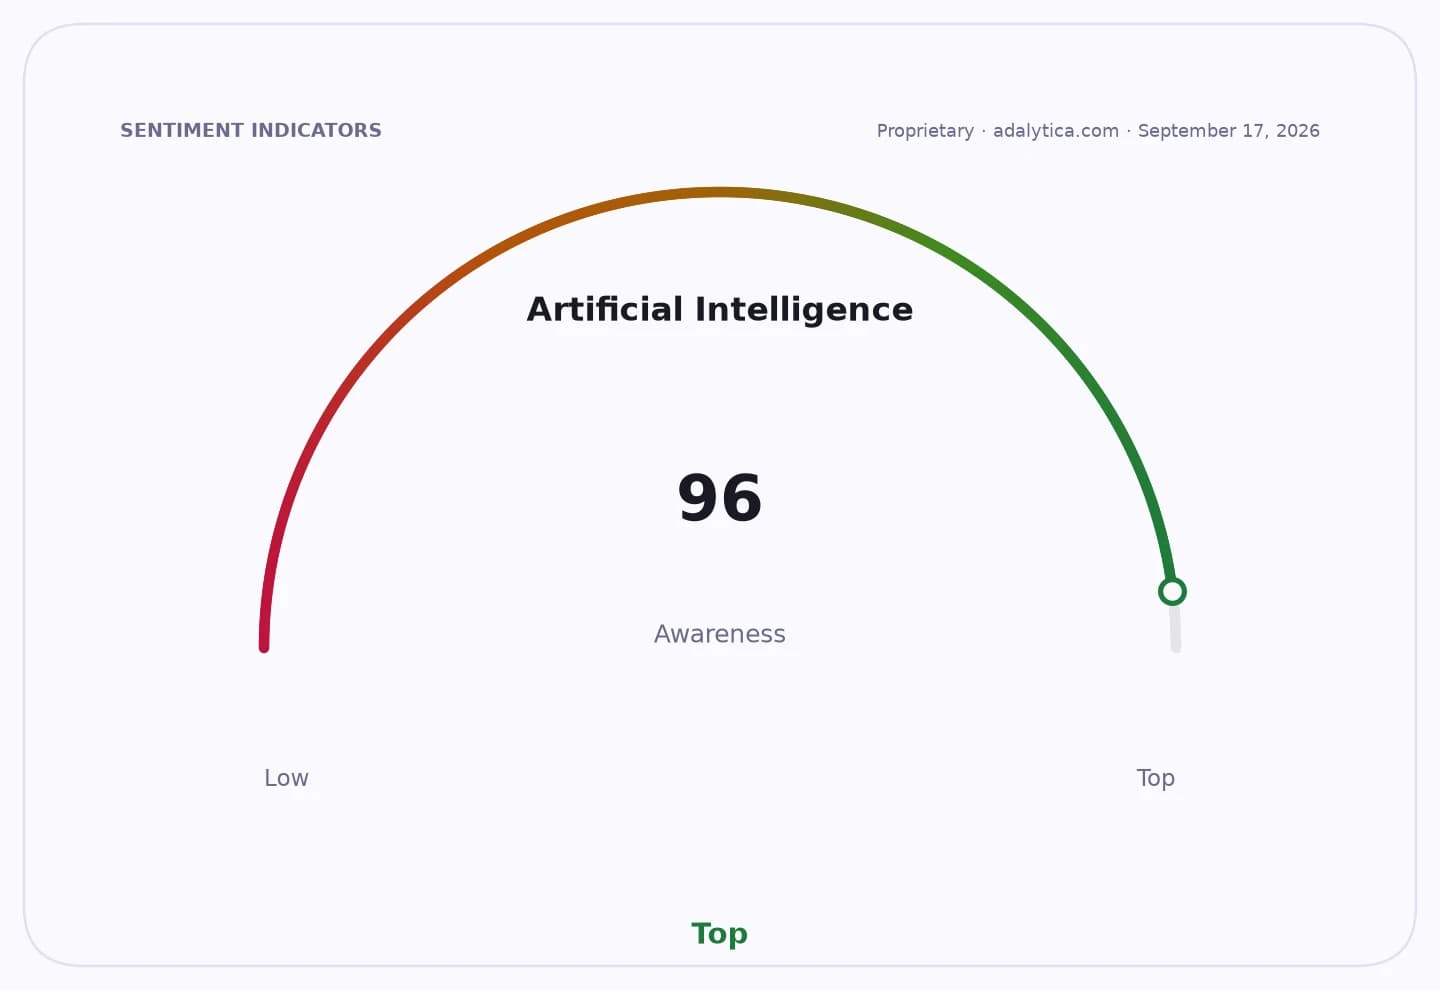
Sentiment IndicatorsⓘProprietary · adalytica.com · September 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The offering also highlights the financing model behind the AI trade. CoreWeave has become one of the clearest “picks-and-shovels” beneficiaries of the boom in model training and inference, but the business remains capital intensive. The company said in its filing that it plans to use part of the proceeds for capped call transactions and the rest for general corporate purposes, which typically means balance-sheet flexibility and funding growth. For investors, that is the key question: whether the company can keep expanding without overly diluting shareholders or locking in expensive financing.
The stock has been on a roller coaster, which only sharpens the stakes of this deal. CoreWeave closed at $81.36 on Sept. 18, far below a recent high above $137 and well under its 50-day and 200-day moving averages, a sign the market is still digesting how quickly the valuation expanded and corrected. The volatility reflects the same tension across the AI complex: enormous demand, enormous capex, and limited patience for execution stumbles.
That backdrop is why the financing matters beyond CoreWeave itself. Microsoft and Nvidia remain central counterparties to the AI infrastructure surge, and both have every incentive to see more compute capacity come online. Microsoft’s cloud and AI demand remains a strategic priority, while Nvidia’s latest disclosures point to a deeper push into AI cloud partners that can broaden access to its data-center stack. CoreWeave is one of the toll roads in that ecosystem, and this raise suggests the road is still being widened.
For investors, the opportunity is not to chase the headline, but to identify who benefits from the next round of infrastructure spending. If AI demand keeps compounding, the winners are likely to be the suppliers of chips, power, networking and specialized cloud capacity — not the companies trying to build it all themselves with fragile capital structures. I believe this is exactly where the market still underestimates the scale of the capex cycle.
The next catalyst will be whether CoreWeave can place the notes on attractive terms and whether the market reads the financing as growth fuel or as another reminder that AI expansion is still very much funded by leverage. Either way, the message is clear: the AI infrastructure trade is far from over, and the best positioning is still in the companies selling the picks and shovels.
| Entity | Gains | Losses |
|---|---|---|
| CoreWeave | ▲Fresh growth capital | ▼Higher leverage/dilution risk |
| Nvidia | ▲More AI infrastructure demand | ▼Customer concentration risk |
| Microsoft | ▲More cloud compute supply | ▼Continued dependence on external capacity |
| Existing CRWV holders | ▲Potentially faster expansion | ▼Share price volatility, dilution pressure |