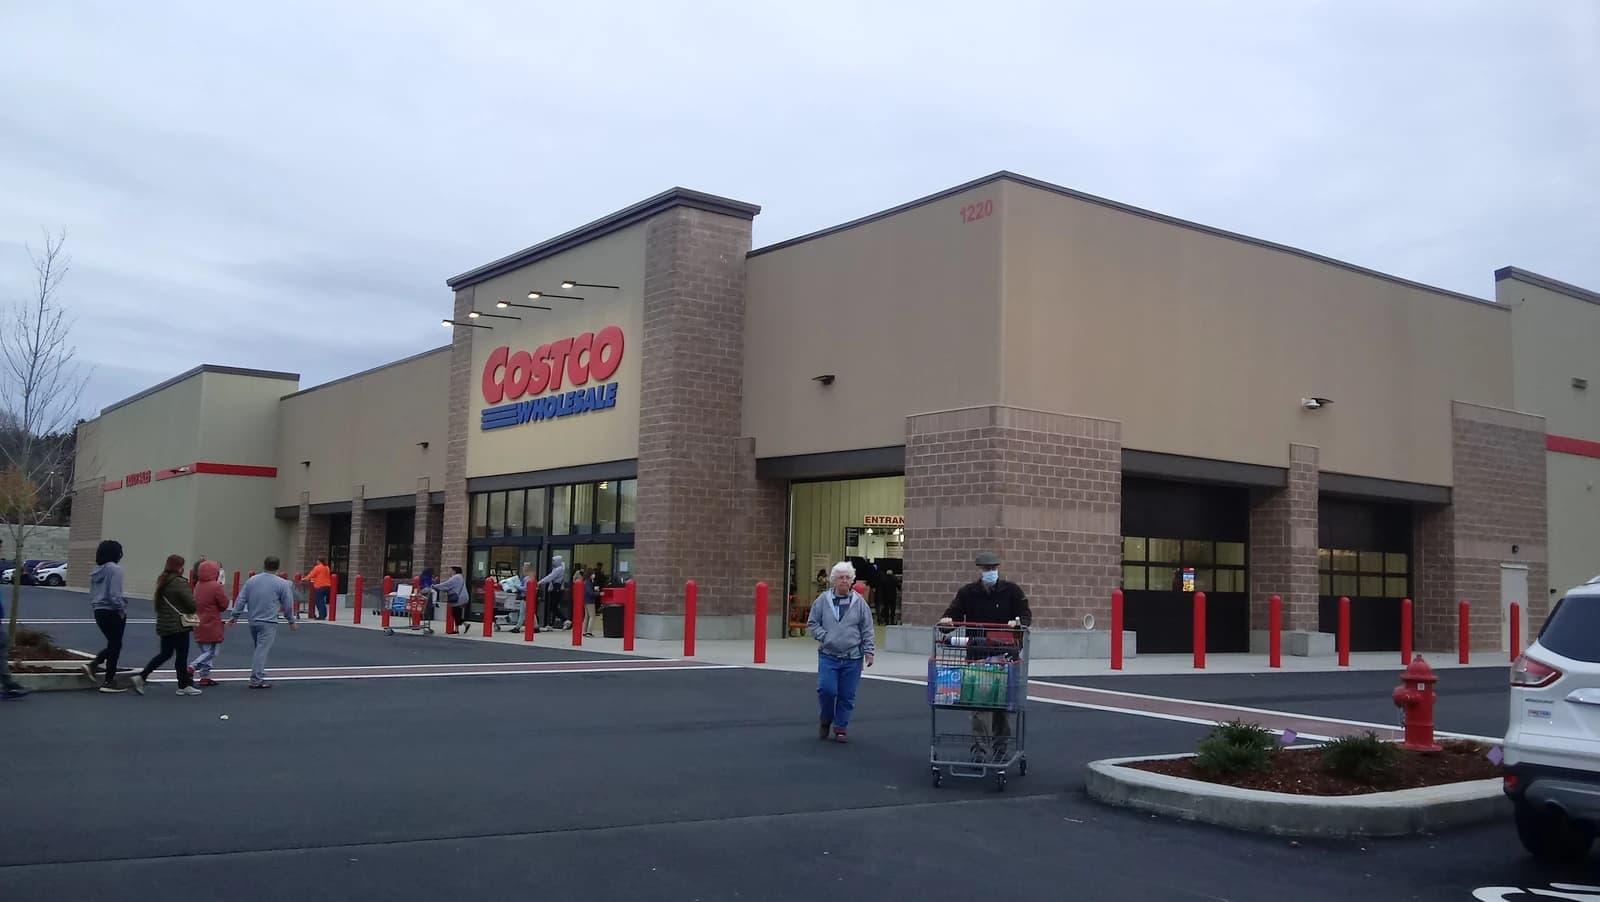
Costco is pulling in more younger members, reinforcing the warehouse chain’s biggest long-term advantage: a subscription-style business that compounds as new households join early and stay for years.
Costco gains younger members and stays strong
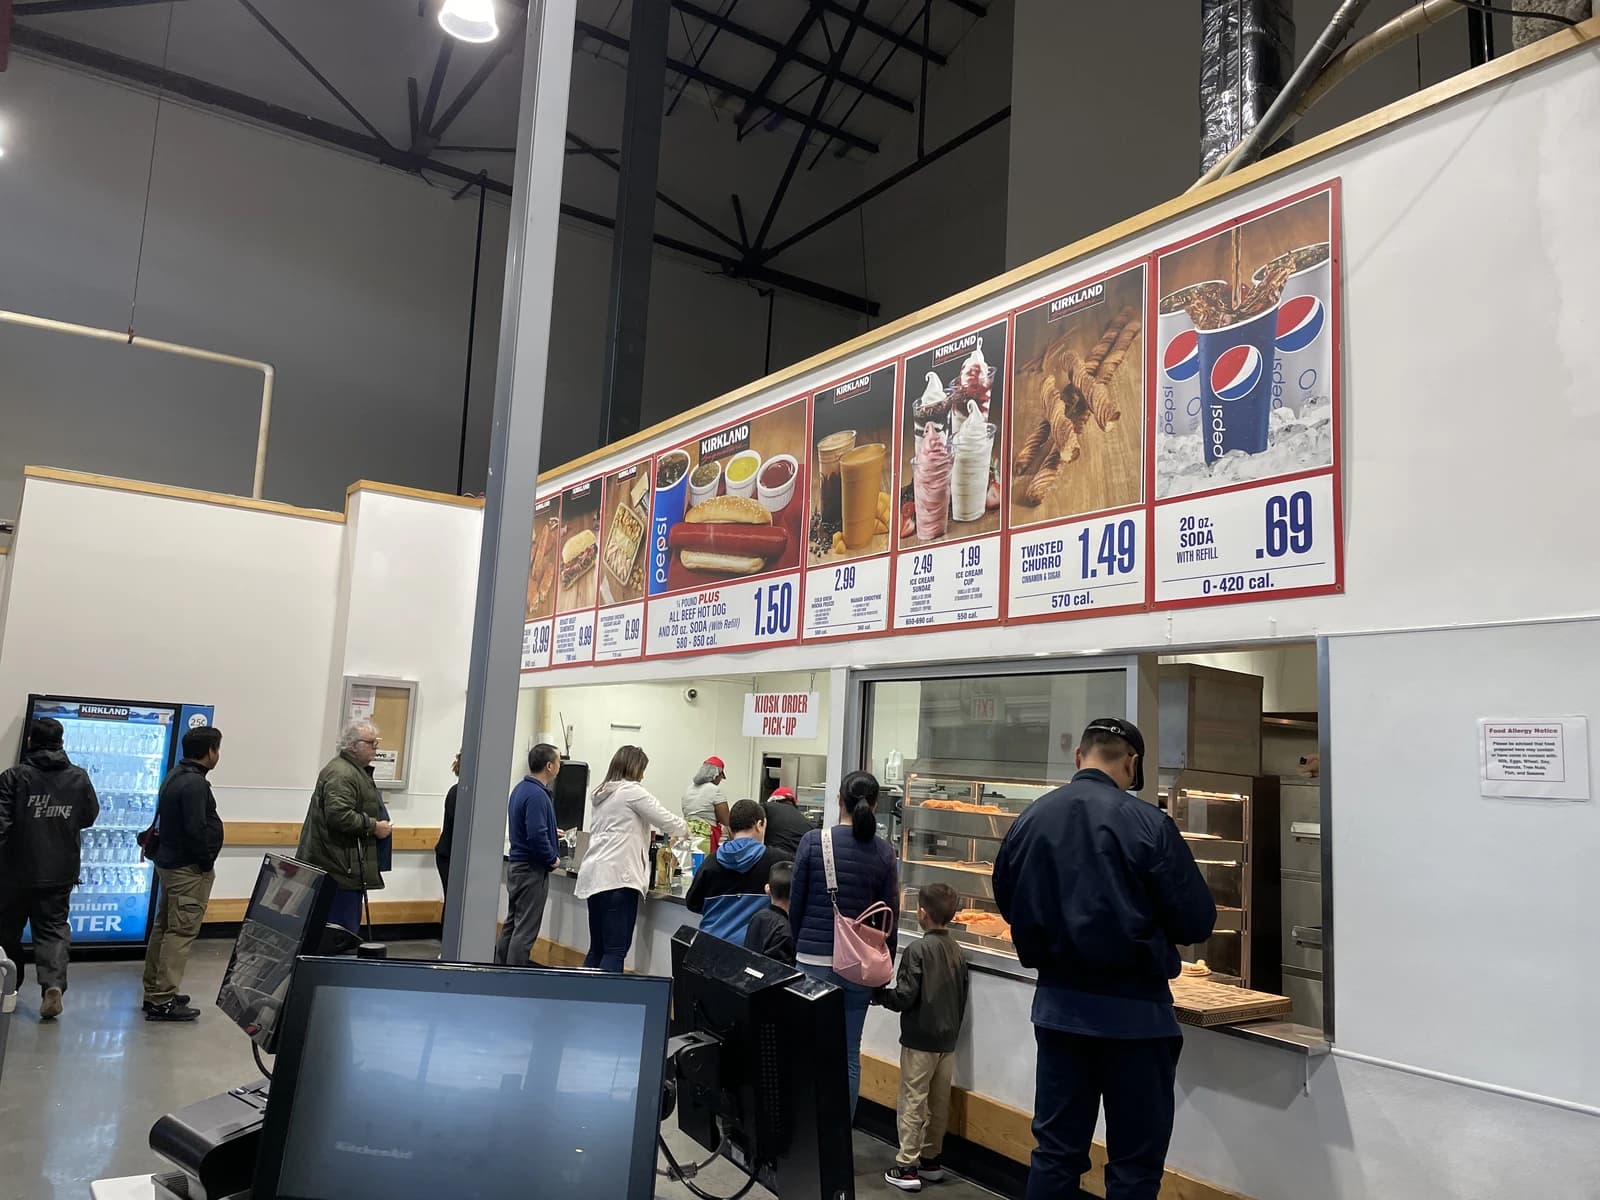
That matters because Costco’s growth story is no longer just about traffic or grocery inflation. It is about lifetime value. Younger members are the kind of customer base retailers fight hardest to win because they tend to renew longer, spend more over time and anchor multi-decade relationships. For Costco, that can translate into steadier fee income, stronger renewal economics and a wider moat against rivals trying to lure value-conscious shoppers with apps, delivery and aggressive promotions.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 14, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The market underestimates how powerful that engine can be when consumer behavior shifts toward bulk buying and disciplined spending. Costco’s latest filing said its ability to grow the membership base, increase Executive penetration and sustain high renewal rates materially influences profitability. In other words, every new member is not just a sale today but a stream of recurring cash flow tomorrow. That is exactly the kind of durability investors pay up for in a shaky macro backdrop.
The stock has already reflected some of that premium. Costco closed at $954.63 on Oct. 13, still well above its 200-day moving average near $962.55 and just below the upper end of its recent trading band. Technical readings show the shares have been strong even after recent volatility, with the 50-day moving average around $931.59 and RSI readings still elevated at 73.4, suggesting momentum remains stretched but intact. That is consistent with a market that continues to prize Costco’s quality, even as the broader consumer tape gets more uneven.
The bigger message for investors is that Costco’s membership mix may be entering a new phase. A younger customer base expands the addressable market beyond the traditional affluent family shopper and helps insulate the business from cyclical pressure. It also strengthens Costco’s hand as it keeps investing in supply chain speed, delivery and warehouse efficiency, all of which can deepen loyalty and increase frequency.
That creates a clear setup for the next leg of the story: if younger members keep joining and renewing, Costco’s fee income can grow faster than many investors expect, while the chain’s scale advantages widen further. For long-term investors, the thesis remains straightforward — Costco is not just a retailer, it is a recurring-revenue platform disguised as one.
| Entity | Gains | Losses |
|---|---|---|
| Costco | ▲Higher renewal loyalty | ▼Less customer churn |
| Younger members | ▲Bulk savings | ▼Less need for rivals |
| Walmart/Sam's Club | ▲Pressure to match value | ▼Mindshare in affluent young households |
| BJ's Wholesale | ▲Harder member acquisition | ▼Relative scale disadvantage |