Investors are heading into a pivotal week for inflation, with the market's next major move likely to be determined by whether the upcoming CPI and PPI reports confirm that price pressures are cooling fast enough to keep the Federal Reserve on track for easier policy.
CPI, PPI Inflation Data Drive Market Focus This Week
That matters because the bond market is already pricing a lot of good news into duration assets while equities have pushed into stretched territory. The S&P 500 is near record highs, Treasury yields remain elevated, and trading desks are sensitive to any upside surprise that could quickly unwind the year-end rate-cut narrative.
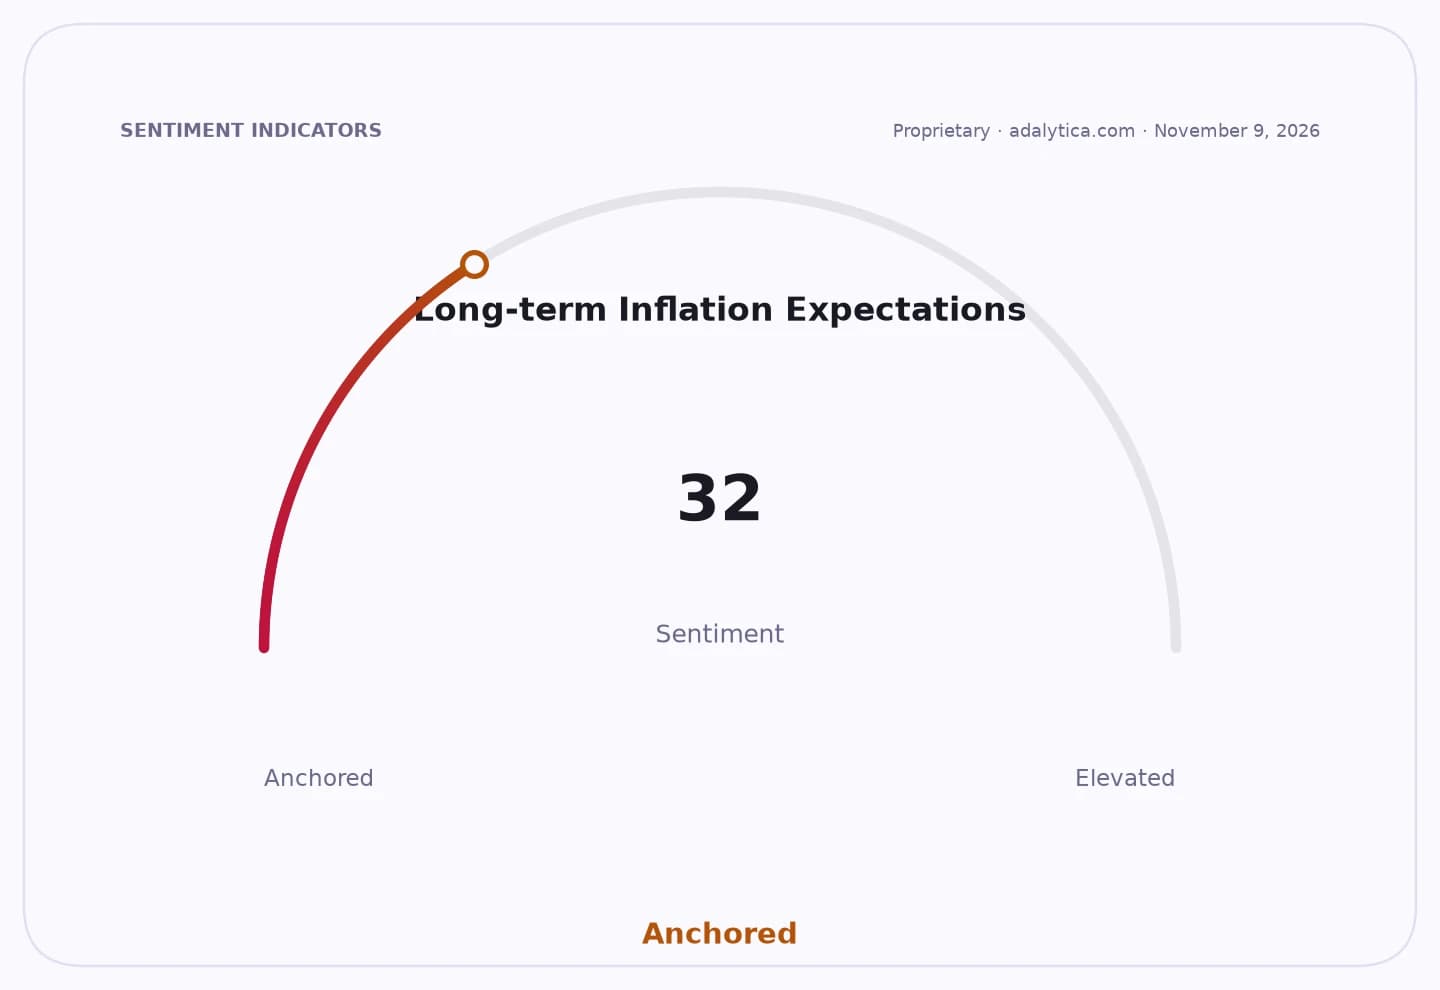
Sentiment Indicators
The setup is unusually clean: CPI on Tuesday and PPI later in the week will give traders the freshest read on both consumer and wholesale inflation before the Fed’s next decision path is repriced. If consumer prices and producer prices come in soft, it strengthens the case that inflation is grinding lower and that real yields have room to ease. If they reaccelerate, the market will have to face the possibility that the Fed stays restrictive longer than bulls want to believe.
That tension is already visible in rate-sensitive assets. The 10-year Treasury yield has been holding around 5.2% to 5.3%, a level that still argues for caution on long-duration growth valuations. At the same time, TLT, the long Treasury ETF, has been crushed, closing near 78, well below its 50-day and 200-day moving averages, with a deeply oversold RSI reading that shows how much bad inflation news is already embedded. In contrast, SPY has stayed buoyant near 779, but Adalytica’s trade signals show “Extreme Greed,” a reminder that equities are vulnerable if the macro backdrop turns less forgiving.
CPIAUCSL vs PPIACO — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.
The economic issue is straightforward: inflation determines the path of real rates, and real rates determine everything from mortgage costs to corporate financing to equity multiples. Softer CPI and PPI readings would support the case for lower borrowing costs and broader multiple expansion, especially in rate-sensitive pockets such as homebuilders, utilities, REITs and long-duration tech. A hot print would do the opposite, pushing yields higher, pressuring small caps and growth stocks, and reviving the market’s obsession with sticky services inflation.
The bond market closure on Monday only adds to the importance of the data later in the week. With Treasury trading paused at the start, investors will have one less buffer before the CPI release hits a market already leaning toward complacency. That raises the odds of a sharp repricing if the numbers surprise.
My view is that the market underestimates how asymmetric this setup is. When positioning is crowded and volatility is suppressed, the inflation reports do not need to be disastrous to matter; they only need to be slightly hotter than expected to disrupt a fragile rally in bonds and rate-sensitive equities. That makes the week a catalyst not just for Fed expectations, but for leadership across the entire equity market.
If inflation cools, the winners are long-duration assets, Treasury bulls and quality growth stocks. If it does not, the trade shifts back toward cash flow, pricing power and balance-sheet strength. For investors, this is the week to respect the macro before chasing the momentum.
| Entity | Gains | Losses |
|---|---|---|
| Treasury bulls / TLT | ▲Softer CPI, lower yields | ▼Hot inflation, higher term premium |
| S&P 500 growth stocks | ▲Easier rate-cut path | ▼Multiple pressure from sticky rates |
| Value / pricing-power stocks | ▲Sticky inflation support | ▼Disinflation-driven rotation |
| Fed doves | ▲Validation of easing case | ▼Delay in rate-cut timeline |