DLF has sold every apartment in its latest Gurugram luxury project, underscoring how India’s top-end housing market is still drawing wealthy buyers even as broader sentiment around housing weakens.
DLF sells out Gurugram luxury apartments
That matters because the deal shows luxury residential demand can remain resilient when the mass market gets choppy. With each apartment priced at Rs 11.5 crore, the project sits at the very top of the domestic market, where buyers are typically less dependent on mortgage rates and more focused on location, scarcity and status. For DLF, India’s largest listed real-estate developer, a fast sellout is not just a headline grabber — it is a reminder that premium inventory can convert into cash even in a more uneven housing cycle.
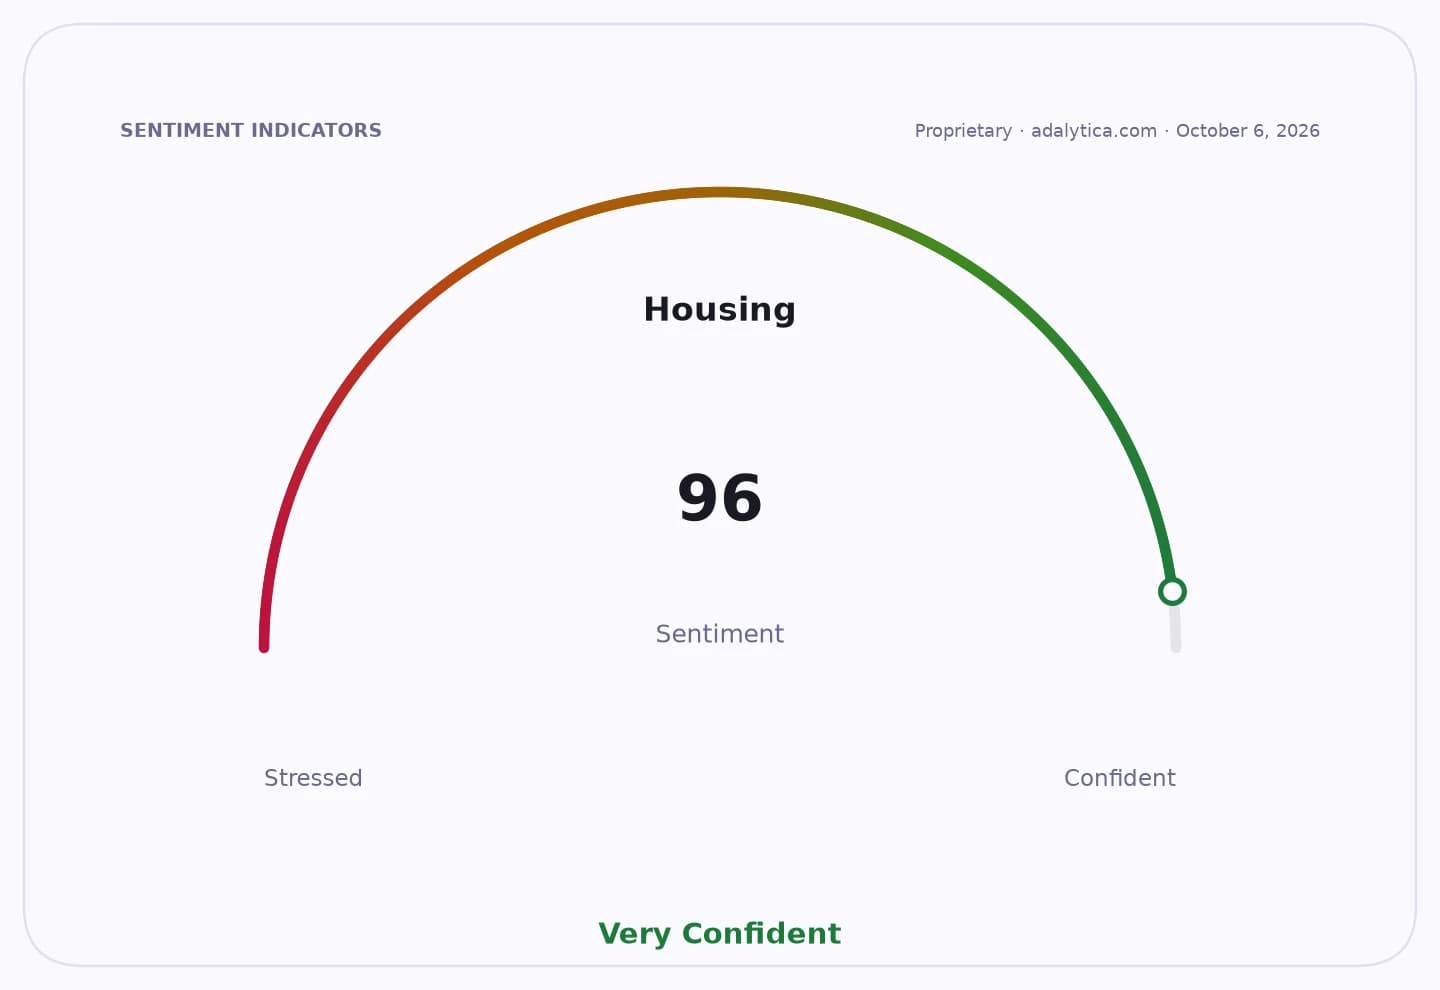
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The timing is notable. Adalytica’s Housing Fear & Greed Index for the broader housing market shows “Extreme Fear,” suggesting caution among homebuyers and investors elsewhere in the sector. Yet luxury property is behaving differently. That split is important for investors because it argues for a two-track real-estate market: premium urban homes can keep pricing power and absorption, while mid-market and mass housing may face more pressure if sentiment and affordability stay weak.
The backdrop also supports the long-term case. India’s housing market has been expanding rapidly, with the value of projects under construction rising sharply in recent years, helped by infrastructure spending, urbanization and still-healthy demand for home ownership. In that environment, developers with strong brands, prime land banks and access to affluent customers are best placed to keep margins intact and avoid the discounting that can hit less differentiated builders.
For investors, DLF’s sellout reinforces a simple idea: in real estate, quality matters more than cycle timing. A trophy project in Gurugram does not tell you everything about India housing, but it does tell you where the money is going when confidence is selective. The company’s challenge now is to keep translating that premium demand into consistent cash flow and returns, which is what matters over the next several years. Worth watching, and for long-term investors, worth keeping on the watchlist.
| Entity | Gains | Losses |
|---|---|---|
| DLF | ▲Faster cash conversion | ▼Broader housing slowdown |
| Luxury homebuyers | ▲Scarcity access | ▼Negotiating leverage |
| Competing developers | ▲Sector validation | ▼Missed premium demand |
| Mass-market housing | ▲Little direct benefit | ▼Weak sentiment pressure |