The Dow Jones finished Wednesday slightly lower, but the bigger market story is that Wall Street is still finding support from trading desks even as some of the market’s largest technology names fade and customer activity cools.
Dow Jones Falls as Rotation Favors Defensives
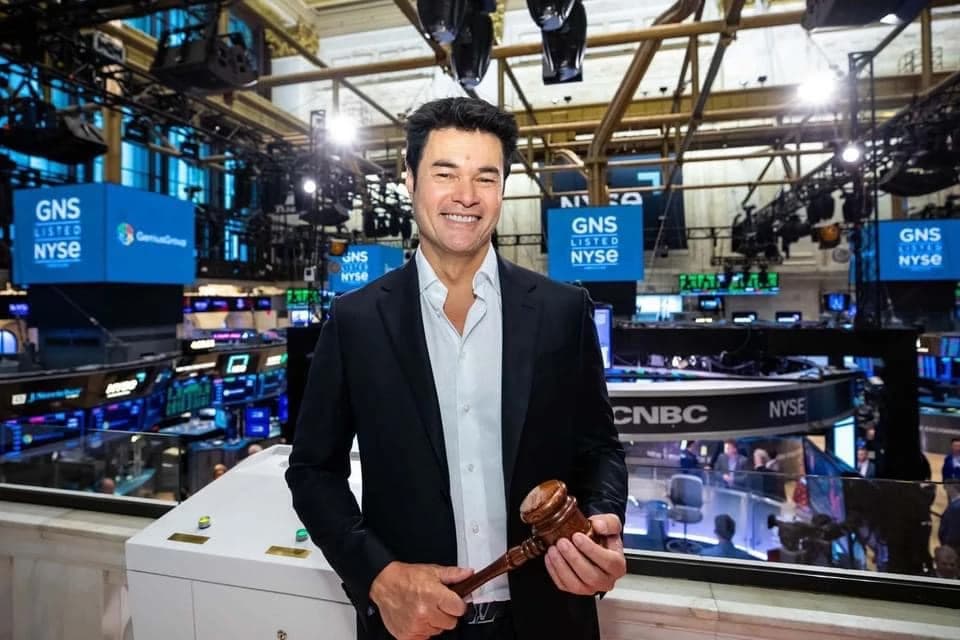
The blue-chip index slipped 0.09% to 51,621.48 after opening with a gain of 0.818%, underscoring a market that is still capable of absorbing profit-taking rather than breaking down. That matters because the Dow’s advance this year — 6.69% so far in 2026 — has been built on a mix of resilient earnings, defensives and still-solid market liquidity, not just momentum in a handful of megacap names.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 16, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The day’s leadership told the real story. UnitedHealth, Merck, Walmart, Amgen and Procter & Gamble led the index higher, while Nvidia, Caterpillar, Microsoft, Amazon and Alphabet all fell. That is a classic sign of rotation rather than broad stress: money is moving away from the highest-profile growth winners and into health care, consumer staples and other cash-generative companies that can hold up if growth cools.
That backdrop fits with the latest readthrough from JPMorgan Chase, which posted a 6% jump in third-quarter profit even as chief executive Jamie Dimon said customer activity had slowed slightly. The bank’s equities business helped carry results, a reminder that trading revenue can still cushion Wall Street when clients become more cautious. For investors, that is important because it suggests the market’s plumbing remains healthy even if conviction is slipping in parts of the risk rally.
Macro conditions also help explain the tone. The 10-year Treasury yield is still around 5.17%, keeping pressure on long-duration growth stocks and making valuation discipline matter more. At the same time, unemployment is forecast near 4.09% and inflation is still running above 3.3% on the CPI measure, a combination that argues for a Fed that is not rushing into aggressive easing. That is a constructive setup for banks, insurers, pharmaceuticals and other sectors with pricing power, but less comfortable for richly valued technology.
From a trading perspective, the Dow’s dip left the index near its 50-day moving average rather than in technical breakdown territory, with the broader S&P 500 also still above its 200-day moving average. That supports the view that this is a rotation market, not a bear market. Adalytica’s S&P 500 trade signals show sentiment in neutral territory even as awareness remains in extreme fear, a setup that often leaves room for further selective upside.
The investable implication is straightforward: the market is rewarding balance sheet strength, dividends and visible earnings more than narrative alone. Investors looking for the next leg higher should focus on the sectors benefiting from persistent rates and continued trading activity — banks, health care, staples and selected industrials — while treating stretched AI and megacap tech exposure more selectively. If JPMorgan’s trading strength and the Dow’s rotation are the guide, the next winning trade is not chasing every high-multiple name, but owning the companies the market leans on when momentum cools.
| Entity | Gains | Losses |
|---|---|---|
| JPMorgan Chase | ▲Trading revenue support | ▼Slower customer activity |
| Health care and staples | ▲Defensive inflows | ▼Less relative capital |
| Dow Jones defensives | ▲Index support | ▼Megacap tech leadership |
| Nvidia, Microsoft, Amazon, Alphabet | ▲ | ▼Rotation pressure |