The European Central Bank is weighing a move that would pull more cash out of the banking system and ease its own mounting interest bill, a shift that matters because it would tighten liquidity without changing policy rates. Officials will discuss next week whether to lift the euro zone’s mandatory reserve ratio to 2% from 1%, according to people familiar with the matter, a step that could save the ECB and national central banks about 4.4 billion euros a year at current rates.
ECB Weighs Raising Euro Zone Reserve Ratio to 2%
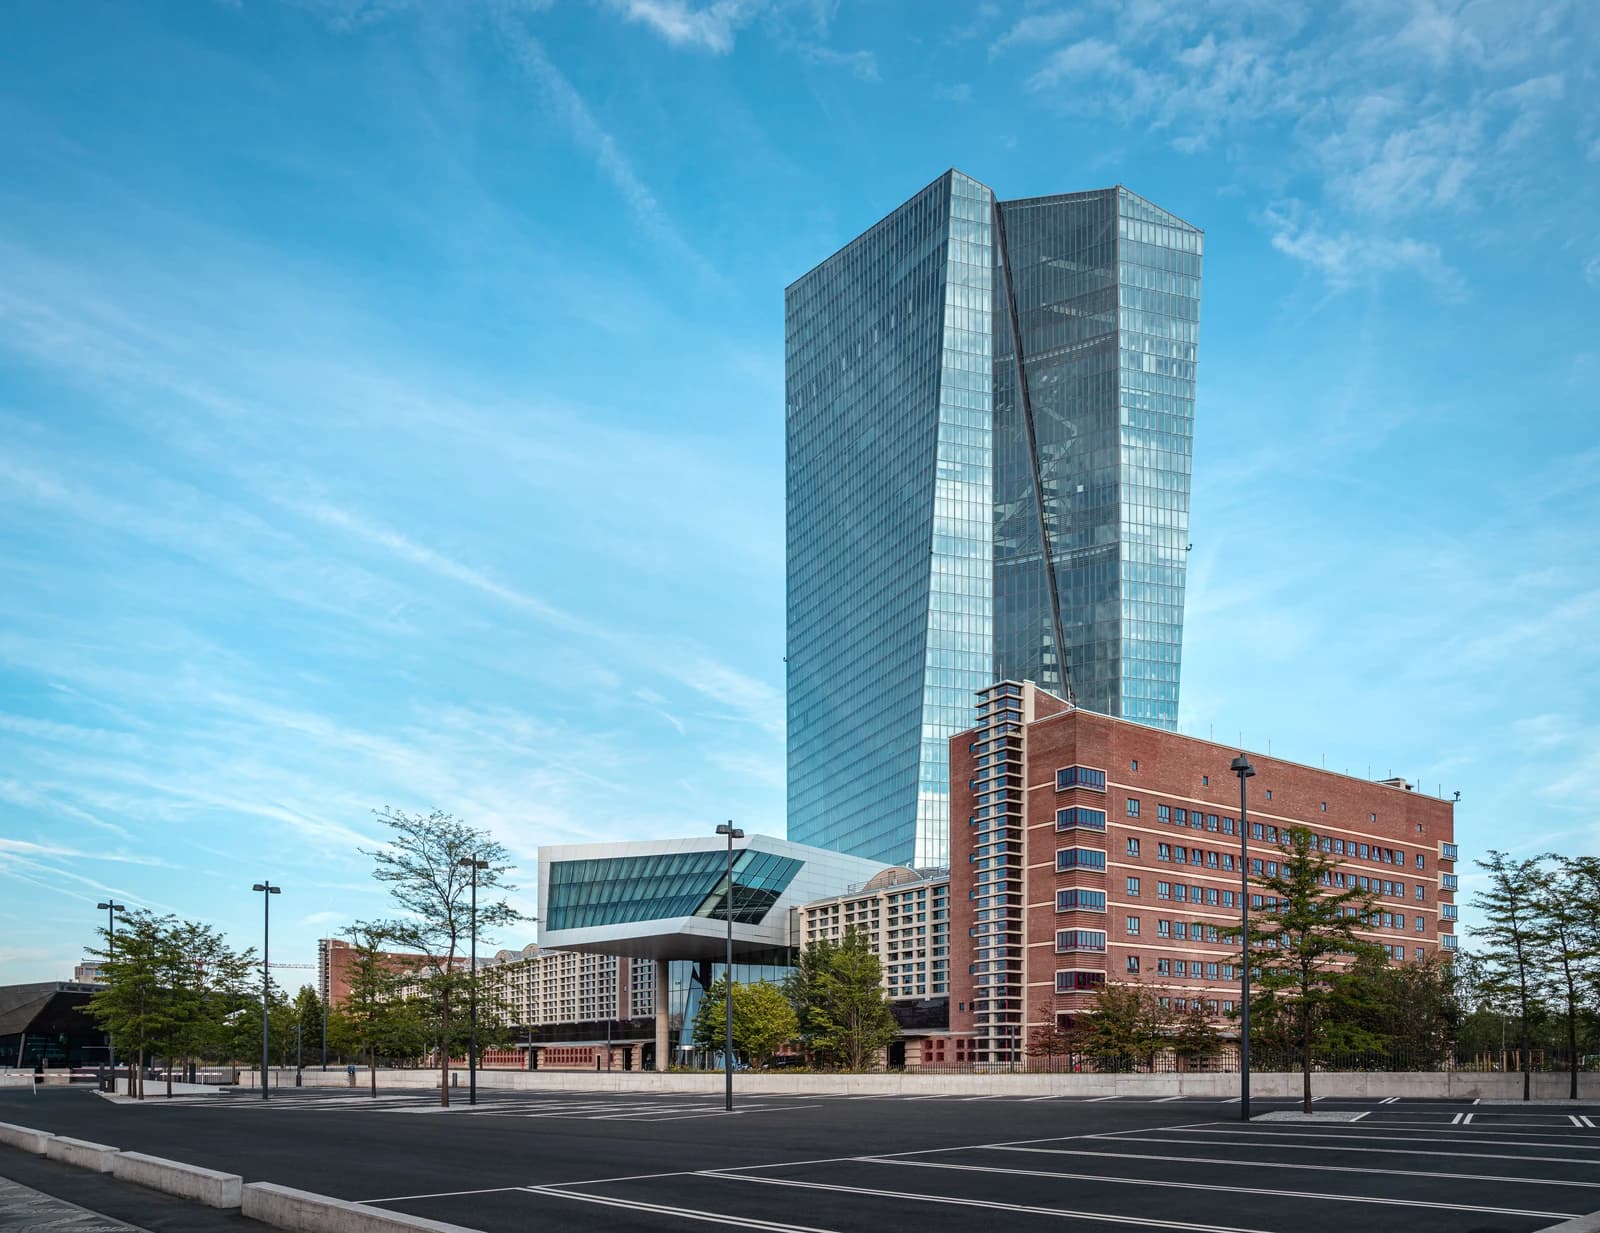
That makes this more than a technical tweak. The ECB has spent years pumping liquidity into the system through asset purchases and long-running stimulus, and now it is paying heavily for the excess cash parked at the central bank. Euro zone banks currently earn deposit interest on money held above the required reserve, while the mandatory portion is non-interest bearing. With more than 2 trillion euros of excess liquidity in the system, the ECB and the 21 national central banks that use the euro are paying 52.2 billion euros in annual interest.
Sentiment Indicators
For policymakers, the attraction is obvious: a higher reserve ratio would reduce the amount of reserves that attract interest and help lower losses at central banks such as Germany’s Bundesbank, which has become politically sensitive because it raises questions about credibility and, in the worst case, taxpayer support. The savings could grow further if the ECB cuts its deposit rate from 2.5% to as low as 3% to 3.25% next year, as some market participants expect.
For investors, the move matters because it would effectively tighten financial conditions at the margin just as the market is trying to gauge how far the ECB is willing to go in draining liquidity. That is usually a negative for banks’ funding flexibility and a mild headwind for credit creation, even if large euro zone lenders remain well capitalized. It also reinforces the message that the ECB is not done adjusting its post-stimulus framework after raising rates to fight inflation.
The market is already sensitive to that shift. Euro zone bank shares have held up better than the broader region this year, but they remain exposed to any policy that compresses excess liquidity or changes the economics of central bank reserves. A reserve-ratio hike would be especially relevant for banks with large deposit bases and abundant liquidity, because it would lock up more low-yield assets at the central bank instead of leaving them free to earn interest elsewhere.
The bigger narrative is that central banks are moving from crisis-era abundance to a more disciplined liquidity regime. The ECB’s discussion next week, whether it comes on Nov. 25 or is deferred to the Dec. 17 policy meeting, would be one of the clearest signs yet that the era of easy reserve management in the euro zone is fading.
For investors, the playbook is straightforward: the winners are banks and lenders with strong deposit franchises and limited reliance on short-term liquidity; the losers are cash-rich banks, and by extension any sector that depends on abundant and cheap euro liquidity. The ECB is not just managing rates now — it is managing the plumbing.
| Entity | Gains | Losses |
|---|---|---|
| ECB / national central banks | ▲Lower interest expense | ▼Less excess liquidity |
| Euro zone banks with strong deposit franchises | ▲Stable funding advantage | ▼Lower reserve earnings |
| Cash-rich banks | ▲— | ▼More funds locked at ECB |
| Bank investors / bank ETFs | ▲Clarity on policy framework | ▼Margin pressure from tighter liquidity |