The Egyptian Exchange is getting its first government offering of the year, with Bank of Cairo’s long-awaited listing set to reopen a privatization channel investors have been watching for signs of life.
Egypt Bank of Cairo IPO reopens privatization push
That matters because Egypt needs capital, not just headlines. A successful placement would signal that Cairo is still willing to push state asset sales after years of delay, a key test for a government that has leaned on the IMF-backed privatization agenda to widen ownership, deepen market liquidity and attract foreign money back into local assets.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
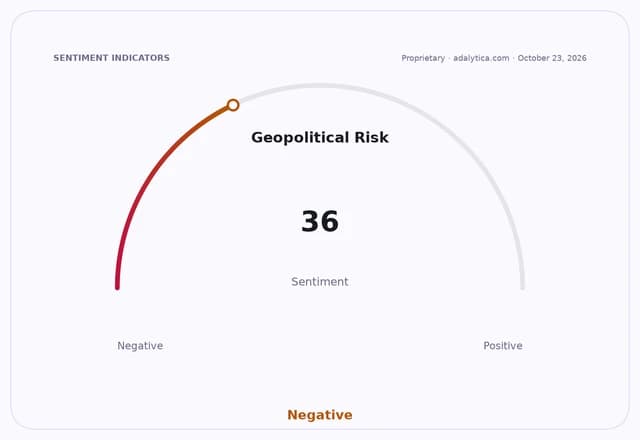
For investors, Bank of Cairo is more than another bank stock. It is a referendum on whether Egypt can still price quality state-linked assets attractively enough to pull in domestic institutions and offshore funds at a time when emerging-market risk appetite remains fragile. Adalytica’s Global Stability Sentiment is still only neutral, while awareness is in extreme fear, a reminder that capital is moving cautiously even as interest in reform stories returns.
The timing also matters for Egypt’s exchange. After nine years on the listing pipeline, Bank of Cairo arrives as one of the most closely watched financial-sector offerings in the market, and its reception could shape expectations for future privatizations. If demand is strong, the deal would support the broader thesis that Egypt’s capital markets are entering a new phase where state divestments become a recurring source of supply rather than a one-off event.
That would have second-order effects. More listings would improve breadth, trading turnover and benchmark relevance for the Egyptian market, while giving local banks and asset managers a fresh pipeline of equity opportunities. For the government, it would help convert policy promises into proceeds and credibility, both of which remain crucial as it tries to balance fiscal needs, currency stability and investor confidence.
The message for investors is straightforward: the market underestimates how powerful a credible privatization cycle can be in a country like Egypt. If Bank of Cairo lands well, this is not just a bank IPO — it could be the opening trade in a larger rerating of Egyptian assets.
| Entity | Gains | Losses |
|---|---|---|
| Egyptian government | ▲Privatization proceeds | ▼Pressure to deliver |
| Bank of Cairo | ▲Public-market capital | ▼State ownership shield |
| Egypt Stock Exchange | ▲More liquidity | ▼Reliance on one marquee deal |
| Sideline investors | ▲Fresh entry point | ▼Those expecting delay |