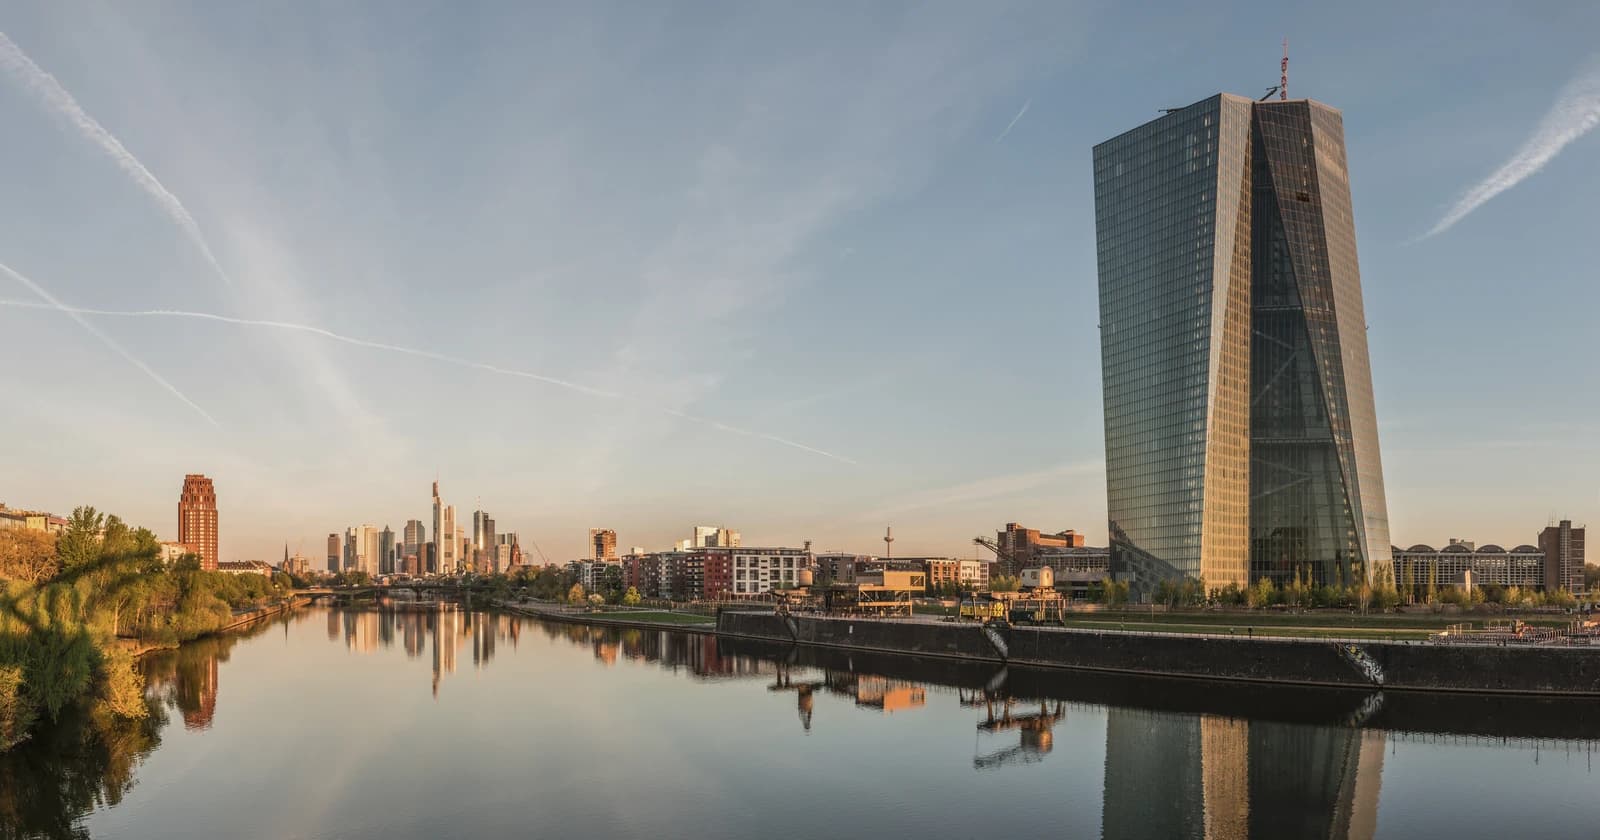
The euro slipped and the dollar firmed after the European Central Bank raised interest rates, a move that underscores how aggressively markets are now pricing global policy divergence and the risk that Europe’s tightening path cannot match U.S. yields.
Euro Falls After ECB Rate Hike

That matters because currencies are increasingly being driven less by the headline rate move itself and more by the relative return on offer. With the U.S. 10-year Treasury yield near 4.95% and the two-year at 4.57%, the dollar still has a powerful carry advantage over the euro, where the latest policy move has not been enough to reverse the broader pressure. The euro held around $1.16, but the technical picture remains soft, with the pair trading near its 50-day and 200-day moving averages and RSI readings still below the middle of the range.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 12, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, that means the stronger-dollar trade remains alive even after the ECB action. The Invesco DB U.S. Dollar Index Bullish Fund, UUP, has climbed to 28.07, above both its 50-day and 200-day moving averages, while FXE, the euro ETF, sits at 107.01 and has struggled to regain momentum. The message is simple: unless Europe can convince markets that inflation is durable enough to justify more hikes, capital is likely to keep favoring dollar assets with higher yields and deeper liquidity.
The broader macro setup reinforces that view. U.S. inflation remains elevated, with the CPI index at 334.131 in August, and that keeps the Federal Reserve’s policy stance comparatively restrictive. In that environment, the ECB’s tightening can lift European short rates, but it does not automatically close the transatlantic yield gap that drives currency flows. Adalytica’s trade signals also show extreme fear in the broader equity complex and surging confidence in the yuan, a reminder that investors are rotating across FX and risk assets with policy differentials, not just growth stories, front and center.
The investment implication is that dollar strength may persist even if the ECB continues to hike, and that has second-order winners and losers across equities, commodities and multinationals. U.S.-based companies with large overseas revenue exposure can get a translation tailwind, while European exporters face a less helpful currency backdrop. For now, the market is treating the ECB move as a confirmation of monetary tightening, not a turning point for the euro.
| Entity | Gains | Losses |
|---|---|---|
| U.S. dollar | ▲Yield advantage | ▼— |
| Euro | ▲— | ▼Policy divergence |
| UUP | ▲Higher dollar exposure | ▼FXE |
| U.S. multinationals | ▲Translation tailwind | ▼European exporters |