European stocks rose as crude eased back under $100 a barrel, a welcome shift that helps cool inflation fears and takes some pressure off interest-rate markets.
European Stocks Rise as Brent Falls Below $100
That matters because oil is still one of the fastest ways energy costs, transport bills and consumer prices can feed through the economy. When crude retreats, companies outside the energy sector get breathing room on margins, while investors are more willing to bet that central banks may not need to keep pushing rates higher for as long.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
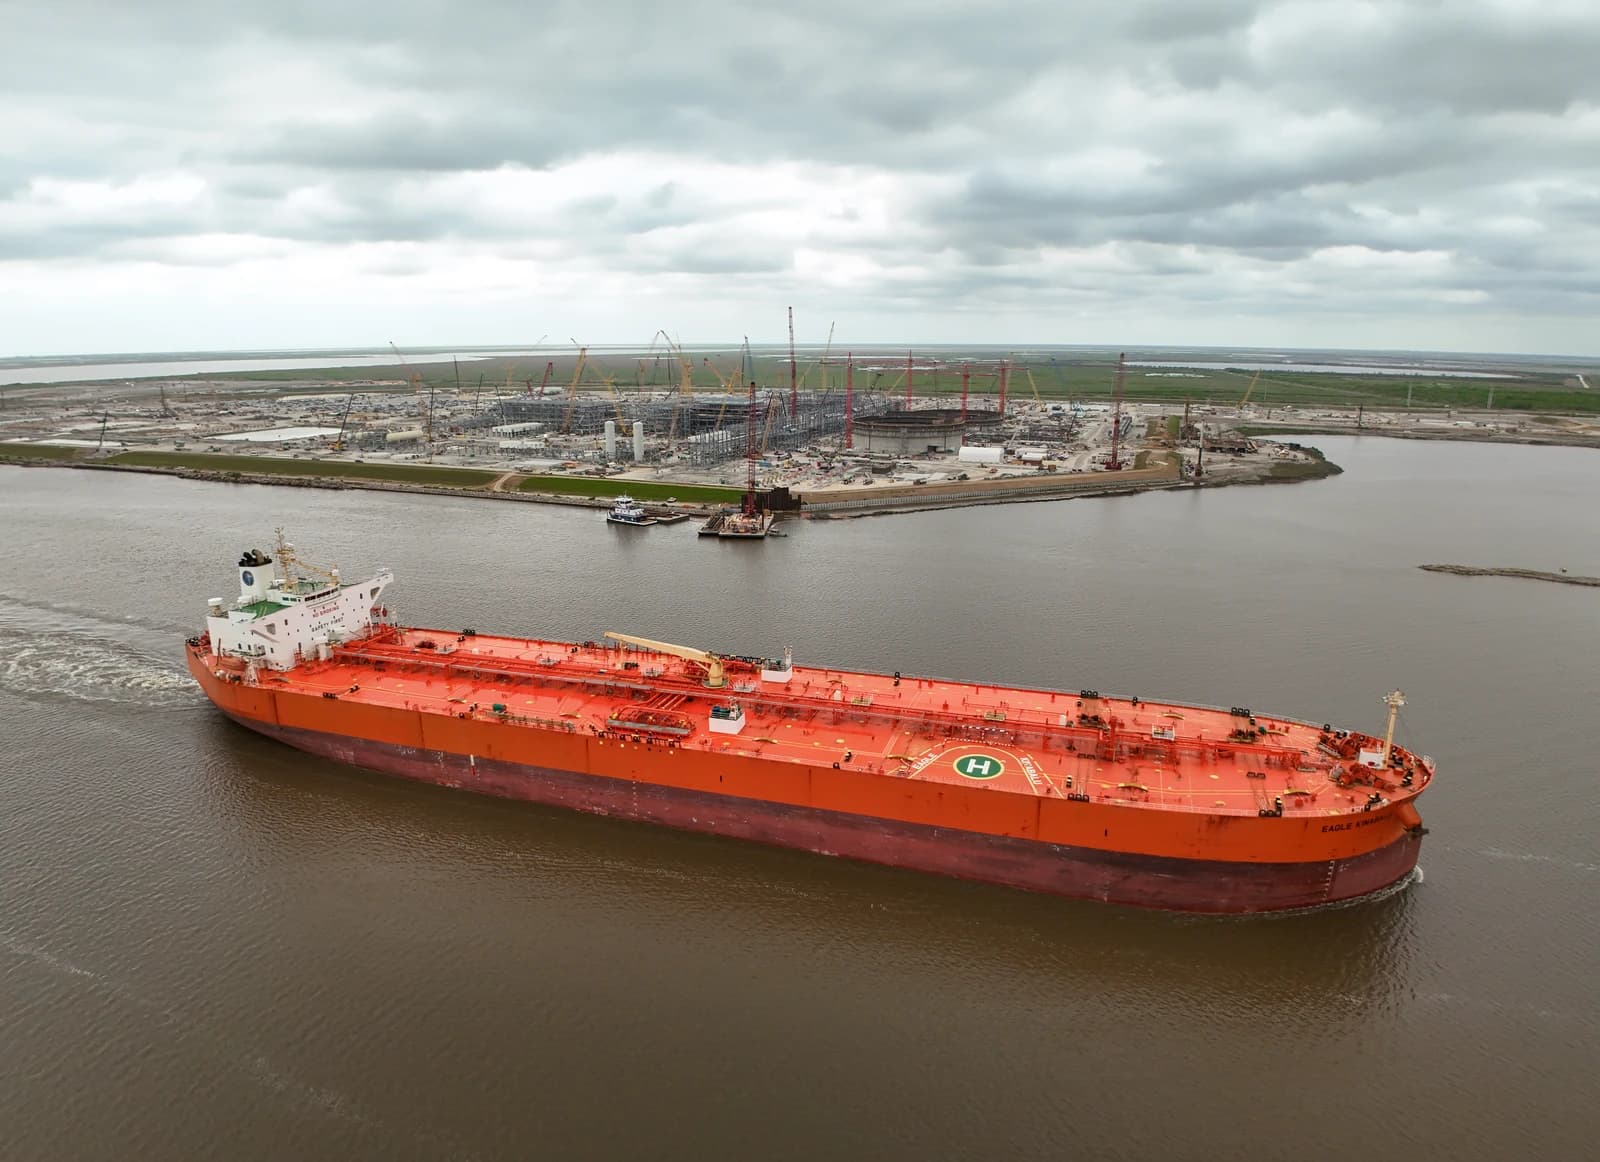
The FTSE MIB in Milan gained 0.87%, while London, Paris, Frankfurt and Madrid also finished higher. Brent slipped to about $99.24 after Saudi Arabia cut prices, a sign the physical market is less tight than it was earlier this year. U.S. crude WTI was also softer, at $88.72 for November delivery.
Bond markets joined the rally. European government yields eased, with French debt helping lead the move after comments from Marine Le Pen on bringing the deficit below 3% of GDP by 2032 supported confidence. For equity investors, falling yields are often just as important as cheaper oil: they improve the relative appeal of stocks and support valuations, especially in rate-sensitive sectors such as banks and industrials.
In Milan, that combination showed up in the market tape. Energy names lagged, with Eni, Saipem and Tenaris under pressure, while banks such as Intesa Sanpaolo and Bper posted gains. That is the classic rotation you tend to see when inflation anxiety cools a bit: lenders and domestic cyclicals can recover, while oil producers give back some of the year’s outperformance.
The broader message for long-term investors is straightforward. A retreat in crude below $100 does not end inflation risk, but it does reduce one of the biggest sources of near-term macro stress. If inflation expectations keep easing and bond yields stay contained, European equities have room to keep grinding higher even if growth remains only moderate.
The next test is whether that relief lasts. Investors are watching U.S. PCE inflation, second-quarter U.S. GDP, and fresh economic data from Italy and Germany for clues on whether the current calm in energy and rates can hold. For now, the setup looks more constructive for stocks than for oil.
| Entity | Gains | Losses |
|---|---|---|
| European equities | ▲Easier inflation backdrop | ▼None immediately |
| Energy producers | ▲None | ▼Lower crude prices |
| Banks and cyclicals | ▲Lower yield pressure | ▼Less relative dominance for oil names |
| Bond investors | ▲Softer rate expectations | ▼Less haven demand for ultra-safe positioning |