European stocks were set for a firmer tone as a pullback in oil prices eased pressure on inflation and bond yields, while a stronger-than-expected euro zone PMI reading reinforced hopes the region can keep growing despite geopolitical uncertainty.
European Stocks Rise on Softer Oil and Strong PMI
The move matters because lower crude prices can reduce some of the immediate inflationary strain on households and businesses, giving policymakers and investors a little more room to breathe after weeks of energy-driven volatility. A less aggressive oil backdrop also helps temper bond-market pressure, which has been weighing on rate-sensitive parts of the market.
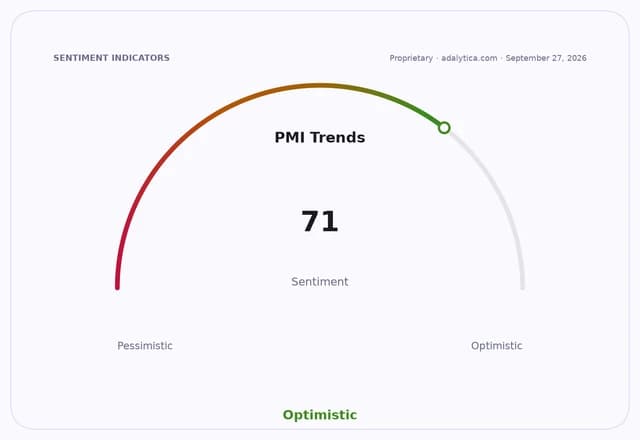
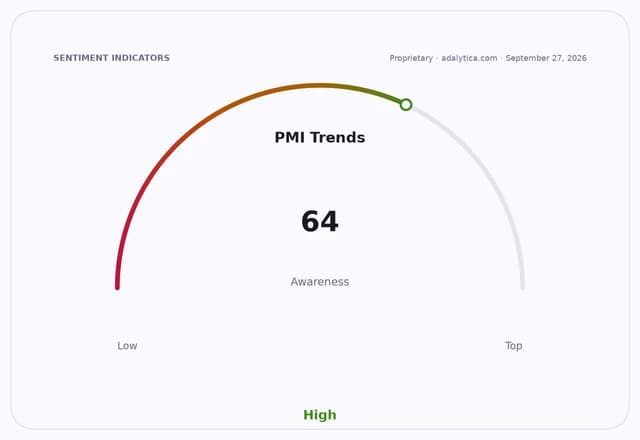
Sentiment IndicatorsⓘProprietary · adalytica.com · September 27, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The pan-European STOXX 600 has been buffeted by swings in crude and sovereign yields, with energy shares the clearest beneficiaries when oil climbs and banks, insurers and construction stocks typically more exposed when yields and financing costs rise. That trade is still playing out against a tense geopolitical backdrop, with traders watching whether the conflict involving Iran and the US broadens or de-escalates.
Adding to the upbeat tone, an S&P Global survey showed euro zone business activity accelerating at the fastest pace in more than three years, a sign the bloc’s economy is holding up better than many expected. For investors, that strengthens the case that recent gains in European equities are being supported by both cyclical recovery and easing energy stress, not just a short-lived relief rally.
Oil itself remains a key market driver. The Brent-linked BNO ETF has been volatile, and although recent pullbacks have eased some pressure, technical indicators including the 14-day RSI and MACD still point to an asset that has been trading with elevated momentum.
Stocks are also facing a global macro test from US-China trade talks and the next leg of bond-market moves, with traders still wary that any renewed spike in crude could quickly reverse sentiment. For now, though, the combination of softer oil and stronger PMI data gives European equities a better near-term backdrop, especially for sectors hit hardest by higher energy costs and financing rates.
| Entity | Gains | Losses |
|---|---|---|
| European equities | ▲Better sentiment, lower inflation pressure | ▼Profit-taking if yields rebound |
| Energy shares | ▲Relative outperformance when oil rises | ▼Easing crude prices |
| Rate-sensitive sectors | ▲Relief from lower bond-yield pressure | ▼Still vulnerable if yields climb |
| Consumers and importers | ▲Lower fuel and input costs | ▼Producers tied to higher oil prices |